What's more, part of that Test4Cram F3 dumps now are free: https://drive.google.com/open?id=1muiQiyIltE_lhudDOK13nNQNZnmvVXyu
Remember that this is a crucial part of your career, and you must keep pace with the changing time to achieve something substantial in terms of a certification or a degree. So do avail yourself of this chance to get help from our exceptional F3 Financial Strategy (F3) dumps to grab the most competitive CIMA F3 certificate. Test4Cram has formulated the F3 Financial Strategy (F3) product in three versions. You will find their specifications below to understand them better.
| Section | Weight | Objectives |
|---|---|---|
| Mergers, Acquisitions and Business Valuation | 10% | - Valuation and deal structure
|
| Investment Appraisal and Decisions | 25% | - Investment evaluation techniques
|
| Financial Strategy Framework | 25% | - Financial objectives and stakeholder value
|
| Financial Risk Management and Treasury | 10% | - Risk management techniques
|
| Corporate Finance | 30% | - Financing decisions
|
The high efficiency method is targeted learning rather than comprehensive learning. Comprehensive learning can improve your basic knowledge but it is not the best to clear exams and obtain certifications. Our valid CIMA F3 exam cram review can help you pass this subject in a short time. If your goal is passing all exams and obtain a useful certification. The best shortcut is to buy Valid F3 Exam Cram Review. Most experienced people can prove that. Good products are here waiting for you.
NEW QUESTION # 402
A company wishes to raise new finance using a rights issue. The following data applies:
* There are 20 million shares in issue with a market value of $6 each
* The terms of the rights will be 1 new share for 4 existing shares held
* After the rights issue, the theoretical ex-rights price (TERP) will be $5.75 Assuming all shareholders take up their rights, how much new finance will be raised ?
Give your answer to one decimal place.
Answer:
Explanation:
$ ? million
7.5, 7.50Workings:Existing shares = 20m at $6 # current value = 20m × 6 = $120mRights: 1 new for 4 existing # New shares = 20m / 4 = 5mTotal shares after issue = 20m + 5m = 25mTERP after issue = $5.75Use TERP to back out funds raised (X):120+X25=5.75\frac{120 + X}{25} = 5.7525120+X=5.75 120+X=25×5.
75=143.75120 + X = 25 \times 5.75 = 143.75120+X=25×5.75=143.75 X=143.75#120=23.75 millionX =
143.75 - 120 = 23.75 \text{ million}X=143.75#120=23.75 million Rounded to 1 decimal place: $23.8 million
NEW QUESTION # 403
A company has:
* A price/earnings (P/E) ratio of 10.
* Earnings of $10 million.
* A market equity value of $100 million.
The directors forecast that the company's P/E ratio will fall to 8 and earnings fall to $9 million.
Which of the following calculations gives the best estimate of new company equity value in $ million following such a change?
A)
B)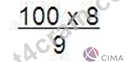
C)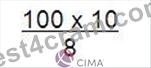
D)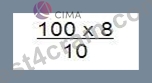
Answer: B
NEW QUESTION # 404
A company is considering whether to lease or buy an asset.
The following data applies:
* The bank will charge interest at 7.14% per annum
* The asset will cost $1 million
* Tax-allowable depreciation is available on a straight line basis over 5 years
* There is no residual value
* Corporate tax is paid at 30% in the year when the profit is earned
What is the NPV of the buy option?
Give your answer to the nearest $000.
Answer:
Explanation:
$ ?
$740,000 (negative NPV of buy option)Under CIMA F3's lease-or-buy framework, the buy option is evaluated by discounting the after-tax cash flows associated with owning the asset. When an asset is purchased, the immediate cash outflow is the purchase price, but ownership provides a benefit through tax- allowable depreciation, which creates an annual tax shield (a reduction in tax payable). Because corporate tax is paid in the same year that profit is earned, the depreciation tax shield arises each year from Year 1 to Year 5.
Step 1: Initial cost (Year 0 outflow)Asset cost = $1,000,000 (cash outflow at time 0).Step 2: Annual tax depreciation and tax shieldStraight-line over 5 years, no residual value:Depreciation = 1,000,000/5=200,0001
{,}000{,}000 / 5 = 200{,}0001,000,000/5=200,000 per year.Tax shield each year = 200,000×30%=60,000200
{,}000 \times 30\% = 60{,}000200,000×30%=60,000.Step 3: Discount rateCIMA F3 applies the after-tax cost of debt when valuing tax-deductible flows funded by borrowing:After-tax discount rate = 7.14%×(1#0.30)=4.
998%#5%7.14\% \times (1 - 0.30) = 4.998\% \approx 5\%7.14%×(1#0.30)=4.998%#5%.Step 4: Present value of tax shields (5-year annuity at 5%)Annuity factor = 1#(1.05)#50.05=4.32948\frac{1 - (1.05)
P.S. Free & New F3 dumps are available on Google Drive shared by Test4Cram: https://drive.google.com/open?id=1muiQiyIltE_lhudDOK13nNQNZnmvVXyu