Übrigens, Sie können die vollständige Version der ITZert IIA-CIA-Part3 Prüfungsfragen aus dem Cloud-Speicher herunterladen: https://drive.google.com/open?id=1_pT3sRFd4PukL9OyVoUh8UNCIoVwSHQ3
Wir suchen die Methode des Erfolgs, aber nicht die Ausrede des Misserfolgs. Um zu garantieren, dass die Prüfungsunterlagen der IIA IIA-CIA-Part3 für Sie am verlässlichsten ist, haben die IT-Profis von ITZert seit Jahren die Prüfungsaufgaben der IIA IIA-CIA-Part3 sorgfältig analysiert und die ausführliche Erklärungen geordnet. Die Zertifizierung der IIA IIA-CIA-Part3 ist der überzeugende Beweis für Ihre IT-Fähigkeit und wird in Ihrem Berufsleben eine große Rolle spielen.
Die IIA-CIA-Part3-Prüfung ist eine Zertifizierungsprüfung, die vom Institute of Internal Auditors (IIA) angeboten wird. Es ist Teil des CIA -Zertifizierungsprogramms für interne Auditor (Certified Internal Auditor), das das Wissen und die Fähigkeiten von internen Prüfern verbessern soll. Die IIA-CIA-Part3-Prüfung konzentriert sich auf Geschäftswissen für interne Prüfung und ist für Personen bestimmt, die ihr Verständnis für Geschäftsbetriebe und Management verbessern möchten.
Die Zertifizierungsprüfung von IIA IIA-CIA-Part3 ist ein unerlässlicher Teil im IT-Bereich. Aber wie kann man in kurzer Zeit bessere Resulate bei weniger Einsatz erzielen? ITZert ist Ihre beste Wahl. Die Schulungsunterlagen zur IIA IIA-CIA-Part3 Zertifizierungsprüfung von ITZert sind von erfahrenen IT-Experten entworfen, deren Korrktheit zweifellos ist. Wenn Sie noch besorgt sind, können Sie einen Teil von den kostenlosen Testaufgaben und Antworten herunterladen, bevor Sie die Schulungsunterlagen von ITZert benutzen.
Die IIA-CIA-Part3-Prüfung ist eine Zertifizierungsprüfung, die entworfen wurde, um das Wissen und die Fähigkeiten von Personen zu testen, die an einer Karriere als interner Auditor interessiert sind. Diese Prüfung ist Teil des Certified Internal Auditor (CIA)-Programms, das vom Institute of Internal Auditors (IIA) angeboten wird und konzentriert sich auf das für interne Revision erforderliche Geschäftswissen.
236. Frage
An internal auditor is reviewing the sales and collections processes of an e-commerce organization that is facing budget constraints. The auditor found that the accountant did not perform reconciliations of cash collections in a timely manner. The auditor determined that the reason was timing errors in the interfacing process between the customer payments portal and the accounting system. The current customer payments portal was recently implemented to replace a legacy system. The finance manager is in charge of the customer payments portal. Which of the following recommendations is the most appropriate to address the root cause of this deficiency?
Antwort: B
Begründung:
The root cause is the system interface errors between the customer payments portal and the accounting system. The most appropriate recommendation is for the finance manager to collaborate with IT and the system vendor to correct the interfacing issue.
Option A (manual workaround) is temporary and inefficient. Option B (new portal) is costly and unnecessary when the existing one can be fixed. Option D addresses symptoms but not the root cause.
Reference:
IIA Standards - Standard 2130: Control; GTAG - Business and IT Alignment.
237. Frage
Refer to the exhibit.
The figure below shows the network diagram for the activities of a large project. What is the shortest number of days in which the project can be completed?
Antwort: C
238. Frage
The entity has an accounts receivable balance of:
Antwort: C
Begründung:
Total assets equal total liabilities and equity. Hence, if total assets equal US $100. Total liabilities and equity must equal US $100, and current liabilities must equal US $30 $100 $40 - $30). Because the quick ratio equals the quick assets cash + accounts receivable) divided by current liabilities, the quip-k assets must equal US $36 $30 x 1.2 quick ratio), and the accounts receivable balance is US $26 $36 I- $10 cash). An entity has a current ratio of 14, a quick, or acid test, ratio of 12, and the following partial summary balance sheet: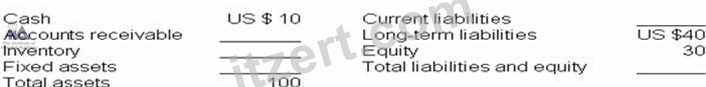
239. Frage
In a diluted earnings-per-share computation, outstanding options issued by the reporting entity are assumed to be exercised. If the exercise price of these options exceeds the average market price, the computation would:
Antwort: C
Begründung:
Options and warrants instruments that give the holders the right to purchase ordinary shares of the entity) issued by the reporting entity are assumed to be exercised at the beginning of the period or at time of issuance, if later. The proceeds are assumed to be from an issuance at the average market price for the period. The difference between 1) the shares issued and 2) the shares that would have been issued at the average market price is an issue for no consideration. If the options are in the money exercise price is less than average market price), they are dilutive because 1) exceeds 2), and the excess will be added to the BEPS denominator. However, when the exercise price exceeds the average market price, the result is ant dilutive.
240. Frage
Which of the following is not true about international transfer prices for a multinational firm?
Antwort: C
Begründung:
The calculation of transfer prices in the international arena must be systematic. A scheme for calculating transfer prices for a firm may correctly price the firm's product in Country A but not in Country B. The product may be overpriced in Country B, causing sales to be lower than anticipated. Alternatively, the product may be underpriced in Country B, and the authorities may allege that the firm is dumping its product there.
241. Frage
......
IIA-CIA-Part3 Prüfungsfragen: https://www.itzert.com/IIA-CIA-Part3_valid-braindumps.html
Laden Sie die neuesten ITZert IIA-CIA-Part3 PDF-Versionen von Prüfungsfragen kostenlos von Google Drive herunter: https://drive.google.com/open?id=1_pT3sRFd4PukL9OyVoUh8UNCIoVwSHQ3