DOWNLOAD the newest Dumpcollection Accounting-for-Decision-Makers PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1FHu4kXFVDk4mMJMceOlqv50YCqnXbSum
By clearing different WGU exams, you can easily land your dream job. If you are looking to find high paying jobs, then WGU certifications can help you get the job in the highly reputable organization. Our Accounting-for-Decision-Makers exam materials give real exam environment with multiple learning tools that allow you to do a selective study and will help you to get the job that you are looking for. Moreover, we also provide 100% money back guarantee on our Accounting-for-Decision-Makers Exam Materials, and you will be able to pass the Accounting-for-Decision-Makers exam in short time without facing any troubles.
| Section | Weight | Objectives |
|---|---|---|
| Profit Planning | 10–15% | - Cost-volume-profit (CVP) analysis
|
| Controls and Regulations | 10–15% | - Internal control systems and principles
|
| Financial Analysis | 45–50% | - Financial statement analysis techniques
|
| Budgeting and Decision Making | 10–15% | - Relevant information for decision making
|
| Cost Systems | 20–25% | - Costing methods
|
>> Accounting-for-Decision-Makers Pass Rate <<
For certificates who will attend the exam, some practice is evitable. But sometimes, time for preparation is quite urgent. Accounting-for-Decision-Makers exam braindumps of us will help you to use the least time to pass the exam. If you choose the Accounting-for-Decision-Makers exam dumps of us, you just need to spend about 48 to 72 hours to practice and you can pass the exam successfully. In addition, Accounting-for-Decision-Makers Exam Dumps are verified by experienced experts, and the accuracy and correctness can be guaranteed. And we pass guarantee and money back guarantee if can’t pass the exam.
NEW QUESTION # 53
Which information does a balance sheet provide about a company?
Answer: A
Explanation:
A balance sheet shows the company's financial position at a specific point in time , so Option C is correct.
It reports what the business owns (assets), what it owes (liabilities), and usually owners' or stockholders' equity as of a particular date. This is why the balance sheet is often described as a snapshot rather than a report covering a span of time. Authoritative accounting learning materials describe the balance sheet as presenting assets, liabilities, and equity "as of" a date or at a specific moment.
Option A is incorrect because revenues and expenses for a period of time belong to the income statement , not the balance sheet. Option D is incorrect because cash collections and cash expenditures for a period of time are presented in the statement of cash flows . Option B is also incorrect because cash inflows and outflows are not reported only at a single point in time; they are summarized over a period. Therefore, the best answer is the one identifying the balance sheet as a statement of assets and liabilities at a specific point in time .
NEW QUESTION # 54
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.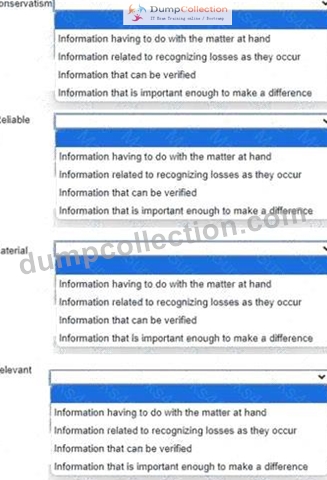
Answer:
Explanation: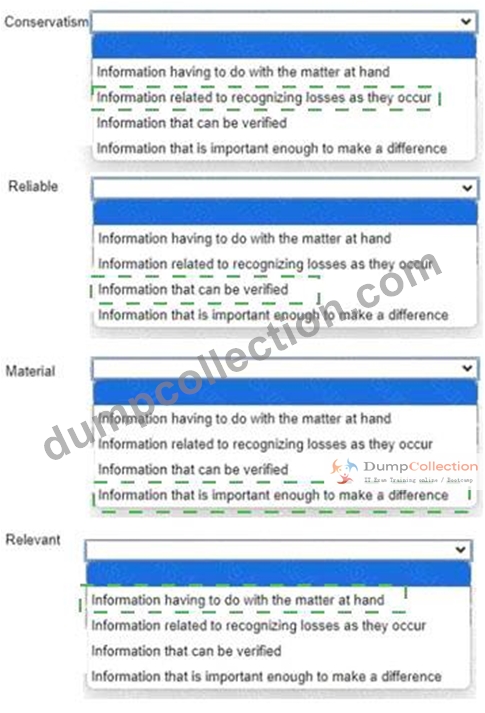
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 55
Which body regulates a certified public accounting firm's audit practices when the firm is auditing a large, publicly traded company?
Answer: D
Explanation:
The correct answer is D. The Public Company Accounting Oversight Board (PCAOB) . The PCAOB was created to oversee the audits of public companies and SEC-registered brokers and dealers in order to protect investors and support the public interest in accurate, independent audit reports. Its responsibilities include registration of audit firms, inspections, enforcement, and audit-related standard-setting. Because the question refers to a CPA firm auditing a large, publicly traded company , PCAOB oversight is the correct regulatory answer.
Option A is incorrect because FASB sets accounting standards, not audit practice regulation for public company auditors. Option B, FASAC , is an advisory council to FASB and does not regulate audit firms.
Option C, the IRS , administers tax laws and does not oversee external audit practices for public companies.
In accounting and auditing, it is essential to distinguish between those who set accounting rules and those who supervise auditors. For publicly traded companies, that audit oversight role belongs to the PCAOB , making Option D the only accurate choice.
NEW QUESTION # 56
What does it mean if a company has a debt ratio of 101.5%?
Answer: A
NEW QUESTION # 57
Which act was implemented as a result of the corporate scandals at companies such as Enron and WorldCom?
Answer: A
Explanation:
The correct answer is D. Sarbanes-Oxley Act . The Sarbanes-Oxley Act of 2002 (SOX) was enacted in response to major corporate frauds, including those involving Enron and WorldCom . The U.S. Securities and Exchange Commission has described the law as a response to these financial frauds and the failures of corporate gatekeepers, with the goal of restoring investor confidence and strengthening accountability in financial reporting and auditing.
Option A is incorrect because "Corporate Accountability Act" is not the recognized statute that addressed those scandals. Option B is incorrect because the Securities Exchange Act of 1934 is an earlier law governing securities markets, not the specific reform enacted after Enron and WorldCom. Option C is also incorrect because "Auditing Accountability Act" is not the proper title of the law passed for this purpose.
SOX introduced important reforms such as stronger internal control requirements, auditor independence rules, executive certification of financial reports, and the creation of the PCAOB. These changes were designed to improve the reliability of financial statements and protect investors. Therefore, the only accurate answer is Sarbanes-Oxley Act .
NEW QUESTION # 58
......
As long as you study with our Accounting-for-Decision-Makers exam braindump, you can find that it is easy to study with the Accounting-for-Decision-Makers exam questions. Therefore, even ordinary examiners can master all the learning problems without difficulty. In addition, Accounting-for-Decision-Makers candidates can benefit themselves by using our test engine and get a lot of test questions like exercises and answers. They will help them modify the entire syllabus in a short time. The most important thing is that our Accounting-for-Decision-Makers Practice Guide can help you obtain the certification without difficulty.
Exam Accounting-for-Decision-Makers Details: https://www.dumpcollection.com/Accounting-for-Decision-Makers_braindumps.html
P.S. Free 2026 WGU Accounting-for-Decision-Makers dumps are available on Google Drive shared by Dumpcollection: https://drive.google.com/open?id=1FHu4kXFVDk4mMJMceOlqv50YCqnXbSum