BTW, DOWNLOAD part of PremiumVCEDump AFP-Exam-1 dumps from Cloud Storage: https://drive.google.com/open?id=1SCyz-4DQqtsugu6v2OXzzliNHcJpCqWe
The PremiumVCEDump CSI AFP-Exam-1 exam dumps are being offered in three different formats. The names of these formats are AFP-Exam-1 PDF questions file, desktop practice test software, and web-based practice test software. All these three Applied Financial Planning Certification Exam 1 (AFP) exam dumps formats contain the real CSI AFP-Exam-1 Exam Questions that will help you to streamline the AFP-Exam-1 exam preparation process.
| Section | Weight | Objectives |
|---|---|---|
| Enabling Competencies | 16% | - Client Relationship and Practice Management - Professional Conduct and Regulatory Compliance |
| Technical Competencies | 84% | - Estate Planning - Investment Planning - Risk Management and Insurance - Retirement Planning - Tax Planning - Asset and Liability Management |
>> Exam AFP-Exam-1 Objectives Pdf <<
We are a certification exam dumps website that meets the needs of many IT workers who are going to participate in the CSI AFP-Exam-1 real exam. Our colleagues will always check the updating of AFP-Exam-1 practice questions and the similarity of real question is almost 100%. It will be not difficult for candidates to clear AFP-Exam-1 Exam Braindumps if they are good at considering and conclude except practicing AFP-Exam-1 dumps pdf.
NEW QUESTION # 101
Bill is reviewing his credit bureau after being declined for a loan. He believes a loan that does not belong to him is appearing on the report. Which section should he review most closely?
Answer: A
Explanation:
A liability that appears to belong to Bill would normally be found in the account history or trade-line section of the credit bureau. That section lists credit facilities such as loans, credit cards, lines of credit, balances, payment status, limits, and delinquency history. Option A is relevant when reviewing who accessed the report, but an inquiry is not itself a liability. Option B may show judgments, bankruptcies, or other public- record items, but a regular loan account is more likely to appear in account history. Option D should still be checked because identity errors can cause mixed files, but it is not where the disputed liability would usually be described. The planner should advise Bill to obtain the full report, identify the creditor, dispute inaccurate information with the bureau and lender, and retain supporting documentation. Credit accuracy matters because lenders assess repayment history, outstanding debt, utilization, and derogatory information when approving credit. References/topics: credit bureau review, account history, borrowing capacity, liability management.
NEW QUESTION # 102
Richard pays periodic spousal support and child support under a written separation agreement. Which statement is generally correct?
Answer: C
Explanation:
Tax treatment depends on the type of support. Periodic spousal support paid under a qualifying written agreement or court order is generally deductible to the payer and taxable to the recipient. Child support is generally not deductible to the payer and not taxable to the recipient. Option B wrongly treats child support like deductible spousal support. Option C confuses payment frequency with tax character; monthly payment does not make child support taxable. Option D is plainly incorrect because spousal support can materially affect after-tax cash flow for both parties. A financial planner should distinguish periodic support from lump- sum settlements, property transfers, arrears, legal fees, and combined agreements because classification changes projections. The planner should also ensure tax assumptions follow the wording of the agreement and should recommend legal or tax advice where facts are unclear. The planning result is measured on after-tax cash flow, not simply the gross support amount. References/topics: support payments, divorce planning, cash flow, tax deductibility.
NEW QUESTION # 103
Ali wishes to retire in five years. His financial planner calculates that he needs to save an additional $40,000 to meet his retirement income objectives. What would Ali's financial planner advise him to do in order to meet his retirement income objectives?
Answer: B
Explanation:
With only five years until retirement, Ali's planner should recommend reducing current expenses and redirecting the freed cash flow to retirement savings. The short time horizon makes aggressive corrective strategies dangerous. Borrowing through a mortgage to invest introduces leverage risk and could worsen retirement security if markets underperform. Increasing equity exposure solely to chase a higher return may be inconsistent with the time horizon and risk capacity. Whole life insurance is not an efficient solution for a near-term retirement savings shortfall; it combines insurance and investment features but does not directly solve a five-year funding gap. Expense reduction is controllable, immediate, and aligned with the identified
$40,000 savings need. The planner should quantify how much monthly savings is required and monitor progress annually. Study Guide focus: retirement shortfall strategies, savings rate, time horizon, risk capacity, leverage risk, and expense management. The recommendation is conservative because the closer the retirement date, the less time Ali has to recover from investment error.
NEW QUESTION # 104
Kendrick, age 55, owns a successful small business, ZXC Inc., valued at $800,000. Kendrick has extensive savings outside of the business and would like to pass the company onto his son at some point in the future.
Kendrick expects the business to increase in value $25,000 per year. If Kendrick decides to use an estate freeze to reduce the amount of taxes he will be required to pay, his financial planner should recommend that he implement the estate freeze at which point in relation to gifting the business to his son?
Answer: C
Explanation:
The estate freeze should be implemented immediately if Kendrick expects the business to continue appreciating. The purpose of the freeze is to lock in the current value of the owner's interest, usually by exchanging growth shares for fixed-value preferred shares, while future growth accrues to the successor generation or a trust. Waiting until the gift date, one month before the gift, or death allows additional appreciation to remain taxable to Kendrick. Since the company is already valued at $800,000 and expected to grow by $25,000 per year, every year of delay increases the value exposed to future tax in Kendrick's estate.
A freeze also needs legal and tax design, including valuation, share terms, control, income needs, and succession intentions. Among the options, immediate implementation best achieves the objective of reducing future tax growth in his hands. Study Guide focus: estate freezes, business succession, preferred shares, future growth transfer, and tax minimization.
NEW QUESTION # 105
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: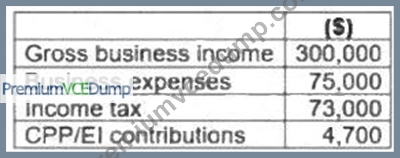
What is Terry's net business income?
Answer: D
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 106
......
Many candidates failed exam before. They have no confidence for next exam and they also hesitate if they have to purchase valid AFP-Exam-1 brain dumps materials or if dumps are actually valid. Now I advise you download our free demo before you are determined to buy. Our free demo is a little of the real test, you can see several questions answers and explanations. You will know the validity of CSI AFP-Exam-1 Brain Dumps materials.
AFP-Exam-1 Examcollection Dumps Torrent: https://www.premiumvcedump.com/CSI/valid-AFP-Exam-1-premium-vce-exam-dumps.html
P.S. Free & New AFP-Exam-1 dumps are available on Google Drive shared by PremiumVCEDump: https://drive.google.com/open?id=1SCyz-4DQqtsugu6v2OXzzliNHcJpCqWe