DOWNLOAD the newest PrepPDF ClaimCenter-Business-Analysts PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1RcnETIBMd788OmGFKH5bvLnJZ3oU68Yh
The page of our ClaimCenter-Business-Analysts simulating materials provides demo which are sample questions. The purpose of providing demo is to let customers understand our part of the topic and what is the form of our ClaimCenter-Business-Analysts study materials when it is opened? In our minds, these two things are that customers who care about the ClaimCenter-Business-Analysts Exam may be concerned about most. We will give you our software which is a clickable website that you can visit the product page.
| Certification Vendor: | Guidewire |
|---|---|
| Exam Name: | ClaimCenter Business Analyst - Mammoth Proctored Exam |
| Exam Number: | ClaimCenter-Business-Analysts |
| Available Languages: | English |
| Exam Format: | Multiple Select, Scenario-based Questions, Multiple Choice |
| Real Exam Qty: | 50-70 (varies by version) |
| Related Certifications: | Guidewire InsuranceSuite Analyst Certification |
| Exam Registration: | Guidewire Education Portal |
| Sample Questions: | Guidewire ClaimCenter-Business-Analysts Sample Questions |
| Exam Way: | Online proctored (Mammoth Proctored Exam) |
| Pre Condition: | Recommended: Guidewire InsuranceSuite Analyst foundational training (no strict formal prerequisite publicly specified) |
>> ClaimCenter-Business-Analysts Test Free <<
Our ClaimCenter-Business-Analysts exam braindumps offer you a wide and full coverage of the keypoints on the career-oriented certification and help you pass the exam without facing any difficulty. And you will find that the subject is well compiled to the content of the ClaimCenter-Business-Analysts training guide in our three different versions. They are the PDF, Software and APP online. The content of these versions is the same, but the displays of our ClaimCenter-Business-Analysts learning questions are all different. You can choose the favorate one.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
| Topic 5 |
|
NEW QUESTION # 36
When creating a new Personal Auto claim, Succeed Insurance would like to identify when Rideshare is the primary use for a vehicle. A Business Analyst (BA) thinks that Primary Use already exists as a typekey on the Vehicle Details screen.
What are two ways the BA can confirm whether this field is configured in ClaimCenter and, if it is, which values are available in the typelist? (Choose two.)
Answer: C,D
Explanation:
To verify the configuration of a specific field and its available values (typelist) within a specific implementation (like Succeed Insurance), a Business Analyst must consult the sources that reflect the current, actual system configuration, not just the out-of-the-box documentation.
* Option A (Data Dictionary):TheData Dictionaryis the definitive, generated documentation of the running application's data model. It lists allEntities(such as Vehicle) and theirTypekeys(such as PrimaryUse). By navigating to the Data Dictionary, a BA can confirm if the field exists in the database schema and view the specificTypelistvalues (e.g., "Rideshare", "Commuting", "Pleasure") associated with it. This is a primary tool for BAs to understand the data structure.
* Option D (Guidewire Studio):Guidewire Studiois the Integrated Development Environment (IDE) used to configure the application. It contains the "Source of Truth" for all configuration files. A BA (or a developer assisting them) can open thePage Configuration (PCF)files to see the Vehicle Details screen definition or open theTypelistfiles (.tti/.ttx) directly to see exactly which values are defined and active.
Why other options are incorrect:
* Option B (Application Guide):The Application Guide documents theBase (Out-of-the-Box)product features. It does not contain customer-specific customizations or extensions. If "Primary Use" or
"Rideshare" were added or modified by Succeed Insurance, the Application Guide would not reflect this.
* Option C (UI Inspection with CTRL+F):While logging into the application allows a user to see the dropdown on the screen, the shortcutCTRL + Fis merely the browser's "Find" function. It searches visible text on the page but does not provide configuration metadata, hidden values, or definitive proof of the underlying data model structure. The correct shortcut for inspecting widget properties in Guidewire is Alt + Shift + I (Location Info), but even that is less efficient for viewing a full typelist than the Data Dictionary or Studio.
NEW QUESTION # 37
Which set of three objects is required to create a liability exposure?
Answer: D
Explanation:
In the Guidewire ClaimCenter object model, a Liability Exposure represents a specific potential financial obligation to a third party. To successfully instantiate (create) a new exposure record, the system requires three fundamental data associations to define "Who, What, and How":
* Claimant:The specific person or entity seeking compensation (the "Who"). Every exposure must be linked to a contact designated as the claimant.
* Coverage (Type and Subtype):The specific contractual provision from the policy that applies to the loss (the "How"). The exposure must link back to a valid coverage on the verified policy to confirm the insurer is liable.
* Incident:The specific details of the event or damage (the "What"). In ClaimCenter, anIncidentis a distinct object (e.g., Vehicle Incident, Injury Incident) that captures the facts of the loss. Multiple exposures can link to the same incident (e.g., Bodily Injury and Property Damage exposures both linking to the same Vehicle Incident), but every exposure requires one underlying incident to define the scope of the damage.
Why other options are incorrect:
* Reserve Line (A, C, D):A Reserve Line is a financial accounting object createdafterthe exposure exists to set aside funds. It is a child object of the exposure, not a prerequisite for creating the exposure itself.
NEW QUESTION # 38
Succeed Insurance requires that a new 'Driver under 18?' field be added to the vehicle incident screen for personal auto claims to indicate whether or not the driver of the vehicle was a minor when the loss occurred.
The field will be set by calculating the driver's age using the date of loss and the driver's date of birth.
There are two validation requirements:
* The field must be set if the 'Date of Birth' field for the driver is not null.
* No payments can be made for collision exposures if the 'Date of Birth' field for the driver of the vehicle is null.
A Business Analyst (BA) documents the validation requirements in the validation tab of the User Story Card
'Adjudicate - Update Maintain Vehicle Incident for Personal Auto Claims' as shown in the exhibit.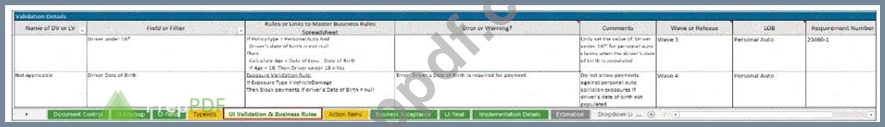
What information in the two validation examples is either missing or incorrectly documented? (Choose two.)
Answer: A,C
Explanation:
The User Story Card exhibit contains several documentation errors when compared to standard Guidewire requirements gathering best practices and the specific scenario provided.
* Missing Requirement Number and Logic Gap (Option C):
* Traceability:In the second row of the exhibit (the payment validation rule), the "Requirement Number" column is completely blank. Traceability back to the original requirements document is mandatory for all entries.
* Logic Precision:The requirement explicitly states that the rule applies to"personal auto claims"
. However, the logic documented in the "Rules" column (If Exposure Type = VehicleDamage Then Block...) doesnotcheck the Policy Type. It relies solely on the Exposure Type, which could exist on Commercial Auto policies as well. To accurately reflect the business requirement, the condition If PolicyType = Personal Auto must be added (similar to how it was done in the first row).
* Missing DV/LV Context for Validation (Option D):
* UI Anchoring:The second requirement is a validation rule that triggers an error ("Driver's Date of Birth is required..."). For the system to highlight the specific field on the screen (the "Driver Date of Birth" widget) when the error occurs, the rule must be associated with the specificDetail View (DV)orList View (LV)where that field resides (e.g., VehicleIncidentDV). The exhibit lists
"Not Applicable" in the "Name of DV or LV" column. This is incorrect because providing the DV name ensures the error message is displayed contextually next to the field rather than as a generic page-level error, improving the user experience.
Why other options are incorrect:
* Option A:The LOB column is used for filtering, reporting, and release management. Even if the rule logic checks the policy type, the LOB column is required metadata and should not be removed.
* Option B:While the first requirement (the calculation) lacks a DV name (which it should have), it is a Business Rule(assignment), not a validation. Therefore, it doesnotgenerate an error or warning message for the user, so the second part of Option B is incorrect.
* Option E:The "Rules" column is exactly where the calculation logic (Date of Loss - Date of Birth) belongs. The developer needs this information to implement the automation.
NEW QUESTION # 39
A claim for an auto accident in California has been assigned to an insurance Adjuster in the Midwest region for investigation and processing. The claim has been flagged as "Low Complexity" in ClaimCenter. The Adjuster has an authority limit for total reserves of $30,000 and has created reserves totaling $35,000.
What is the correct approval routing for this transaction?
Answer: A
Explanation:
Based on theGuidewire ClaimCenter Financials and Authority Limitsdocumentation, the correct behavior for this scenario is determined by the strict enforcement ofAuthority Limits, regardless of claim complexity or geographic region.
In ClaimCenter, every user is assigned specific authority limits for various financial transactions, including reserves, payments, and recovery reserves. These limits are absolute constraints designed to control financial exposure. In the scenario provided, the Adjuster attempted to set a reserve of$35,000, which exceeds their authorized limit of$30,000.
When a user submits a financial transaction that exceeds their pre-configured authority limit, ClaimCenter automatically triggers anApproval Workflow. The system validates the transaction amount against the user's limit at the time of submission. Since the limit is breached, the transaction is not committed immediately to the database as "Submitted"; instead, it enters a"Pending Approval"status.
Routing Logic:
The standard, out-of-the-box approval routing logic in ClaimCenter follows the Group Hierarchy.
* The system identifies the group to which the Adjuster belongs.
* It creates anApproval Activity.
* This activity is assigned to theSupervisorof that group.
The Supervisor must then review the transaction. If the Supervisor has sufficient authority (greater than
$35,000), they can approve it. If the Supervisor also lacks sufficient authority, they must still "approve" it to escalate the request further up the hierarchy totheirmanager, until it reaches a user with sufficient limits.
Why other options are incorrect:
* A (Complexity):Claim complexity flags (e.g., "Low Complexity") are often used forAssignmentrules (Segment-based assignment) or straight-through processing ofdocuments, but they do not override Financial Authoritycontrols. A low-complexity claim still requires financial oversight if the dollar amount is high.
* B (Peer Approval):Approval routing is hierarchical, not peer-to-peer. It does not look for "any" team member; it looks specifically for the defined Supervisor.
* C (Region):The region mismatch might trigger an assignment rule or a validation warning depending on configuration, but the specific trigger for theapprovalhere is purely the financial discrepancy ($35k
> $30k), not the geography.
NEW QUESTION # 40
Under the Travel loss type, Succeed Insurance offers personal travel policies as part of its travel line of business.
Which two pieces of information in the user interface (UI) will be different for a personal travel claim than for a personal auto or homeowners claim? (Choose two.)
Answer: A,D
Explanation:
Guidewire ClaimCenter is designed to support multiple Lines of Business (LOB), and the User Interface adapts dynamically based on the policy type associated with the claim.
* Incident Types (Option B):The "Incident" is the object that describes what was damaged or lost.
* ForAuto, the UI displaysVehicle Incidents(describing cars).
* ForHomeowners, the UI displaysDwellingorFixed Property Incidents.
* ForTravel, the UI will display distinct incident types such asBaggage Incident(for lost luggage) orTrip Cancellation Incident. These are fundamentally different data objects with different fields.
* Loss Causes (Option C):The LossCause typelist is filtered by the Line of Business.
* Autoclaims show causes like "Collision," "Rear-end," or "Theft of Vehicle."
* Travelclaims will show completely different values such as "Trip Delay," "Lost Baggage,"
"Medical Emergency," or "Cancellation."
Why other options are incorrect:
* Financial Summary (A):The structural format of the Financial Summary screen (displaying Reserve Lines, Payments, and Remaining Reserves) is a core system framework that remains consistent across all lines of business.
* Contact Information (E):The Contact entity (Name, Address, Phone) is a shared entity. The fields used to capture a person's details are generally the same whether they are a driver, a homeowner, or a traveler.
NEW QUESTION # 41
......
ClaimCenter-Business-Analysts Latest Exam Simulator: https://www.preppdf.com/Guidewire/ClaimCenter-Business-Analysts-prepaway-exam-dumps.html
BONUS!!! Download part of PrepPDF ClaimCenter-Business-Analysts dumps for free: https://drive.google.com/open?id=1RcnETIBMd788OmGFKH5bvLnJZ3oU68Yh