DOWNLOAD the newest Prep4King Financial-Management PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1pgCA_aRJk9Aog1XGCqrp4Hj3dAKETTG2
Passing the WGU Financial Management VBC1 certification test is an important step in professional development, and preparing with actual WGU Financial Management VBC1 exam questions can help applicants achieve this certification. The Financial-Management Study Material promotes an organized approach to studying, aid applicants in identifying areas for development, build confidence and reduces exam anxiety. Prep4King has created three formats for applicants to pass the WGU Financial Management VBC1 test on the first try.
| Section | Objectives |
|---|---|
| Topic 1: Financial Management Concepts | - Financial Environment
|
| Topic 2: Working Capital Management | - Current Asset Management
|
| Topic 3: Cost of Capital and Capital Structure | - Cost of Capital
|
| Topic 4: Financial Statement Analysis | - Ratio Analysis
|
| Topic 5: Time Value of Money | - Bond and Stock Valuation
|
| Topic 6: Capital Budgeting | - Decision Criteria
|
>> Reliable Financial-Management Exam Cram <<
As is known to us, a good product is not only reflected in the strict management system, complete quality guarantee system but also the fine pre-sale and after-sale service system. In order to provide the best Financial-Management study materials for all people, our company already established the integrate quality manage system, before sell serve and promise after sale. If you buy the Financial-Management Study Materials from our company, we can make sure that you will have the right to enjoy the 24 hours full-time online service.
NEW QUESTION # 31
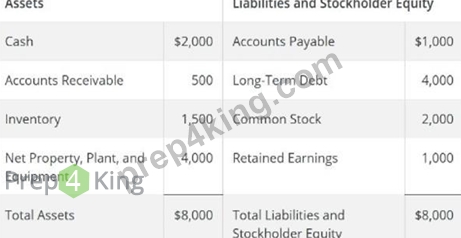
Use Whole Pine Inc.'s financial statements for 20X3 below to answer the following question.
What is Whole Pine Inc.'squick ratiofor 20X3?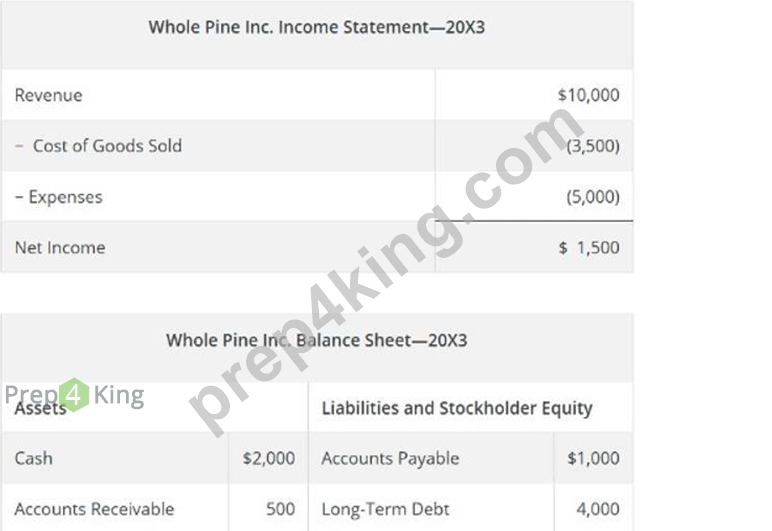
Answer: B
Explanation:
The quick ratio, also known as the acid-test ratio, measures a firm's ability to meet short-term obligations using its most liquid assets. It is calculated as:
(Cash + Accounts Receivable + Marketable Securities) ÷ Current Liabilities.
For Whole Pine Inc., quick assets include cash of $2,000 and accounts receivable of $500, totaling
$2,500. Inventory is excluded because it is less liquid and may not be easily converted into cash.
Current liabilities consist of accounts payable of $1,000. Dividing $2,500 by $1,000 yields a quick ratio of 2.50. This indicates that the firm has $2.50 in highly liquid assets for every $1.00 of short-term obligations, suggesting strong short-term liquidity. Option C correctly reflects this calculation and interpretation.
NEW QUESTION # 32
What is the difference between market orders and limit orders?
Answer: B
Explanation:
A market order instructs a broker to buy or sell a security immediately at the best available current market price. The main priority of a market order is speed of execution, not price certainty. In contrast, a limit order specifies the exact price at which an investor is willing to buy or sell. A buy limit order will only execute at the limit price or lower, while a sell limit order will only execute at the limit price or higher. The advantage of a limit order is price control, but the tradeoff is that the order may not be filled if the market never reaches the specified price. This distinction is important in capital markets because it affects trading strategy, transaction cost, and execution risk. Choice A reverses the real logic. Choice B is incorrect because both market and limit orders can be used for either buying or selling. Choice D is also incorrect because market orders do not execute at a fixed price; they execute at whatever the best available market price is at that moment. Therefore, C correctly states the fundamental difference between market orders and limit orders.
========
NEW QUESTION # 33
What are opportunity costs in the context of inventory management?
Answer: D
Explanation:
Opportunity cost represents the return a firm forgoes by investing resources in one use instead of the next best alternative. In inventory management, capital tied up in inventory cannot be used for other value-generating activities such as investing in new projects, paying down debt, or returning cash to shareholders. Financial management emphasizes opportunity cost as a key component of inventory carrying costs, along with storage, insurance, and obsolescence. Ignoring opportunity costs can lead to excessive inventory levels and reduced firm value. Option B correctly identifies this fundamental concept.
NEW QUESTION # 34
What is the significance of Section 302 of the Sarbanes-Oxley Act (SOX)?
Answer: B
Explanation:
Section 302 of the Sarbanes-Oxley Act requires a company's chief executive officer (CEO) and chief financial officer (CFO) to personally certify the accuracy and completeness of financial statements and disclosures. This certification affirms that management is responsible for establishing and maintaining effective internal controls and has evaluated their effectiveness. The provision was introduced to enhance accountability and restore investor confidence following major accounting scandals. By placing legal responsibility directly on senior executives, Section 302 strengthens corporate governance and reduces the likelihood of fraudulent reporting. Financial management and governance literature consistently highlight this section as a cornerstone of SOX compliance. Option A accurately reflects its purpose.
NEW QUESTION # 35
How does the use of historical returns to estimate the cost of common equity differ from the Gordon growth model?
Answer: C
Explanation:
The historical-return approach differs from the Gordon growth model because it is based primarily on past stock performance rather than on expected future dividends and growth. Under the historical-return method, analysts estimate the cost of common equity by examining the returns investors earned on the firm's stock over prior periods. The Gordon growth model, by contrast, is a forward-looking dividend-based approach that estimates the cost of equity as the expected dividend yield plus the constant growth rate of dividends. Choice D is correct because it captures the defining feature of the historical-return method. Choice B and choice C describe the Gordon growth model rather than the historical-return approach. Choice A is more closely associated with CAPM, which uses market risk and beta. Financial management often uses multiple methods to estimate the cost of equity because each approach has limitations. Historical returns can be useful as a reference point, but they may not reflect current risk or investor expectations. The Gordon growth model can be useful for stable dividend-paying firms, but it is less suitable for firms without predictable dividends.
Therefore, D correctly explains the main difference between these two valuation methods.
========
NEW QUESTION # 36
......
Prep4King WGU Financial Management VBC1 (Financial-Management) exam dumps save your study and preparation time. Our experts have added hundreds of WGU Financial Management VBC1 (Financial-Management) questions similar to the real exam. You can prepare for the WGU Financial Management VBC1 (Financial-Management) exam dumps during your job. You don't need to visit the market or any store because Prep4King WGU Financial Management VBC1 (Financial-Management) exam questions are easily accessible from the website.
Financial-Management Download: https://www.prep4king.com/Financial-Management-exam-prep-material.html
What's more, part of that Prep4King Financial-Management dumps now are free: https://drive.google.com/open?id=1pgCA_aRJk9Aog1XGCqrp4Hj3dAKETTG2