P.S. Free & New CIMAPRA19-F03-1 dumps are available on Google Drive shared by iPassleader: https://drive.google.com/open?id=1N8yKBMsdMJWBJq15RRbMhv2QhBviXXzY
iPassleader has made the F3 Financial Strategy (CIMAPRA19-F03-1) exam dumps after consulting with professionals and getting positive feedback from customers. The team of iPassleader has worked hard in making this product a successful CIMA CIMAPRA19-F03-1 Study Material. So we guarantee that you will not face issues anymore in passing the CIMA CIMAPRA19-F03-1 certification test with good grades.
CIMA CIMAPRA19-F03-1 (F3 Financial Strategy) Certification Exam is a globally recognized certification exam for candidates who wish to demonstrate their expertise in financial strategy. CIMAPRA19-F03-1 exam is designed to test candidates on their ability to analyze and evaluate financial information to develop and implement effective financial strategies. CIMAPRA19-F03-1 Exam covers various topics such as financial risk management, investment decisions, and valuation techniques.
>> Reliable CIMAPRA19-F03-1 Exam Braindumps <<
There are many merits of our exam products on many aspects and we can guarantee the quality of our CIMAPRA19-F03-1 practice engine. You can just look at the feedbacks on our websites, our CIMAPRA19-F03-1 exam questions are praised a lot for their high-quality. Our experienced expert team compile them elaborately based on the real exam and our CIMAPRA19-F03-1 Study Materials can reflect the popular trend in the industry and the latest change in the theory and the practice.
The F3 exam is a challenging exam that requires a strong understanding of financial concepts, as well as the ability to apply them in practical situations. Candidates are expected to have a good understanding of financial accounting and financial management, as well as a basic knowledge of economics and business strategy. CIMAPRA19-F03-1 Exam is designed to test candidates' ability to analyze financial information, make financial decisions, and communicate financial information to stakeholders. It is a crucial exam for anyone who wants to pursue a career in finance or accounting.
NEW QUESTION # 203
A company gas a large cash balance but its directors have been unable to identify any positive NPV projects to invest in.
Which THREE of the following are advantages of a share repurchase, compared with a one-off large dividend?
Answer: A,D,E
Explanation:
A). The shareholder can choose whether to take the cash or not.
With a repurchase, shareholders can decide to sell (take cash) or keep their shares. A one-off dividend forces all shareholders to receive cash.
C). It means that the company will be able to pay lower total dividends in the future.
After a buyback there are fewer shares in issue. If the company keeps the same dividend per share, the total dividend outlay falls - good for future cash flow and flexibility.
E). It will not create an expectation for future increased dividends.
A large one-off dividend may be interpreted as a permanent increase, creating pressure to maintain higher payouts. A buyback is seen as a more one-off, discretionary event, so it avoids that expectation.
B is wrong: a repurchase reduces, not increases, shares in issue.
D is not an advantage relative to a dividend - both methods return cash that shareholders can spend as they wish.
NEW QUESTION # 204
BBA is a wholly owned subsidiary of AAB BBA operates in country B where the currency is the B$.
The following is an extract from BBA's financial statements at 31 December 20X1: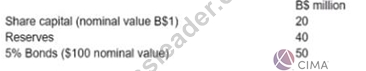
The following Information is relevant:
" The bonds were trading at $110 per $100 on 31 December 20X1. "Operating profit of BBA for the year ended 31 December 20X1 was S15 million
* The P/E ratio is 8
* Corporate income tax rate is 20%.
The tax authorities m country B Implemented thin capitalisation rules based on the level of gearing of the subsidiary, calculated as book value o( debt lo book value of equity The cut-off point for gearing used by the tax authorities for a company to be thinly capitalised is 75%.
Which of the following statements is correct as at 31 December 20X1?
Answer: B
NEW QUESTION # 205
Listed company R is in the process of making a cash offer for the equity of unlisted company S.
Company R has a market capitalisation of $200 million and a price/earnings ratio of 10.
Company S has a market capitalisation of $50 million and earnings of $7 million.
Company R intends to offer $60 million and expects to be able to realise synergistic benefits of $20 million by combining the two businesses. This estimate excludes the estimated $8 million cost of integrating the two businesses.
Which of the following figures need to be used when calculating the value of the combined entity in $ millions?
Answer: C
Explanation:
Calculation_F0
Calc_Set1
NEW QUESTION # 206
Company A is planning to acquire Company B. Both companies are listed and are of similar size based on market capitalisation No approach has yet been made to Company B's shareholders as the directors of Company A are undecided about the most suitable method of financing the offer Two methods are under consideration a share exchange or a cash offer financed by debt.
Company A currently has a gearing ratio (debt to debt plus equity) of 30% based on market values. The average gearing ratio (debt to debt plus equity) for the industry is 50% Although no formal offer has been made there have been market rumours of the proposed bid. which is seen as favorable to Company A. As a consequence. Company As share price has risen over the past few weeks while Company B's share price has fallen.
Which THREE of the following statements are most likely to be correct?
Answer: A,C
NEW QUESTION # 207
A company has undertaken a transaction with its shareholders which has had the following impact on its financial statements:
* Retained earnings has decreased
* Share capital has increased
* Earnings per share has decreased
* The book value of equity is unchanged
The company has undertaken a:
Answer: D
Explanation:
A scrip (or bonus) issue capitalises reserves: an amount is transferred from retained earnings to share capital.
Effects:
Retained earnings decrease (transfer out).
Share capital increases by the same amount.
Total equity (book value of equity) is unchanged (it's just a reclassification).
Number of shares increases, so with unchanged earnings, EPS decreases.
That matches exactly the effects listed, so the transaction is a scrip dividend.
NEW QUESTION # 208
......
CIMAPRA19-F03-1 Passguide: https://www.ipassleader.com/CIMA/CIMAPRA19-F03-1-practice-exam-dumps.html
What's more, part of that iPassleader CIMAPRA19-F03-1 dumps now are free: https://drive.google.com/open?id=1N8yKBMsdMJWBJq15RRbMhv2QhBviXXzY