CSIの認定資格を取得しようと懸命に努力している方もいらっしゃるかもしれませんが、当然、1つのレベルの重要な指標の1つに対する評価になります。 仕事を探すとき、もちろん、多くの会社は、Pass4Test人事マネージャーがあなたの能力を証明するためにAFP-Exam-1認定を取得した志願者に何を求めるのか、したがって、私たちが得た知識を証明するために他の方法を使用する必要があります AFP-Exam-1テスト準備を取得して資格証明書を取得し、包括的な能力のすべての側面を示すなど、大学で勉強しますApplied Financial Planning Certification Exam 1 (AFP)試験ガイドは、短期間で完璧に自分を証明するのに役立ちます。 そして効率的に。
| Section | Objectives |
|---|---|
| Insurance and Risk Management | - Risk mitigation strategies in financial planning - Life and health insurance fundamentals |
| Retirement Planning | - Retirement savings vehicles and planning principles |
| Investment Planning | - Investment products and risk-return profiles - Asset allocation and portfolio basics |
| Financial Planning Foundations | - Ethics and professional standards in financial advising - Financial planning process and client relationship management |
| Taxation Concepts | - Personal income tax principles - Tax-efficient investment strategies |
Pass4Testはウェブサイトだけでなく、候補者のための専門的な学習ツールとしても使用できます。 最後になりますが、AFP-Exam-1トレーニング資料の高度な運用システムを使用して、CSIお客様に最速の配信速度を保証するだけでなく、お客様の個人情報を自動的に保護することもできます。 さらに、販売後の専門スタッフが、すべてのお客様に24時間年中無休でAFP-Exam-1試験Applied Financial Planning Certification Exam 1 (AFP)問題に関するオンラインアフターサービスを提供します。 そして、AFP-Exam-1学習ガイドの合格率は99%〜100%です。 AFP-Exam-1練習準備で認定を取得します。
質問 # 82
In 2019, Glenda, age 46, visited her financial planner to discuss her goal of retiring at the age of 65. Glenda had questions about whether she qualified for the maximum amount of CPP and OAS benefits as she had immigrated to Canada just 10 years earlier to take a job as a nuclear technician. What should her financial planner have told her?
正解:C
解説:
Glenda should be told to expect partial CPP and partial OAS benefits at age 65. OAS is based primarily on Canadian residence after age 18. A full OAS pension normally requires 40 years of qualifying Canadian residence, while a partial pension can be available with at least 10 years of residence in Canada after age 18.
Since Glenda immigrated only 10 years before the 2019 meeting at age 46, she would have about 29 years of residence by age 65, not the 40 years needed for maximum OAS. CPP is contribution-based; maximum CPP generally requires a long contribution history at or near maximum pensionable earnings. Even if her nuclear technician income is high, her Canadian contribution period is limited. Therefore, maximum CPP is not supportable on the facts. Study Guide focus: Canada Pension Plan, Old Age Security, residence requirements, contribution history, and retirement income projections. The projection should be updated as actual CPP contributions and future residency years become known.
質問 # 83
Demario, age 29, has started his own professional practice. He is single, has a mortgage, and his future earning power is his largest asset. Which insurance should receive priority?
正解:C
解説:
For a young self-employed professional, the dominant exposure is interruption of earned income. Disability insurance protects human capital by replacing income if illness or injury prevents the client from working.
Because Demario is self-employed, he may not have employer long-term disability benefits, paid sick leave, or group coverage. Option B is irrelevant because joint last-to-die coverage is built for two lives and estate liquidity after the second death. Option C is narrow and does not protect ongoing income. Option D may be useful in some estate plans, but estate equalization is not the priority for a single client whose key asset is earning ability. The planner should review own-occupation wording, elimination period, benefit period, inflation indexing, residual disability benefits, integration with emergency savings, and business overhead coverage if practice expenses must continue. The correct planning lens is income protection before estate accumulation. References/topics: disability insurance, human capital, self-employed clients, income replacement.
質問 # 84
Sapphire, age 35, a recent widow, is still in the grieving stage. She has just received a large insurance payout.
She has limited savings, a long-term time horizon, and a high tolerance for risk. What investment strategy should her financial planner recommend until Sapphire is better able to understand her new situation?
正解:A
解説:
Sapphire's technical risk tolerance is not the only planning factor. She is recently widowed, grieving, inexperienced in her new financial position, and has received a large insurance payout. A planner should avoid pushing her into a moderate or high-risk portfolio before she can make stable, informed decisions about goals, income needs, debts, taxes, and estate intentions. A high-interest savings account preserves capital, maintains liquidity, and buys time for the planning process. A ladder of GICs may eventually be suitable, but traditional and index-linked GICs still lock in terms or introduce product features she may not yet understand.
A high-risk portfolio would be especially inappropriate during the immediate transition period. The temporary recommendation is not a long-term asset-allocation decision; it is a prudent holding strategy until discovery and emotional readiness improve. Study Guide focus: major life events, client vulnerability, liquidity, temporary cash management, and suitability. This temporary parking approach is common after bereavement, divorce, inheritance, or business sale proceeds.
質問 # 85
Consider the following information for a client's portfolio: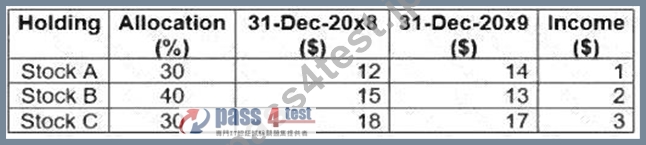
What is the annual rate of return for this portfolio?
正解:C
解説:
The portfolio return must combine price change and income for each holding, then weight each holding by its allocation. Stock A rises from $12 to $14 and pays $1 of income, producing a return of ($14 + $1 - $12) / $12
= 25%. Stock B falls from $15 to $13 but pays $2, producing a 0% total return. Stock C falls from $18 to $17 and pays $3, producing ($17 + $3 - $18) / $18 = 11.11%. Applying the allocation weights gives 30% × 25%, plus 40% × 0%, plus 30% × 11.11%, which is approximately 10.8%. The answer is not based only on market value movement and not on a simple average of the three returns. AFP investment calculations require total return and allocation weighting. Study Guide focus: portfolio return, income return, capital return, weighted averages, and performance measurement. This is why the answer is a weighted total-return figure, not a yield figure or a price-only performance measure.
質問 # 86
Two shareholders sign a buy-sell agreement requiring the surviving shareholder to purchase the deceased shareholder's shares at fair market value. What planning tool most directly funds the death-triggered purchase obligation?
正解:A
解説:
A death-funded buy-sell arrangement requires cash at the precise time a shareholder dies. Life insurance on the shareholders is commonly used because the death benefit provides liquidity when the obligation is triggered. Ownership may be corporate-owned or cross-owned, depending on tax, control, creditor, and agreement design. Option A is irrelevant because an RRSP is a personal retirement account and does not fund a contractual share purchase. Option C is weak because credit may be unavailable or expensive after a shareholder's death, and it shifts the funding risk to the survivor. Option D is too narrow because it pays only for accidental death, not death generally. A properly designed buy-sell plan coordinates the insurance amount, valuation formula, beneficiary or owner structure, agreement wording, tax treatment, and corporate cash flow.
The planner should involve legal and tax advisers because insurance funding must match the binding shareholder agreement. References/topics: buy-sell agreements, business insurance, shareholder planning, liquidity at death.
質問 # 87
......
CSI AFP-Exam-1試験を難しく感じる人に「やってもいないのに、できないと言わないこと」を言いたいです。我々Pass4TestへのCSI AFP-Exam-1試験問題集は専業化のチームが長時間で過去のデータから分析研究された成果で、あなたを試験に迅速的に合格できるのを助けます。依然躊躇うなら、弊社の無料のCSI AFP-Exam-1デモを参考しましょう。そうしたら、CSI AFP-Exam-1試験はそんなに簡単なことだと知られます。
AFP-Exam-1日本語的中対策: https://www.pass4test.jp/AFP-Exam-1.html