P.S. Free & New LLQP dumps are available on Google Drive shared by ActualPDF: https://drive.google.com/open?id=1RyV_8ILbxgMuzdlNth5r1iz3RXLizDoX
In comparison to others, Life License Qualification Program (LLQP) (LLQP) exam dumps are priced at a reasonable price. It is possible to prepare using LLQP exam using a pdf file anytime according to the hectic routines. If you are confused regarding its quality LLQP exam dumps, download the free trial to assist you make a final decision prior to purchasing. All exam dumps and patterns are made to follow the style of actual exam dumps. Therefore, it increases your chances of success in the Real LLQP Exam.
| Certification Vendor: | IFSE Institute |
|---|---|
| Exam Name: | Life License Qualification Program (LLQP) Modular Exams |
| Exam Number: | LLQP |
| Available Languages: | French, English |
| Real Exam Qty: | 20–30 per module |
| Exam Duration: | 75 per module |
| Certificate Validity Period: | 1 year from completion |
| Exam Price: | $12.50 USD per attempt |
| Exam Format: | Multiple-choice, Online proctored, Computer-based |
| Passing Score: | 60% per module |
| Recommended Training: | IFSE LLQP Official Course |
| Exam Registration: | IFSE Institute Exam Registration |
| Sample Questions: | IFSE Institute LLQP Sample Questions |
| Exam Way: | Online proctored via IFSE eTest platform; available 24/7 |
| Pre Condition: | No formal prerequisites; must complete approved LLQP course before exams |
| Official Syllabus URL: | https://www.ifse.ca/courselist/life-license-qualification-program-llqp/ |
IFSE Institute training pdf material is the valid tools which can help you prepare for the LLQP actual test. LLQP vce demo gives you the prep hints and important tips, helping you identify areas of weakness and improve both your conceptual knowledge and hands-on skills. With the help of LLQP study material, you will master the concepts and techniques that ensure you exam success. What’s more, you can receive LLQP updated study material within one year after purchase. Besides, you can rest assured to enjoy the secure shopping for IFSE Institute exam dumps on our site, and your personal information will be protected by our policy.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
NEW QUESTION # 163
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
Answer: A
Explanation:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence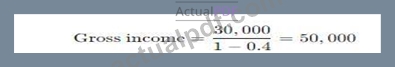
Calculate Required Capital for Income Replacement:
Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence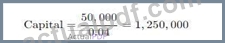
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
NEW QUESTION # 164
(Philippe, age 50, has been a widower for six months. He inherited the money in his wife's pension fund, which he transferred to a LIRA. He also received a $150,000 life insurance benefit. Philippe works for a private firm as an IT analyst and earns $80,000 a year. He would like to retire at age 60.
What income sources will be available to Philippe if he retires at age 60?)
Answer: A
Explanation:
Philippe will have access to hisLIRA, theGIChe invested in, and anyRRSPsor similar savings. CPP/QPP and OAS are not typically available until later (after 60 or 65), and GIS is for low-income individuals, which Philippe is not.
Exact Extract:
"A LIRA can be converted to a Life Income Fund (LIF) starting at age 55, allowing withdrawals. RRSPs can also be accessed by converting to RRIFs. GICs are fully redeemable based on terms. Eligibility for GIS and OAS typically starts at 65 years." (Reference:LifeInsur-E311-2022-10-9ED, Chapter 1 Retirement Income Options)
NEW QUESTION # 165
Coraline owns a $250,000 whole life insurance policy. She purchased the policy last year and does not have any funds accumulated in her cash surrender value (CSV). On December 30, Coraline assigns the policy to the cancer foundation, and she plans on continuing to pay the $200 monthly premium. Coraline calls her accountant James to ask him how much of her donation she will be able to use to obtain a charitable tax credit this year.
Answer: C
Explanation:
When Coraline assigns her whole life insurance policy to a charitable organization, she can claim the entire policy's fair market value as a charitable donation for tax credit purposes, which is generally the death benefit if there is no significant accumulated cash value. Since Coraline continues to pay the premiums, the policy remains in force. Thus, she can claim the$250,000face value of the policy as her charitable donation, which is eligible for a tax credit. Monthly premium amounts (Options B and C) or a lack of CSV (Option A) do not limit her eligibility for the credit based on the policy's value.Therefore,Option Dis correct.
NEW QUESTION # 166
Six years ago, Diu purchased an immediate life annuity with a 10-year guarantee period. The annuity paid her a monthly benefit of $1,800. She named her son Shan as the beneficiary of the policy and her niece Haru as a contingent beneficiary. Shan died four months ago in a motorcycle accident and between grieving and planning the funeral, Diu forgot to update her beneficiary designation. Last week, Diu died of a heart attack.
Who would receive the annuity benefits?
Answer: A
Explanation:
Since Diu had designated her son Shan as the primary beneficiary and her niece Haru as the contingent beneficiary, the death benefit from the annuity will pass to Haru, the contingent beneficiary, after Shan's death. In annuity contracts, if the primary beneficiary predeceases the annuitant and no changes are made to the designation, the benefits will typically go to the contingent beneficiary. According to LLQP principles, a contingent beneficiary is entitled to receive the remaining guaranteed payments when the primary beneficiary is no longer able to do so.
Option A is incorrect as Shan's widow is not mentioned as a beneficiary. Option B is incorrect as Shan's estate would not receive the benefits if a contingent beneficiary exists. Option D is incorrect as Diu's estate would only receive the benefits if no beneficiaries were named.
NEW QUESTION # 167
Nikolai owns a guaranteed renewable individual disability policy that he purchased last year. The policy pays a monthly benefit of $3,000 and includes a 4-month waiting period and a 5-year benefit period. Today, he is diagnosed with prostate cancer and learns he must undergo 6 months of radiation.
When should he contact the insurance company to inform them of his diagnosis?
Answer: C
Explanation:
Nikolai should inform his insureras soon as he receives his diagnosis. Prompt notification is crucial as it ensures that his claim process can begin, including the assessment of eligibility,documentation, and verification. Additionally, reporting the diagnosis early helps the insurer monitor his waiting period of four months and plan for benefit payments starting at the end of this period. LLQP materials recommend early communication with the insurer to avoid delays in claim processing.
NEW QUESTION # 168
......
LLQP Valid Test Experience: https://www.actualpdf.com/LLQP_exam-dumps.html
P.S. Free 2026 IFSE Institute LLQP dumps are available on Google Drive shared by ActualPDF: https://drive.google.com/open?id=1RyV_8ILbxgMuzdlNth5r1iz3RXLizDoX