Laden Sie die neuesten ITZert CIMAPRA19-F03-1 PDF-Versionen von Prüfungsfragen kostenlos von Google Drive herunter: https://drive.google.com/open?id=1ZuoXUF72aHj6GhN-UrtRND7f5X3Jm-05
Wir ITZert sind die Website, die Kadidaten IT-zertifizierung Dumps und gut helfen können. Wir ITZert schreiben alle CIMA CIMAPRA19-F03-1 Prüfungsfragen bei der Verwendung der früheren Erlebnisse, deshalb haben wir die besten CIMA CIMAPRA19-F03-1 Dumps. Die Prüfungsunterlagen beinhalten alle möglichen Prüfungsfragen in der aktuellen Prüfung. Es kann Ihnen garantieren, einmal den Erfolg zu erreichen.
| Section | Weight | Objectives |
|---|---|---|
| Financial Risks | 20% | - Currency Risk Management
|
| Financial Policy Decisions | 15% | - Development of Financial Strategy
|
| Sources of Long-Term Funds | 25% | - Capital Structure and Dividend Policy
|
| Business Valuation | 40% | - Mergers and Acquisitions
|
Jeder hat seinen eigenen Lebensplan. Wenn Sie andere Wahle treffen, bekommen Sie sicher etwas Anderes. So ist die Wahl serh wichtig. Die Schulungsunterlagen zur CIMA CIMAPRA19-F03-1 Zertifizierungsprüfung von ITZert ist eine beste Methode, die den IT-Fachleuten helfen, ihr Ziel zu erreichen. Sie enthalten Prüfungsfragen und Antworten zur CIMA CIMAPRA19-F03-1 Zertifizierung. Und sie sind den echten Prüfungen ähnlich. Es ist wirklich die besten Schulungsunterlagen.
148. Frage
Company A is based in country A with the AS as its functional currency. It expects to receive BS20 million from Company B in settlement of an export invoice.
The current exchange rate is A$1 =B$2 and the daily standard deviation of this exchange rate = 0 5% What is the one-day 95% VaR in AS?
Antwort: A
Begründung:
Exposure: Company A will receive B$20 million.
Spot rate: A$1 = B$2 # 1 B$ = A$0.5
Current A$ value of the receipt:
20,000,000×0.5=A$10,000,00020{,}000{,}000 \times 0.5 = A\$10{,}000{,}00020,000,000×0.
5=A$10,000,000
Daily standard deviation of the exchange rate = 0.5% = 0.005
1-day 95% VaR uses Z # 1.645
VaR:
VaR=Z×#×exposure=1.645×0.005×10,000,000\text{VaR} = Z \times \sigma \times \text{exposure} = 1.645
\times 0.005 \times 10{,}000{,}000VaR=Z×#×exposure=1.645×0.005×10,000,000 0.005×10,000,000=50,
0000.005 \times 10{,}000{,}000 = 50{,}0000.005×10,000,000=50,000 1.645×50,000=82,2501.645 \times 50
{,}000 = 82{,}2501.645×50,000=82,250
So the 1-day 95% VaR is A$82,250 # Option C.
149. Frage
A company plans to acquire new machinery.
It has two financing options; buy outright using a bank loan, or a finance lease.
Which of the following is an advantage of a finance lease compared with a bank loan?
Antwort: A
Begründung:
In CIMA F3, finance leases are analysed as a form of debt financing and are compared directly with bank loans when evaluating long-term funding options. The syllabus (under Financing Decisions and Leasing vs Buying) explains that a finance lease is economically similar to borrowing to purchase an asset, because the lessee assumes substantially all the risks and rewards of ownership.
Option B is correct because one key advantage of a finance lease over a bank loan is that the lessor retains legal ownership of the asset, which provides strong security for the lender. As a result, the lessor's risk is lower than that of a bank providing an unsecured or partially secured loan. CIMA F3 study guidance highlights that this reduced risk can allow the lessor to offer more favourable interest rates or financing terms than a conventional bank loan.
The other options are incorrect under current accounting and financial strategy principles:
A is incorrect because finance leases are not off-balance sheet. Under IFRS 16 (examined in F3), finance leases must be recognised on the statement of financial position, increasing both assets and liabilities and therefore affecting gearing.
C is incorrect because tax depreciation (capital allowances) normally remain with the legal owner, the lessor.
These benefits are not "passed on" directly, although they may be reflected indirectly in lease pricing.
D is incorrect because maintenance is a feature of operating leases, not finance leases. In a finance lease, the lessee is responsible for maintenance and insurance.
150. Frage
D has US$10 million to invest over 12 months in either USS or GBP Its options are to invest in USS at the present USS interest rate of 10 18%. or to convert the USS to GBP at the spot rate GBP1 =US$1 61 and invest in GBP at an interest rate of 6.4%.
According to the interest rate parity theory, what will the one year forward rate be?
Give your answer to three decimal places.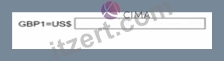
Antwort:
Begründung:
1.667
151. Frage
A company's annual dividend has grown steadily at an annual rate of 3% for many years. It has a cost of equity of 11%. The share price is presently $64.38.
The company is about to announce its latest dividend, which is expected to be $5.00 per share.
The Board of Directors is considering an attractive investment opportunity that would have to be funded by reducing the dividend to $4.50 per share. The board expects the project to enable future dividends to grow by 5% every year and the cost of equity to remain unchanged.
Calculate the change in share price, assuming that the directors announce their intention to proceed with this investment opportunity.
Give your answer to 2 decimal places.
$ ?
Antwort:
Begründung:
14.37
152. Frage
A company intends to sell one of its business units. Company W, by a management buyout (MBO). A selling price of S200 million has been agreed.
The managers are discussing with a bank and a venture capital company (VCC) the following financing proposal.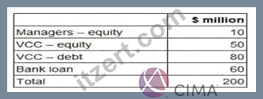
The VCC requires a minimum return on its equity investment In the MBO of 35% a year on a compound basis over 5 years. What is the minimum total equity value of Company W in 5 years time in order to meet the VCC's required return? Give your answer to one decimal place.
BONUS!!! Laden Sie die vollständige Version der ITZert CIMAPRA19-F03-1 Prüfungsfragen kostenlos herunter: https://drive.google.com/open?id=1ZuoXUF72aHj6GhN-UrtRND7f5X3Jm-05