In order to cater to meet different needs of candidates, three versions of AFP-Exam-1 learning materials are available. AFP-Exam-1 PDF version is printable, and if you prefer the hard one, you can choose this version for your practice. AFP-Exam-1 Soft test engine can install in more than 200 personal computers, and it can also stimulate the real examenvironment, and you can know what the real exam is like. AFP-Exam-1 Online Test engine is convenient and easy to learn, you can learn anytime and anyplace. This version can record your process of training, and you can have a general review before next training.
| Section | Weight | Objectives |
|---|---|---|
| Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
| Technical Competencies | 84% | - Risk Management and Insurance - Asset and Liability Management - Investment Planning - Tax Planning - Retirement Planning - Estate Planning |
>> Reliable AFP-Exam-1 Exam Cost <<
There are some prominent features that are making the CSI AFP-Exam-1 exam dumps the first choice of CSI AFP-Exam-1 certification exam candidates. The prominent features are real and verified Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam questions, availability of Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam dumps in three different formats, affordable price, 1 year free updated CSI AFP-Exam-1 exam questions download facility, and 100 percent CSI AFP-Exam-1 exam passing money back guarantee.
NEW QUESTION # 23
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.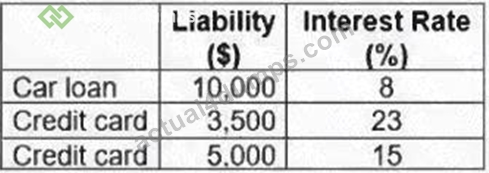
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
Answer: C
Explanation:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
NEW QUESTION # 24
A client realizes a $16,000 capital loss on one non-registered investment and a $28,000 capital gain on another non-registered investment in the same year. How should the loss be treated?
Answer: A
Explanation:
Capital losses are used within the capital-gains system. In the same taxation year, the realized capital loss can reduce realized capital gains, producing a lower net capital gain before applying the taxable inclusion rules.
Option A is wrong because capital losses can be valuable when gains exist. Option B is generally incorrect because net capital losses are not normally applied against employment income. Option D is also incorrect; a capital loss is not a refundable credit. A planner should also consider whether a sale creates a superficial loss if the same or identical property is repurchased within the restricted period by the client or an affiliated person. Current-year gains are usually offset first, and unused net capital losses may have carryback or carryforward treatment under tax rules. The planning objective is to coordinate realization timing so tax is minimized without allowing tax considerations to override investment suitability. References/topics: capital gains and losses, tax-loss selling, non-registered accounts, superficial loss rules.
===============
NEW QUESTION # 25
A client completed a financial plan two years ago. Since then, she has divorced, changed jobs, and purchased a new home. What is the planner's most appropriate recommendation?
Answer: C
Explanation:
Major life events trigger a planning review. Divorce, employment change, and a new home can alter income, expenses, debt service ratios, beneficiary designations, insurance needs, tax filing status, retirement savings capacity, emergency reserves, and estate documents. A two-year-old plan may no longer reflect the client's legal or financial position. Option A is too rigid; scheduled reviews do not replace event-driven reviews.
Option C is too narrow because the changes affect far more than investments. Option D is product-driven and inconsistent with a planning relationship. A disciplined review should update KYC, net worth, cash flow, support obligations if any, mortgage terms, risk capacity, insurance coverage, wills, powers of attorney, and retirement assumptions. The planner should document the triggering events and the revised recommendations.
In official planning language, monitoring is not passive; it requires reassessment when facts materially change. References/topics: monitoring and review, life events, comprehensive planning, client relationship management. This review also confirms whether previous assumptions remain valid.
NEW QUESTION # 26
Francois and Brigitte are meeting with their financial planner, Robin. They would like to ensure that if one of them were to die suddenly that their mortgage would be paid in full. Their current mortgage has an outstanding balance of $400,000 with 10 years remaining. The couple are in good health and have a well- balanced financial plan that focuses on debt reduction and savings. Which type of insurance policy should Robin recommend to assist the couple in meeting their objective?
Answer: C
Explanation:
A joint 10-year term first-to-die policy matches the couple's exact risk. Francois and Brigitte want the mortgage paid if one spouse dies suddenly, and the mortgage has 10 years remaining. First-to-die coverage pays on the first death, which is when the survivor would need funds to discharge the mortgage. A 10-year term aligns the coverage period with the debt. Last-to-die coverage is inappropriate because it pays only after both insured persons have died, too late to protect the survivor's mortgage obligation. Whole life coverage is permanent and more expensive than necessary for a temporary mortgage balance. Since the couple is healthy and already has a balanced plan, the planner should recommend efficient, purpose-built term insurance rather than over-insuring with a permanent policy. Study Guide focus: mortgage insurance needs, first-to-die coverage, term insurance, debt protection, and risk matching. The death benefit should be sized to the outstanding debt and reviewed as the mortgage is repaid.
NEW QUESTION # 27
Interest rates are expected to rise sharply. Which fixed-income security would normally have the highest price sensitivity to that change, all else equal?
Answer: C
Explanation:
Price sensitivity to interest-rate changes is measured primarily through duration. A long-term zero-coupon bond normally has very high duration because the investor receives no interim coupons; the entire cash flow is concentrated at maturity. When rates rise, the present value of that distant cash flow falls sharply. Option A has low sensitivity because it matures quickly. Option C adjusts its coupon with reference rates, which usually reduces price volatility relative to fixed-coupon long bonds. Option D is a deposit product rather than a market-traded bond and generally does not experience the same market-price movement. This question tests the inverse relationship between bond prices and yields plus the additional effect of term and coupon structure. A planner should not simply ask whether fixed income is "safe"; fixed-income portfolios have interest-rate risk, reinvestment risk, credit risk, and liquidity risk. The highest-risk answer under rising rates is the longest zero-coupon exposure. References/topics: duration, bond pricing, interest-rate risk, fixed-income securities.
NEW QUESTION # 28
......
CSI AFP-Exam-1 exam is a Technical Specialist exam. CSI AFP-Exam-1 exam can help and promote IT staff have a good career. With a good career, and of course you can create a steady stream of corporate and national interests, so as to promote the development of the national economy. If all of the IT staff can do like this the state will become stronger. Actual4Dumps CSI AFP-Exam-1 Exam Training materials can help IT personnel to achieve this purpose. We guarantee you 100% to pass the exam. Make the tough decision to choose our Actual4Dumps CSI AFP-Exam-1 exam training materials please.
Latest AFP-Exam-1 Study Notes: https://www.actual4dumps.com/AFP-Exam-1-study-material.html