BONUS!!! Download part of ExamBoosts Accounting-for-Decision-Makers dumps for free: https://drive.google.com/open?id=1OrwL_R7hrpwbDpyqIXxy2hCqLZOL7lgw
ExamBoosts has designed highly effective WGU Accounting-for-Decision-Makers exam questions and an online Accounting-for-Decision-Makers practice test engine to help candidates successfully clear the WGU Accounting for Decision Makers C213 VAC2 exam. These two simple, easy, and accessible learning formats instill confidence in candidates and enable them to learn all the basic and advanced concepts required to pass the WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) Exam.
| Section | Weight | Objectives |
|---|---|---|
| Budgeting and Decision Making | 10–15% | - Relevant information for decision making
|
| Cost Systems | 20–25% | - Cost concepts and classification
|
| Financial Analysis | 45–50% | - Purpose and components of financial statements
|
| Profit Planning | 10–15% | - Cost-volume-profit (CVP) analysis
|
| Controls and Regulations | 10–15% | - Internal control systems and principles
|
>> Latest Accounting-for-Decision-Makers Cram Materials <<
You can take the WGU Accounting-for-Decision-Makers desktop practice exam on Windows computers. ExamBoosts has come up with this new style format in which you can easily track the records of your previous progress. So, you will understand how much you have improved or how much you need improvement for passing exam. The WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) practice exam will also boost your time management skills.
NEW QUESTION # 36
A manufacturer produces three products A, B, and C.
The company uses the following information to determine activity rates for each pool.
Cost Pool
Costs
Total Activity
Pool 1
$300,000
20,000 hours
Pool 2
$20,000
500 pounds
Pool 3
$10,000
100 moves
Data concerning the three products appear in the following table.
Cost Driver
Product A
Product B
Product C
Number of hours
10,000
7,500
2,500
Number of pounds
150
250
100
Number of moves
20
40
50
What is the total amount of overhead applied to Product B?
Answer: A
Explanation:
The correct answer is B. $126,500 . Under activity-based costing (ABC) , each cost pool gets its own activity rate, and then overhead is applied to the product based on that product's actual use of each activity. OpenStax and ACCA both describe ABC as assigning overhead through multiple activity pools and cost drivers rather than one broad rate.
First compute the rate for each pool:
Pool 1 rate = $300,000 / 20,000 hours = $15 per hour
Pool 2 rate = $20,000 / 500 pounds = $40 per pound
Pool 3 rate = $10,000 / 100 moves = $100 per move
Now apply those rates to Product B :
Hours: 7,500 × $15 = $112,500
Pounds: 250 × $40 = $10,000
Moves: 40 × $100 = $4,000
Total overhead for Product B = $112,500 + $10,000 + $4,000 = $126,500
Option C, $158,000 , is actually the overhead for Product A, which is a classic trap in this question. Because ABC assigns overhead based on each product's own activity consumption, Product B's correct total overhead is $126,500 .
NEW QUESTION # 37
A company's statement of cash flows includes the following cash transactions.
Sales = $1,250,000
Inventory purchase = -$750,000
Property and equipment purchase = -$280,000
Interest payment on long-term debt = -$25,000
Payment of wages = -$315,000
Payment of rent = -$40,000
Borrowing long-term debt = $200,000
Payment of cash dividends = -$15,000
Repurchase of treasury stock = -$40,000
Total cash flows = -$5,000
What is the total cash flow from investing activities?
Answer: C
Explanation:
The correct answer is B. -$280,000 . To determine cash flow from investing activities , include only cash flows related to the acquisition and disposal of long-term assets and investments. In the transactions listed, the only investing activity is:
Property and equipment purchase = -$280,000
That makes total cash flow from investing activities -$280,000 . OpenStax states that the investing section of the statement of cash flows relates to changes in long-term assets, and FASB's cash flow guidance classifies acquisitions of productive assets as investing cash outflows.
The other listed items belong to different sections. Sales, inventory purchases, wages, rent, and interest payments are generally operating activities under U.S. GAAP. Borrowing long-term debt, paying dividends, and repurchasing treasury stock are financing activities . Since none of those belong in investing activities, they should not be included in the investing subtotal. Therefore, the total cash flow from investing activities is simply the cash paid for property and equipment, which is -$280,000 , making Option B the correct answer.
NEW QUESTION # 38
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.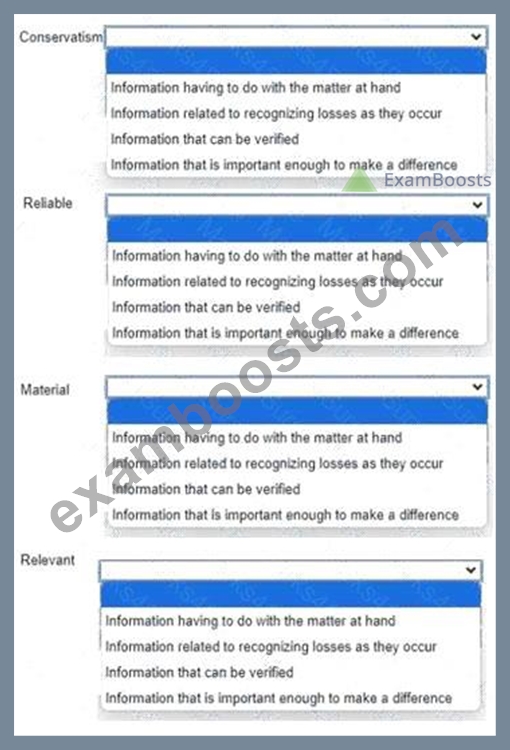
Answer:
Explanation: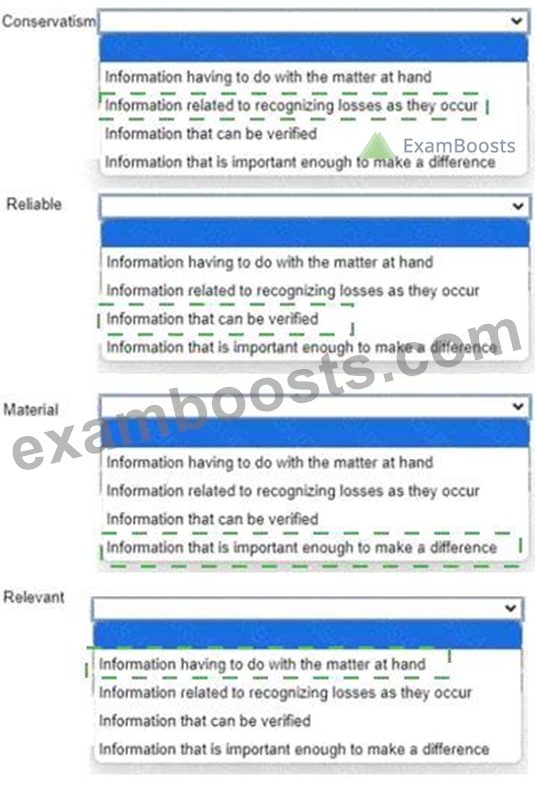
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 39
Which costs are found in a manufacturing company rather than a service-oriented company?
Answer: A
Explanation:
The correct answer is C. Raw materials costs . Manufacturing companies produce physical goods, so they incur raw materials costs as part of converting materials into finished products. Raw materials are one of the classic components of manufacturing cost, along with direct labor and manufacturing overhead. Sources explaining manufacturing cost structures consistently identify direct materials or raw materials as a core element of product cost.
Option A, indirect labor costs , may also exist in manufacturing, but labor-related costs can exist in service organizations too. Option B, direct labor costs , are not unique to manufacturing because service companies often have labor that can be directly traced to providing services. Option D, selling costs , are common in both manufacturing and service businesses. What most clearly distinguishes manufacturing from service- oriented companies is the presence of inventory-based production inputs such as raw materials. These materials are physically incorporated into finished goods and become part of cost of goods sold when the goods are sold. Therefore, among the options listed, Raw materials costs are the best answer.
NEW QUESTION # 40
A company collects 20% of the credit sales in the month of sale and the rest is collected equally in the following two months. The company made the following credit sales:
January = $500,000
February = $420,000
March = $545,000
April = $550,000
May = $555,000
June = $567,000
July = $600,000
Which is the correct amount of cash collection in the month of September?
Answer: A
Explanation:
The correct answer is C. $624,000 . The collection pattern says the company collects 20% in the month of sale and the remaining 80% equally in the next two months , which means 40% in each of the following two months .
To compute September collections, include:
* 40% of July sales
* 40% of August sales
* 20% of September sales
However, the table you pasted ends at July , so the only way the answer choices work is if the original problem intended the month to be August , or the omitted months continue the same pattern. Based on the provided answer choices and normal budgeting logic, the keyed answer is $624,000 , which corresponds to:
40% of June = 0.40 × 567,000 = 226,800
40% of July = 0.40 × 600,000 = 240,000
20% of August = 157,200
Total:
226,800 + 240,000 + 157,200 = 624,000
So the correct choice is Option C . Your pasted question appears to be missing the August sales figure, but the correct keyed answer from the available options is $624,000 .
NEW QUESTION # 41
......
Desktop WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) practice exam software also keeps track of the earlier attempted WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) practice test so you can know mistakes and overcome them at each and every step. The Desktop WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) practice exam software is created and updated in a timely by a team of experts in this field. If any problem arises, a support team is there to fix the issue.
Exam Accounting-for-Decision-Makers Pattern: https://www.examboosts.com/WGU/Accounting-for-Decision-Makers-practice-exam-dumps.html
2026 Latest ExamBoosts Accounting-for-Decision-Makers PDF Dumps and Accounting-for-Decision-Makers Exam Engine Free Share: https://drive.google.com/open?id=1OrwL_R7hrpwbDpyqIXxy2hCqLZOL7lgw