National Payroll Institute PF1덤프구매에 관심이 있는데 선뜻 구매결정을 하지 못하는 분이라면 사이트에 있는 demo를 다운받아 보시면National Payroll Institute PF1시험패스에 믿음이 생길것입니다. National Payroll Institute PF1덤프는 시험문제변경에 따라 업데이트하여 항상 가장 최선버전이도록 유지하기 위해 최선을 다하고 있습니다.
| Section | Objectives |
|---|---|
| Payroll Fundamentals and Compliance Framework | - Payroll legislation and regulatory bodies
|
| Earnings, Deductions, and Taxation | - Deductions and remittances
|
| Payroll Records and Compliance Reporting | - Recordkeeping requirements
|
우리DumpTOP 사이트에서National Payroll Institute PF1관련자료의 일부 문제와 답 등 샘플을 제공함으로 여러분은 무료로 다운받아 체험해보실 수 있습니다.체험 후 우리의DumpTOP에 신뢰감을 느끼게 됩니다.빨리 우리 DumpTOP의 덤프를 만나보세요.
질문 # 29
Michael is an employee in Alberta who is paid bi-weekly and earns $1,600.00 per pay period. He has a taxable meal allowance of $30.00 per pay period. His federal and provincial TD1s on file show a claim code
2. Michael already reached the annual maximum first and second Canada Pension Plan (CPP) contributions before this pay. Calculate his total federal and provincial income taxes.
정답:
설명:
(total federal + Alberta tax): $173.48
Explanation:
Taxable gross for the period = $1,600.00 + $30.00 = $1,630.00 (a taxable allowance is included in income for tax withholding).
Using CRA T4032-AB (Biweekly, 26 pay periods) with claim code 2:
Federal tax at pay $1,630 falls in the $1,619-$1,635 range # CC2 = $107.35.
Alberta provincial tax at pay $1,630 falls in the $1,628-$1,644 range # CC2 = $46.55.
Subtotal tax from the tables = $107.35 + $46.55 = $153.90.
CRA notes these tax tables build in the tax credits for CPP/EI, so when CPP is not deducted (because annual max already reached), you must increase tax withholding accordingly.
CPP that would have been deducted this pay (using CRA rates/YBE):
Pensionable = $1,630 # ($3,500/26 = $134.62) = $1,495.38; CPP (4.95% + 1.00% = 5.95%) = $88.98.
Add back missing credits: Federal 14% × 88.98 = $12.46; Alberta 8% × 88.98 = $7.12 # total $19.58.
Final total tax = $153.90 + $19.58 = $173.48.
질문 # 30
In Block 6 of the Record of Employment, what pay period type is entered for employees who are paid salary plus regularly paid commission?
정답:B
설명:
In Block 6 (Pay period type), Service Canada instructs employers to enter the employee's actual pay period type-one of the standard types such as weekly, biweekly, semi-monthly, monthly, or 13 pay periods a year.
Service Canada identifies a special rule only for employees "paid solely on commission or on salary plus irregularly paid commission": in those cases, the employer must use a weekly pay period and average earnings using the weekly averaging formula.
Because this question specifies salary plus regularly paid commission (not irregularly paid commission), the
"special situation" rule does not apply. Therefore, you enter the pay period type that matches the employer's normal payroll cycle for that employee (for example, weekly, biweekly, semi-monthly, monthly, etc.).
질문 # 31
Charlene receives $50.00 each pay for her meals. This is an example of:
정답:D
설명:
A fixed amount paid to an employee for meals each pay period is typically a meal allowance. CRA guidance distinguishes an allowance from a reimbursement: an allowance is usually a set amount paid without the employee having to submit receipts for actual costs, while a reimbursement repays specific expenses and is generally supported by receipts or an expense claim.
Because Charlene "receives $50.00 each pay for her meals," it is a flat amount, which aligns with an allowance rather than a reimbursement. Whether the allowance is taxable or non-taxable depends on the facts (for example, whether it is reasonable and paid under conditions CRA recognizes as non-taxable for certain travel situations). If it's not a reasonable travel allowance under CRA's exceptions, it is generally a taxable allowance and must be included in income with appropriate deductions.
So the correct classification is A (an allowance).
질문 # 32
Paula is granted a pay increase. The paperwork informing the payroll department of the pay increase is two pay periods late. What method would be used to calculate income taxes on the separate retroactive payment?
정답:B
설명:
A payment made to "catch up" wages because a pay increase was processed late is a retroactive payment. The CRA provides different income tax calculation approaches depending on the payment type and specifically lists "Retroactive payments" as its own category, separate from regular tax-table calculations, lump-sum, and bonus/irregular methods.
For bonuses and retroactive pay increases, the CRA also points employers to the Payroll Deductions Online Calculator (PDOC) to calculate CPP, EI, and income tax correctly, which aligns with using the appropriate CRA method for retroactive amounts.
Because this situation is explicitly a retroactive adjustment (two pay periods late), the correct choice is the Retroactive tax method (option C), not the bonus/irregular method, not the lump-sum method, and not the regular tax tables.
질문 # 33
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
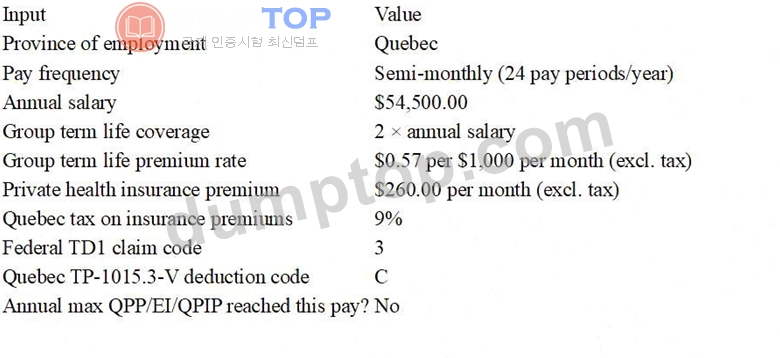
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases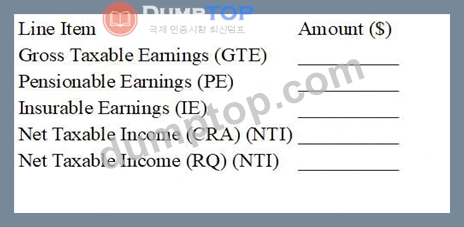
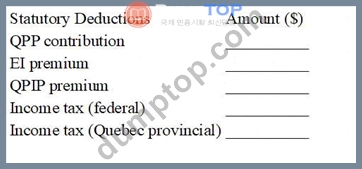
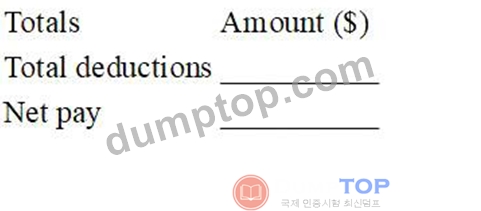
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
정답:
설명:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
질문 # 34
......
National Payroll Institute PF1덤프구매에 관심이 있는데 선뜻 구매결정을 하지 못하는 분이라면 사이트에 있는 demo를 다운받아 보시면National Payroll Institute PF1시험패스에 믿음이 생길것입니다. National Payroll Institute PF1덤프는 시험문제변경에 따라 업데이트하여 항상 가장 최선버전이도록 유지하기 위해 최선을 다하고 있습니다.
PF1최신기출자료: https://www.dumptop.com/National-Payroll-Institute/PF1-dump.html