市場の一般的な質問バンクとは異なり、TopexamのPF1の実際の試験は、多くの業界専門家によって認められているさまざまな専門知識のための科学的かつ効率的な学習システムです。 National Payroll InstituteのPF1試験トレントの内容だけでなく、最新かつ正確な情報をお客様に提供するため、レイアウトについてもデジタルデバイスの開発に応じて改革を実施しました。 最新のPF1試験問題とともにPayroll Fundamentals 1Exam試験に合格します。
| Section | Objectives |
|---|---|
| Payroll Fundamentals and Compliance Framework | - Payroll system overview in Canada
|
| Payroll Records and Compliance Reporting | - Recordkeeping requirements
|
| Earnings, Deductions, and Taxation | - Deductions and remittances
|
あなたのキャリアでいくつかの輝かしい業績を行うことを望まないのですか。きっとそれを望んでいるでしょう。では、常に自分自身をアップグレードする必要があります。では、IT業種で仕事しているあなたはどうやって自分のレベルを高めるべきですか。実は、PF1認定試験を受験して認証資格を取るのは一つの良い方法です。National Payroll Instituteの認定試験のPF1資格は非常に大切なものですから、National Payroll Instituteの試験を受ける人もますます多くなっています。
質問 # 37
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
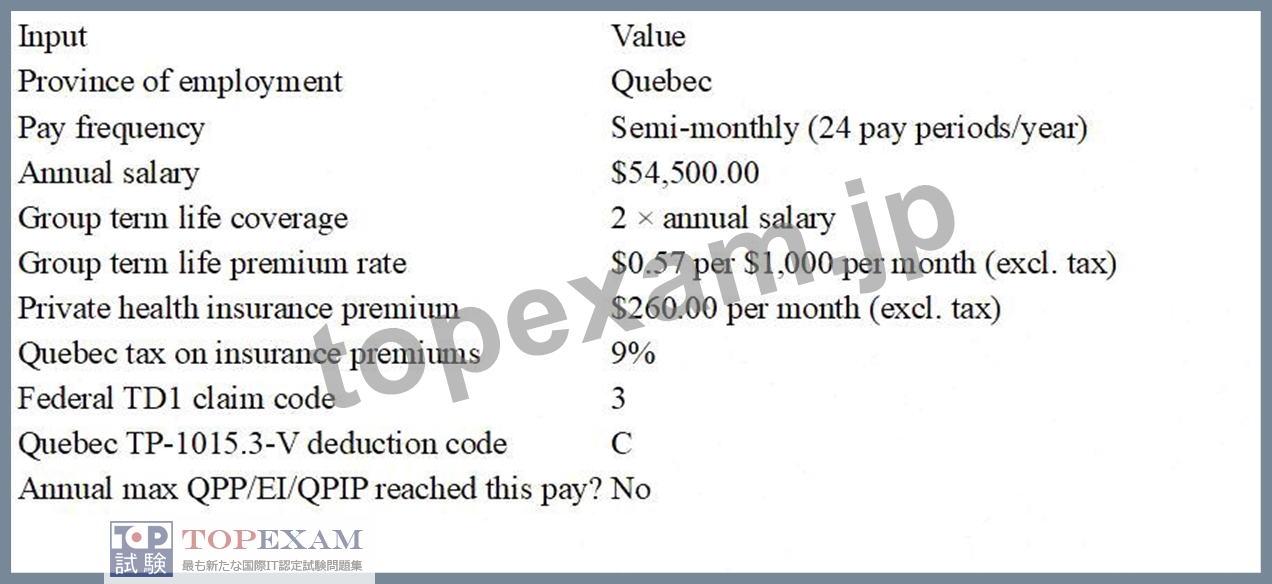
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases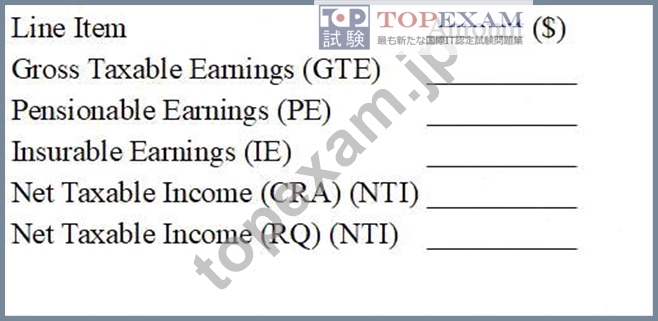
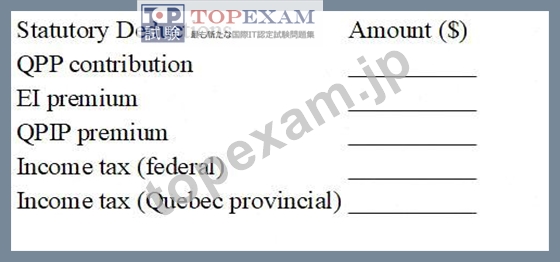
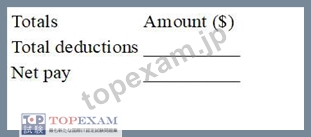
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
正解:
解説:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
質問 # 38
The capital cost of an employer-owned vehicle includes:
正解:A
解説:
For CRA automobile benefit purposes (standby charge on an employer-owned automobile), the "cost" used is the capital cost, which includes more than just the sticker price. CRA guidance states the cost includes the trade-in amount (if applicable), additions, and GST/HST and PST as part of the cost base used in the standby charge calculation.
Option D is the best match because it includes vehicle options/accessories, sales taxes, and additions that add to depreciation value. Importantly, CRA also notes that certain specialized equipment added to meet the requirements of a disabled person or employment (examples include heavy-duty suspension and power winches) is not considered part of the automobile's cost for standby charge purposes. This directly rules out options A and C, since they treat specialized equipment as part of capital cost. Option B is incorrect because CRA includes sales taxes (GST/HST and PST) in the cost base.
質問 # 39
The source deductions form completed by all new employees in Quebec is called:
正解:A
解説:
In Quebec, employees must complete a Quebec-specific source deductions form so the employer can calculate Quebec income tax to withhold. Revenu Quebec identifies Form TP-1015.3-V (Source Deductions Return) as the form employees complete and provide to their employer/payer for this purpose. It is part of the onboarding
/payroll setup process in Quebec and is used to determine personal tax credits and any additional withholding instructions for Quebec provincial income tax.
The other options are not the standard Quebec source deductions return for new employees: T1213 is a CRA form used to request a reduction in tax deductions at source (federal), TD1-AB is a provincial TD1 for Alberta (not Quebec), and T2222 is not the Quebec source deductions return. From a payroll communication standpoint, the employer should request both the applicable federal TD1 and the Quebec TP-1015.3-V, then retain them on file to support accurate withholding calculations.
質問 # 40
Which statutory deductions is salary continuance subject to?
正解:B
解説:
Salary continuance means the employee continues to receive regular pay (and often benefits) for a period after their job ends. In this arrangement, the payments are treated like regular employment income for payroll purposes, so the usual payroll deductions apply. A Government of Canada guidance page explains that when severance is paid as salary continuance, the employee pays income tax like regular employment income and that the usual deductions apply, including CPP (or QPP), EI premiums, and RPP contributions (where applicable).
This aligns with standard payroll obligations in CRA's payroll remittance framework: employers deduct and remit CPP contributions, EI premiums, and income tax on employment income unless a specific exemption applies.
Therefore, the correct option is B (All deductions)-and in Quebec, that "all deductions" concept includes Quebec-specific programs (for example QPP/QPIP where applicable) based on the employee's province of employment and insurability rules.
質問 # 41
Phillip is being paid a severance payment with his final pay. Which block should this payment be reported on the Record of Employment?
正解:C
解説:
On the ROE, separation payments are reported in Block 17. Service Canada explains that Block 17C - Other monies is used to record "any other payments or benefits...paid...because of the separation," whether or not they are insurable.
The ROE Guide specifically lists "Severance pay" as a type of separation money to enter in Block 17C ("Enter 'Severance pay' and the amount").
Crucially, Block 15B and Block 15C are for insurable earnings totals/by pay period. The ROE Guide notes that some amounts reported in Block 17 (like vacation pay) are insurable and must be added into Blocks 15B
/15C; however, retirement leave credits/retiring allowances (a form of severance-type payment) are not insurable and are not added to Blocks 15B/15C even though they are recorded in Block 17C.
So, severance is reported in Block 17C only.
質問 # 42
......
National Payroll Institute完璧な素材の選択については、品質、価格、アフターサービスなどに反映される場合があります。 PF1試験シミュレーションは、Topexam試験のシラバスに厳密に基づいた試験に関する知識の蓄積です。 情報や試験へのアクセスをユーザーに提供し、教室のように参加したときに模擬的なテスト環境を提供します。 また、PF1学習ガイドの内容は、日常生活での実践に適した専門家によって選択されます。 PF1準備資料Payroll Fundamentals 1Examを渡すのに十分な時間がない忙しい労働者にとって特に有利です。
PF1学習資料: https://www.topexam.jp/PF1_shiken.html