権威のあるIIA-CIA-Part3資格練習 &合格スムーズIIA-CIA-Part3過去問 |信頼的なIIA-CIA-Part3日本語独学書籍

BONUS!!! CertShiken IIA-CIA-Part3ダンプの一部を無料でダウンロード:https://drive.google.com/open?id=14t8lh8Ph2NAg5NKFuGZPNKlU1y6QGS6p
IIA-CIA-Part3証明書を所有して、自分が有能であることを証明し、特定の分野で優れた実用的な能力を高めることができます。したがって、CertShikenあなたは有能な人々とみなされ、尊敬されます。テストIIA-CIA-Part3認定に合格すると、目標を実現するのに役立ちます。また、IIA-CIA-Part3ガイドトレントを購入すると、IIA-CIA-Part3試験に簡単に合格できます。 IIA-CIA-Part3試験問題は最も専門的な専門家によって書かれているため、IIA-CIA-Part3学習教材の品質は素晴らしいです。そして、試験に合格するために、Internal Audit Function学習ガイドを常に最新の状態に保ちます。
IIA-CIA-PART3試験は、2.5時間以内に完了する必要がある100の複数選択質問で構成されています。この試験では、ビジネス環境と概念、財務会計と報告、管理会計、情報技術、ビジネス戦略と管理など、幅広いトピックをカバーしています。試験に合格した候補者は、IIA-CIA-PART3認定を受け取ります。これは、ビジネスの概念を内部監査に適用する知識と能力を実証します。この認定は、世界中の組織によって認識されており、キャリアを前進させようとする監査人にとって貴重な資産です。
IIA-CIA-PART3認定試験は、内部監査の分野における卓越性の兆候として世界中の雇用主によって認識されています。この認定は、内部監査人がキャリアを前進させ、収益の可能性を高めるのに役立ちます。また、雇用主に、内部監査人が職務を効果的に実行するために必要な知識とスキルを確保する方法を提供します。
>> IIA-CIA-Part3資格練習 <<
IIA IIA-CIA-Part3過去問、IIA-CIA-Part3日本語独学書籍
IIA-CIA-Part3実践ガイドまたはシステムの内容が更新された場合、更新された情報を電子メールアドレスに送信します。もちろん、製品の更新状況については、当社の電子メールをご覧ください。 IIA-CIA-Part3模擬試験を使用してIIA-CIA-Part3試験に合格するように協力できることを願っています。コンテンツの更新に加えて、IIA-CIA-Part3トレーニング資料のシステムも更新されます。ご意見がありましたら、私たちの共通の目標は、ユーザーが満足する製品を作成することであると言えます。学習を開始した後、メールをチェックするための固定時間を設定できることを願っています。
IIA-CIA-Part3試験は、内部監査のキャリアを追求する個人の知識とスキルをテストする認定試験です。この試験は、内部監査者研究所(IIA)が提供する認定内部監査士(CIA)プログラムの一部であり、内部監査に必要なビジネス知識に焦点を当てています。
IIA Internal Audit Function 認定 IIA-CIA-Part3 試験問題 (Q70-Q75):
質問 # 70
What is the percentage of the total variance that can be explained by the regression equation?
- A. 80.982%
- B. 99.862%
- C. 99.724%
- D. 69.613%
正解:C
解説:
The coefficient of determination (r2) measures the percentage of the total variance in cost that can be explained by the regression equation. If the coefficient of determination is .99724, 99.724% of the variance is explained by the regression equation. Thus, the values in the regression equation explain virtually the entire amount of total cost.
質問 # 71
An internal auditor is trying to assess control risk and the effectiveness of an organization's internal controls. Which of the following audit procedures would not provide assurance to the auditor on this matter?
- A. Reading the board's minutes.
- B. Observing the organization's operations.
- C. Inspecting manuals and documents.
- D. Interviewing the organization's employees.
正解:A
質問 # 72
Which of the following is a likely result of outsourcing?
- A. Decreased focus on costs
- B. Increased dependence on suppliers.
- C. Decreased sensitivity to government regulation
- D. Increased importance of market strategy.
正解:C
質問 # 73
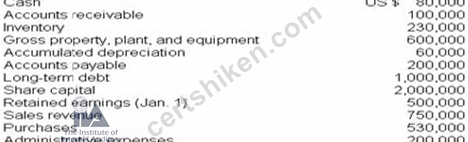
Which adjusting entry should be used at year-end to account for interest expense on the long-term debt?
- A. Interest expense US $50,000 Cash US $50,000
- B. Interest payable US $100,000 Interest expense US $100,000
- C. Interest expense US $50,000 Interest payable US $50,000
- D. Interest expense US $100,000 Interest payable US $100,000
正解:C
解説:
The debt was issued on July 1 and has been outstanding for only 6 months. Interest expense equals the face amount of the debt multiplied by the interest rate and the fraction of the year the debt was outstanding [US $1.000.000 x 10% x6 - 12) = US $50,000].
Because interest is payable on July1 6 months' interest is accrued and expensed in the current period. The payable is also recognized in the current period. Thus, the adjusting entry should be
Interest expense US $50,000 Interest payable US $50.000
Copper Co. had the pre-closing trial balance at December 31 shown below. Additional information: The balance of opening inventory was US $140,000. The long-term debt pays interest at a rate of 10% per annum, payable every 12 months. The debt was issued on July 1 of the current year and originally had 5 years to maturity. The assets classified as property, plant, and equipment have a 10-year estimated useful life and were 1 year old at the start of the current year Straight-line depreciation is used.
質問 # 74
An internal auditor is assessing the risks related to an organization's mobile device policy. She notes that the organization allows third parties (vendors and visitors) to use outside smart devices to access its proprietary networks and systems. Which of the following types of smart device risks should the internal Auditor be most concerned about?
- A. Strategic
- B. Physical security
- C. Privacy
- D. Compliance.
正解:D
質問 # 75
......
IIA-CIA-Part3過去問: https://www.certshiken.com/IIA-CIA-Part3-shiken.html
- IIA-CIA-Part3専門試験 🐗 IIA-CIA-Part3関連試験 ✅ IIA-CIA-Part3認定資格 🔛 サイト【 www.passtest.jp 】で「 IIA-CIA-Part3 」問題集をダウンロードIIA-CIA-Part3資格取得講座
- IIA-CIA-Part3過去問題 ⬆ IIA-CIA-Part3試験番号 🐋 IIA-CIA-Part3試験番号 🧗 ⮆ www.goshiken.com ⮄は、“ IIA-CIA-Part3 ”を無料でダウンロードするのに最適なサイトですIIA-CIA-Part3資格取得講座
- 便利IIA-CIA-Part3|最高のIIA-CIA-Part3資格練習試験|試験の準備方法Internal Audit Function過去問 🔼 ➠ www.mogiexam.com 🠰で使える無料オンライン版( IIA-CIA-Part3 ) の試験問題IIA-CIA-Part3試験番号
- IIA-CIA-Part3参考書 🎫 IIA-CIA-Part3資格取得講座 😗 IIA-CIA-Part3無料試験 🏤 ウェブサイト{ www.goshiken.com }から☀ IIA-CIA-Part3 ️☀️を開いて検索し、無料でダウンロードしてくださいIIA-CIA-Part3模擬対策
- 有難いIIA-CIA-Part3資格練習 - 合格スムーズIIA-CIA-Part3過去問 | 実用的なIIA-CIA-Part3日本語独学書籍 🔇 ⮆ jp.fast2test.com ⮄から簡単に( IIA-CIA-Part3 )を無料でダウンロードできますIIA-CIA-Part3合格問題
- 便利なIIA-CIA-Part3資格練習 - 合格スムーズIIA-CIA-Part3過去問 | 100%合格率のIIA-CIA-Part3日本語独学書籍 💖 今すぐ➽ www.goshiken.com 🢪を開き、[ IIA-CIA-Part3 ]を検索して無料でダウンロードしてくださいIIA-CIA-Part3日本語学習内容
- IIA IIA-CIA-Part3 Exam | IIA-CIA-Part3資格練習 - 優れた試験ツールを保証 🛐 { www.japancert.com }で✔ IIA-CIA-Part3 ️✔️を検索して、無料でダウンロードしてくださいIIA-CIA-Part3無料試験
- IIA-CIA-Part3専門試験 🎥 IIA-CIA-Part3関連試験 🦑 IIA-CIA-Part3模擬問題集 🦒 ウェブサイト☀ www.goshiken.com ️☀️を開き、▛ IIA-CIA-Part3 ▟を検索して無料でダウンロードしてくださいIIA-CIA-Part3過去問題
- 100%合格率-信頼的なIIA-CIA-Part3資格練習試験-試験の準備方法IIA-CIA-Part3過去問 🙍 【 www.xhs1991.com 】には無料の➥ IIA-CIA-Part3 🡄問題集がありますIIA-CIA-Part3参考書
- 実用的IIA-CIA-Part3|最新のIIA-CIA-Part3資格練習試験|試験の準備方法Internal Audit Function過去問 📱 ✔ www.goshiken.com ️✔️を開き、☀ IIA-CIA-Part3 ️☀️を入力して、無料でダウンロードしてくださいIIA-CIA-Part3日本語学習内容
- IIA-CIA-Part3認定資格 🕣 IIA-CIA-Part3模擬トレーリング 🐣 IIA-CIA-Part3的中率 🦡 ( IIA-CIA-Part3 )を無料でダウンロード{ www.goshiken.com }ウェブサイトを入力するだけIIA-CIA-Part3過去問題
- myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, www.stes.tyc.edu.tw, fortunetelleroracle.com, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, myportal.utt.edu.tt, Disposable vapes
P.S.CertShikenがGoogle Driveで共有している無料の2026 IIA IIA-CIA-Part3ダンプ:https://drive.google.com/open?id=14t8lh8Ph2NAg5NKFuGZPNKlU1y6QGS6p