P.S. Free 2026 CISI IFC dumps are available on Google Drive shared by ActualPDF: https://drive.google.com/open?id=1-LYPyXh2E-3LCmatsddXcDOms801X958
Many candidates apply for professional certifications exams because their company has business with relating company. If so our IFC exam guide torrent should be your best helper. Our IFC exam questions help you pass exam soon and certainly so that you can obtain dreaming certifications before other peers. It will be a great opportunity for you to obtain better position even promotion. You can trust our reliable IFC Exam Collection materials as we have high pass rate more than 98%.
| Certification Vendor: | CSI (Canadian Securities Institute) |
|---|---|
| Exam Name: | Investment Funds in Canada (IFC) |
| Exam Number: | IFC |
| Passing Score: | 60% |
| Certificate Validity Period: | 2 years |
| Available Languages: | English, French |
| Exam Duration: | 180 minutes |
| Exam Format: | Multiple Choice |
| Exam Price: | CAD 520.00 |
| Real Exam Qty: | 100 |
| Sample Questions: | CISI IFC Sample Questions |
| Exam Way: | Proctored (remote or in-person at a test centre) |
| Pre Condition: | None |
| Official Syllabus URL: | https://www.csi.ca/student/en_ca/courses/csi/ifc.xhtml |
The fact that CISI IFC questions are available in three different formats enables users to prepare according to their styles. To test out the IFC study material, you can download a free CISI IFC demo from ActualPDF. You receive 1 year of free IFC Questions updates and 24-hour customer service. To avoid disappointment and failure, purchase IFC exam preparation material and begin your Investment Funds in Canada (IFC) Exam (IFC) exam preparation.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
| Topic 5 |
|
| Topic 6 |
|
| Topic 7 |
|
NEW QUESTION # 280
Dale will be using his mutual fund portfolio to supplement his income from other sources. He is comfortable with variable payouts and fluctuating markets. What is the best solution for Dale?
Answer: D
Explanation:
Dale is using his mutual fund portfolio for income, is comfortable with variable payouts, and accepts market fluctuations.
A ratio withdrawal plan pays out a fixed percentage of the fund's value each year. Since the percentage is applied to a fluctuating fund value, the payouts vary with market performance. This makes it suitable for investors who can tolerate variability.
In contrast:
Life withdrawal plans and annuities provide more predictable income.
Fixed-period plans are designed to exhaust the investment over a set period, which may not align with Dale's needs.
Thus, the best option is the Ratio withdrawal plan, which matches Dale's comfort with variable payouts and fluctuating markets.
NEW QUESTION # 281
Your client contacts you requesting that you purchase a mutual fund based on a "hot tip" from a friend who has been a successful investor. What bias is your client most likely being affected by?
Answer: C
Explanation:
Overconfidence bias leads investors to overestimate their knowledge or the reliability of information, such as a "hot tip," prompting them to act without sufficient due diligence. The feedback from the document states:
"Overconfidence is defined generally as unwarranted faith in one's intuitive reasoning, judgements and cognitive abilities. People tend to overestimate both their predictive abilities as well as the precision of the information they have been given. For example, an investor may get a tip from a wealth advisor or read something on the Internet about an investment opportunity, and then take action (that is, make the decision to invest) based on her perceived knowledge advantage." Reference: Chapter 5 - Behavioural FinanceLearning Domain: The Know Your Client Communication Process
NEW QUESTION # 282
Exchange traded funds (ETFs) that track an index and index mutual funds have many similarities. However, what is a major difference between these two products?
Answer: C
Explanation:
ETFs can be purchased continuously throughout the trading day while index funds can only be bought or sold at the end of the day. This is because ETFs are traded on a stock exchange like stocks, while index funds are traded directly with the fund company like mutual funds. This difference gives ETFs more liquidity and flexibility than index funds, as investors can buy and sell ETFs at any time during market hours at the prevailing market price. Index funds, on the other hand, are priced only once a day at the end of the day based on the net asset value per unit (NAVPU) of the fund. Both ETFs and index funds are prone to tracking errors (A), which are the differences between the performance of the fund and the performance of the underlying index. Tracking errors can be caused by various factors, such as fees, expenses, dividends, rebalancing, and market conditions. The market price of ETFs does not always match the underlying basket of securities , as it is determined by supply and demand in the market. There can be a discrepancy between the market price and the NAVPU of an ETF, which is called the premium or discount. Index funds, on the other hand, are priced based on the NAVPU of the fund, which reflects the value of the underlying securities. Both ETFs and index funds have management fees (D), as they are both types of mutual funds that incur costs for managing and operating the fund. However, ETFs usually have lower management fees than index funds, as they are more passive and have lower turnover and distribution costs.
NEW QUESTION # 283
A sample of four portfolios is given below, with an even split between allocations 1 and 2.
Portfolios | Allocation #1 | Allocation #2
Portfolio A
Preferred shares
Common shares
Portfolio B
Treasury bills
Debentures
Portfolio C
Debentures
Common shares
Portfolio D
Treasury bills
Preferred shares
Which portfolio carries the greatest amount of risk?
Answer: D
Explanation:
Risk hierarchy in CSC: Common shares (highest risk), Preferred shares, Debentures, Bonds, T-bills (lowest risk) .
Portfolio analysis:
A (Preferred + Common) # Medium-high risk.
B (T-bills + Debentures) # Low-medium risk.
C (Debentures + Common) # Contains common shares (high risk) plus debentures (credit risk), making it highest overall risk.
D (T-bills + Preferred) # Low risk.
Therefore, Portfolio C carries the greatest amount of risk.
NEW QUESTION # 284
What does a Sharpe ratio of 1 indicate?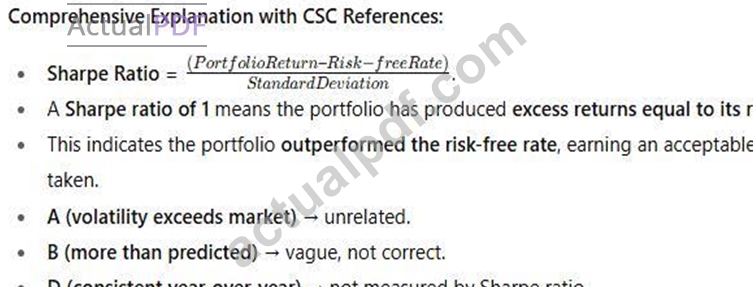
Answer: D
NEW QUESTION # 285
......
IFC Practice Exams Free: https://www.actualpdf.com/IFC_exam-dumps.html
BONUS!!! Download part of ActualPDF IFC dumps for free: https://drive.google.com/open?id=1-LYPyXh2E-3LCmatsddXcDOms801X958