BONUS!!! Download part of PDFTorrent Financial-Management dumps for free: https://drive.google.com/open?id=1Cv0kCb5LkQKGUL1jXv8Gb2hSjgDfS2bH
In accordance with the actual exam, we provide the latest Financial-Management exam dumps for your practices. With the latest Financial-Management test questions, you can have a good experience in practicing the test. Moreover, you have no need to worry about the price, we provide free updating for one year and half price for further partnerships, which is really a big sale in this field. After your payment, we will send the updated Financial-Management Exam to you immediately and if you have any question about updating, please leave us a message.
| Section | Objectives |
|---|---|
| Topic 1: Financial Management Concepts | - Financial Markets and Institutions
|
| Topic 2: Capital Budgeting | - Cash Flow Estimation
|
| Topic 3: Time Value of Money | - Bond and Stock Valuation
|
| Topic 4: Cost of Capital and Capital Structure | - Leverage and Capital Structure
|
| Topic 5: Working Capital Management | - Current Asset Management
|
| Topic 6: Financial Statement Analysis | - Financial Statement Basics
|
>> Financial-Management Test Dumps.zip <<
In this cut-throat competitive world of PDFTorrent, the WGU Financial-Management certification is the most desired one. But what creates an obstacle in the way of the aspirants of the WGU Financial-Management certificate is their failure to find up-to-date, unique, and reliable Financial-Management practice material to succeed in passing the WGU Financial-Management certification exam. If you are one of such frustrated candidates, don't get panic. PDFTorrent declares its services in providing the real Financial-Management PDF Questions.
NEW QUESTION # 45
A recent news article reported that a popular tech start-up has not yet reached profitability or experienced a period of positive cash flows from operations. Instead, the company has been focused primarily on capturing market share and attracting new customers.
What does the continued negative cash flow from operations (CFO) signal about this firm?
Answer: C
Explanation:
Cash flow from operations reflects the cash generated (or consumed) by a firm's core business activities. When CFO is consistently negative, it indicates that operating expenses and working capital needs exceed cash inflows from sales. For start-ups, this is common during early growth phases, as firms spend heavily on marketing, technology, and customer acquisition to build scale and future revenue potential. However, from a financial management perspective, negative CFO also signals cash burn. Unless offset by financing inflows (equity or debt) or expected future positive cash flows, continued operating losses can threaten liquidity and solvency. Analysts closely monitor burn rate, funding runway, and the firm's ability to transition to sustainable operations. Option C accurately captures this risk-focused interpretation, whereas the other options either mischaracterize negative CFO or contradict its fundamental meaning.
NEW QUESTION # 46
Why must analysts be cautious about accounting practices when analyzing ratios?
Answer: D
Explanation:
Accounting methods influence reported financial results and, consequently, financial ratios. Differences in depreciation methods, inventory valuation (FIFO vs. LIFO), revenue recognition, and expense capitalization can significantly alter earnings, assets, and equity. When analysts compare ratios across firms or over time, failure to account for these differences can lead to incorrect conclusions about profitability, efficiency, or risk. Financial management emphasizes adjusting or at least recognizing accounting differences to improve comparability and interpret ratios accurately. Option A correctly explains why caution is required, while the remaining options incorrectly assume uniformity or rigidity in accounting practices.
NEW QUESTION # 47
What is a potential drawback of lowering the annual dividend payment?
Answer: B
Explanation:
Dividend policy carries important signaling effects in financial markets. Investors often view dividends as a signal of management's confidence in the firm's future cash flows. When a company lowers its dividend, shareholders may interpret the action as a sign of financial distress, declining profitability, or uncertainty about future earnings. This negative perception can result in a decline in the firm's stock price and reduced investor confidence. While dividend reductions may free up cash for reinvestment and improve long-term financial flexibility, the short-term market reaction is often unfavorable.
Financial management literature stresses that dividend changes should be made cautiously and clearly communicated to avoid misinterpretation. Option D correctly identifies this key drawback.
NEW QUESTION # 48
Use Whole Pine Inc.'s financial statements for 20X3 below to answer the following question.
What is Whole Pine Inc.'stotal asset turnoverfor 20X3?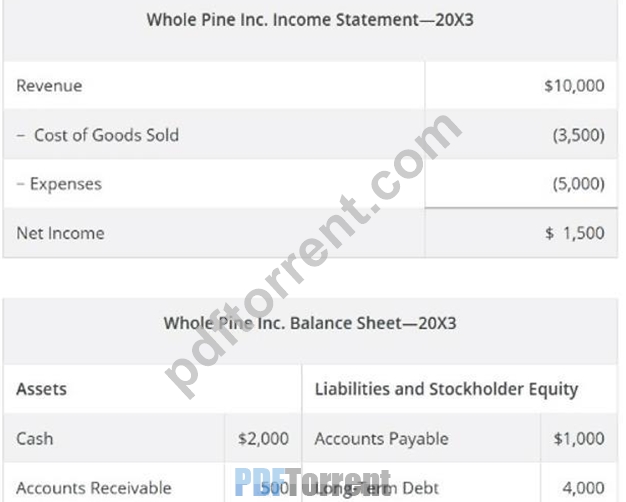
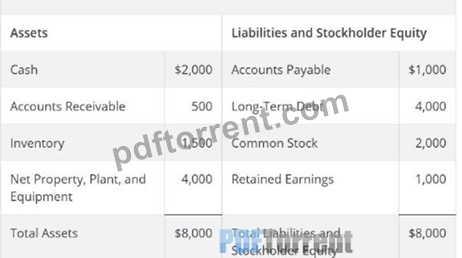
Answer: D
Explanation:
Total asset turnover measures how efficiently a firm uses its assets to generate revenue. It is calculated as Sales ÷ Total Assets. For Whole Pine Inc., sales for 20X3 are $10,000 and total assets are $8,000.
Dividing $10,000 by $8,000 yields a total asset turnover of 1.25. This means the company generates
$1.25 in sales for every $1.00 invested in assets. From a financial management perspective, this ratio is a key indicator of operating efficiency and is commonly compared across firms within the same industry or across time. A higher turnover suggests more efficient use of assets, while a lower turnover may indicate underutilized capacity or inefficient asset deployment. Asset turnover is also a component of the DuPont analysis, linking operational efficiency to return on equity. Option B correctly reflects both the calculation and interpretation consistent with standard financial analysis practice.
NEW QUESTION # 49
How does company size relate to capital structure in terms of access to financing options?
Answer: B
Explanation:
Company size has a significant effect on capital structure because larger firms generally have better access to external financing markets. Large companies often have more stable cash flows, broader operating histories, stronger credit profiles, and greater name recognition among investors and lenders. As a result, they are more likely to obtain financing from both debt markets and equity markets on favorable terms. They may be able to issue bonds publicly, negotiate better loan agreements, and attract equity investors more easily than smaller firms. In contrast, smaller firms often face more information asymmetry, less predictable earnings, and fewer financing alternatives, which can increase their cost of capital and limit access to long-term funding. Choice A is too narrow and not generally true. Choice C is incorrect because larger firms are usually less dependent on internal financing, not more. Choice D is also incorrect because smaller firms often face higher borrowing costs due to greater perceived risk. Financial management theory recognizes firm size as an important determinant of financing flexibility and capital structure. Therefore, B is correct because larger firms typically enjoy broader and cheaper access to both debt and equity capital.
========
NEW QUESTION # 50
......
PDFTorrent provides you with WGU Financial-Management exam questions in 3 different formats to open up your study options and suit your preparation tempo. The WGU Financial-Management PDF is the most convenient format to go through all exam questions easily. It is a compilation of actual WGU Financial-Management exam questions and answers.
Latest Financial-Management Exam Dumps: https://www.pdftorrent.com/Financial-Management-exam-prep-dumps.html
2026 Latest PDFTorrent Financial-Management PDF Dumps and Financial-Management Exam Engine Free Share: https://drive.google.com/open?id=1Cv0kCb5LkQKGUL1jXv8Gb2hSjgDfS2bH