DOWNLOAD the newest ITExamDownload PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1Qi7ING8Z5_t7bOKCO5XjI3bOBpfjdQ-S
Our product is dedicated to providing a better understanding of the the PF1 exa, through providing the stimulated environment of the PF1 exam, it will benefit you while taking part in the exam. For your benefit, we also have money back gurantee if you fail to pass the exam. Once you have passed the PF1exam, it is directly linked to yur salary and the position of you in your copany. The certificate is also a stimulation of you, it proves that the ability of you is impoved,and it will offers you more opportunities in the future job market.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Communication and Compliance | 10% | - Accuracy and documentation
|
| Topic 2: Individual Pay Calculations | 40% | - Non-regular earnings
|
| Topic 3: Termination and Special Payments | 30% | - Termination payments
|
| Topic 4: Record of Employment (ROE) | 20% | - Submission and deadlines
|
We provide free update to the client and the discounts to the old client. We provide free update of our PF1 exam materials within one year and after one year the client can enjoy the 50% discounts. The old clients enjoy some certain discounts when they buy our PF1 exam torrent. Our experts check whether there is the update of the test bank every day and if there is the system will send to the client automatically. We choose the most typical questions and answers which seize the focus and important information and the questions and answers are based on the real exam. So you can master the most important PF1 Exam Torrent in the shortest time and finally pass the exam successfully.
NEW QUESTION # 69
Raminder was hired in January 1997. He was fully vested in the organization's pension plan at the time he received the retiring allowance. His employment was terminated on May 1, 2006 and he was paid a
$10,000.00 retiring allowance. Calculate the eligible portion of the retiring allowance.
Answer: B
Explanation:
The "eligible portion" of a retiring allowance (the part that may be transferred directly to an RRSP/RPP on a tax-deferred basis without using regular RRSP room) is based on years of service before 1996 (and potentially an additional amount for certain pre-1989 years). CRA explains that the eligible part is: $2,000 for each year or part-year of service before 1996, plus an additional $1,500 for each year or part-year of service before 1989 only if no employer-funded pension/DPSP benefits for those years were vested (or previously paid out).
Raminder was hired in January 1997, so he has zero years (or part-years) of service before 1996, and therefore he has no base eligible amount under the $2,000-per-year rule. Because he also has no pre-1989 service, the additional $1,500-per-year rule does not apply either.
So, the eligible portion is $0, meaning none of the $10,000 retiring allowance is eligible (option D).
NEW QUESTION # 70
Paula is granted a pay increase. The paperwork informing the payroll department of the pay increase is two pay periods late. What method would be used to calculate income taxes on the separate retroactive payment?
Answer: A
Explanation:
A payment made to "catch up" wages because a pay increase was processed late is a retroactive payment. The CRA provides different income tax calculation approaches depending on the payment type and specifically lists "Retroactive payments" as its own category, separate from regular tax-table calculations, lump-sum, and bonus/irregular methods.
For bonuses and retroactive pay increases, the CRA also points employers to the Payroll Deductions Online Calculator (PDOC) to calculate CPP, EI, and income tax correctly, which aligns with using the appropriate CRA method for retroactive amounts.
Because this situation is explicitly a retroactive adjustment (two pay periods late), the correct choice is the Retroactive tax method (option C), not the bonus/irregular method, not the lump-sum method, and not the regular tax tables.
NEW QUESTION # 71
A premium payment for overtime hours worked or a rate per piece of goods produced is an example of:
Answer: D
Explanation:
Overtime premiums and piece-rate pay are forms of earnings because they are amounts paid for work performed. CRA's payroll guidance confirms overtime pay is remuneration from which you must deduct statutory deductions (CPP, EI, and income tax), reflecting that overtime is treated as employment earnings.
Similarly, piecework (piece-rate pay) is a method of paying wages based on units produced rather than time.
It is still compensation for labour and therefore part of gross earnings used to calculate payroll deductions and net pay. This is fundamentally different from:
Expense reimbursements, which repay employee-incurred business costs (not pay for work).
Allowances, which are predetermined amounts to help cover anticipated expenses without receipts.
Benefits, which are the value of goods/services provided by the employer or paid on the employee's behalf.
So a premium paid for overtime hours or a piece-rate per unit produced is classified as earnings (option A).
NEW QUESTION # 72
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)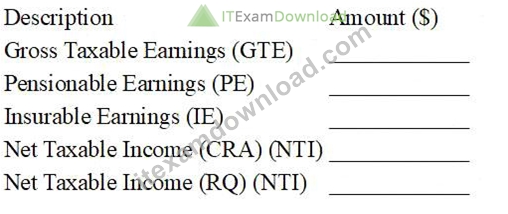
STATUTORY DEDUCTIONS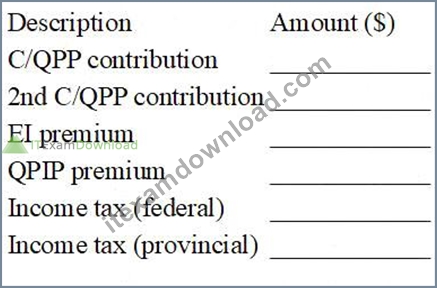
OTHER DEDUCTIONS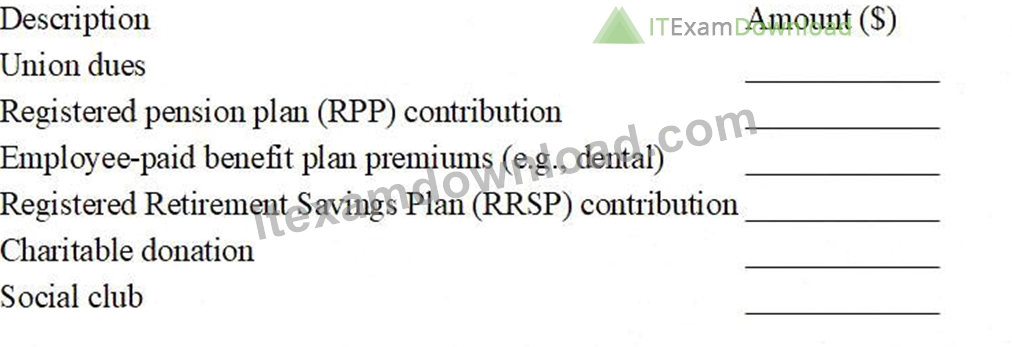
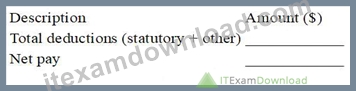
Given Data (Reference)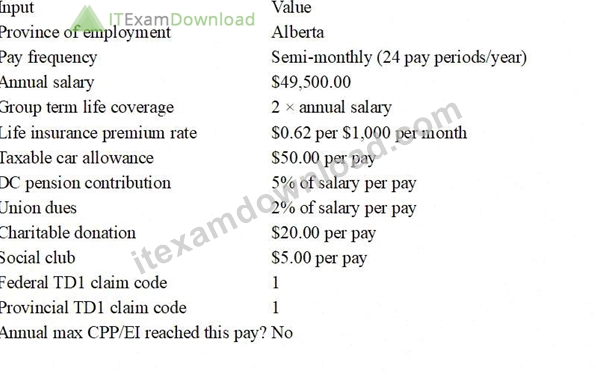
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 73
Rosa joined Avion Electronics in April 1983. Her employment was terminated on November 30, 2015 and she was paid a $62,500.00 retiring allowance. Rosa joined her company's pension plan in 1986 and was fully vested on termination of employment. Calculate the non-eligible portion of the retiring allowance.
Answer:
Explanation:
$32,000.00 non-eligible portion
Explanation:
CRA requires separating a retiring allowance into an eligible and non-eligible portion. The eligible portion is the maximum that can be transferred to an RRSP/RPP under the special rules (without using regular RRSP room). The formula is: $2,000 for each year (or part-year) of service before 1996, plus an additional $1,500 for each year (or part-year) before 1989 in which the employee had no employer pension/DPSP benefit vested at the time of payment (or previously paid).
Rosa worked from 1983 to 1995 (inclusive) for pre-1996 service: 13 years × $2,000 = $26,000.
For the extra pre-1989 amount: she joined the pension plan in 1986 and was fully vested when paid the retiring allowance in 2015, so 1986-1988 do not qualify for the extra $1,500. However, 1983-1985 were years before 1989 when she had no vested employer pension benefit, so 3 years × $1,500 = $4,500.
Eligible portion = $26,000 + $4,500 = $30,500.
Non-eligible portion = $62,500 # $30,500 = $32,000.
NEW QUESTION # 74
......
As we entered into such a web world, cable network or wireless network has been widely spread. That is to say, it is easier to find an online environment to do your practices. This version of PF1 test prep can be used on any device installed with web browsers. We specially provide a timed programming test in this online test engine, and help you build up confidence in a timed exam. With limited time, you need to finish your task in PF1 Quiz guide and avoid making mistakes, so, considering your precious time, we also suggest this version that can help you find out your problems immediately after your accomplishment.
PF1 Latest Dump: https://www.itexamdownload.com/PF1-valid-questions.html
What's more, part of that ITExamDownload PF1 dumps now are free: https://drive.google.com/open?id=1Qi7ING8Z5_t7bOKCO5XjI3bOBpfjdQ-S