DOWNLOAD the newest TopExamCollection ClaimCenter-Business-Analysts PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1kXtKy_vgqpABkPJUEUX9NuYG8ggF747v
To cater to the different needs of different customers, our product for ClaimCenter-Business-Analysts exam have provide three different versions of practice materials. I f you are more like the paper version, then PDF version will be your choice, since this version can be printed. If you are more likely to use the computer, the Desktop version is your choice, this version can provide you the feeling of the Real ClaimCenter-Business-Analysts Exam.If you prefer to practice the materials on online, then online version is your choice, this version support all web browers, and you can practice it in your free time if you want. Just try it, there is always a version for you.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
>> Related ClaimCenter-Business-Analysts Certifications <<
During nearly ten years, our company has kept on improving ourselves on the ClaimCenter-Business-Analysts study questions, and now we have become the leader in this field. And now our ClaimCenter-Business-Analysts training materials have become the most popular ClaimCenter-Business-Analysts Practice Engine in the international market. There are so many advantages of our ClaimCenter-Business-Analysts guide quiz, and as long as you have a try on them, you will definitely love our exam dumps.
NEW QUESTION # 33
Succeed Insurance has a requirement to add a new high-risk indicator to the Claim Status screen for property claims that have a lien on the property. A new icon will be added to the configuration to provide a visual indicator making it easier for Adjusters and other ClaimCenter users to determine that a claim has a lien.
Which two common areas of the user interface (UI) can display the new lien icon? (Choose two.)
Answer: D,E
Explanation:
In the standard Guidewire ClaimCenter User Interface architecture, high-priority alerts and claim indicators are displayed in two primary locations to ensure visibility:
* The Info Bar (Option D):This is the persistent strip located at the top of the claim file (just below the Tab Bar). It remains visible regardless of which specific claim sub-screen (Medical, Financials, Notes) the user is navigating. It is designed specifically to host "High Risk Indicators" such as Litigation, Fatalities, Coverage issues, and in this scenario, a "Lien" indicator. This ensures the adjuster is aware of the critical status immediately upon opening the claim.
* The Screen Area (Option A):Specifically, theClaim Status(or Summary) screen-which resides in the main Screen Area-contains a dedicated section for "Claim Indicators." Here, the icon is displayed along with a text description and potential toggle status (On/Off). The prompt explicitly mentions the requirement to "add a new high-risk indicator to the Claim Status screen," confirming the Screen Area as the second location.
Why other options are incorrect:
* Sidebar (B):The sidebar (left panel) is used for the "Actions" menu and navigation links (steps) to move between screens. It does not typically host status icons for the claim object itself.
* Workspace (C):While "Workspace" can refer to the application frame, in UI terminology, it often refers to the specific worksheets (bottom pane) or the container, not the specific UI element for indicators.
* Tab Bar (E):The Tab Bar is for high-level navigation (Claim, Desktop, Administration, Search) and does not display claim-specific data icons.
NEW QUESTION # 34
Succeed Insurance has a strategic initiative to change auto insurance into a pay-as-you-drive model... When claims are processed, claimants must provide the log from the application for the date of incident. The log's details are essential to validation and analysis of the monitoring system's activity at the time of the incident.
Without the application log, claims should not be processed to indemnification.
Executives say the implementation team must maintain the base product functionality where appropriate and only change those things essential to the success of the initiative...
Which two requirements are in scope based on the guiding principles? (Choose two.)
Answer: A,B
Explanation:
When defining scope based on specific strategic initiatives and guiding principles (such as "only change those things essential"), the Business Analyst must map requirements directly to the stated business rules and critical success factors.
* Requirement D (Log Intake):The scenario explicitly states:"The log's details are essential to validation and analysis... claimants must provide the log."Option D directly captures this by requiring the log to be received, reviewed, and attached. This is the core data intake requirement.
* Requirement C (Validation Rule):The scenario states:"Without the application log, claims should not be processed to indemnification."Option C directly maps to this business rule. It utilizes base product capabilities (Validation Rules) to enforce the "No Log, No Pay" constraint, ensuring the initiative's security and validity.
Why other options are incorrect:
* Option B (OEM Integration):The scenario mentions leveraging integration "where possible," but creates a requirement for "application logs," not direct integration with "top five vehicle manufacturers." Adding a rigid schedule ("one integration every 30 days") is a high-cost, high- complexity constraint that contradicts the principle of maintaining base functionality and minimizing cost/maintenance unless explicitly required.
* Option A (Mileage):While mileage is part of the concept, theessentialrequirement described for the claim process is thevalidation of the logfor the incident. Tracking mileage is secondary to the critical path of validating the accident data via the log.
NEW QUESTION # 35
An auto accident in Chicago, Illinois has been reported to Succeed Insurance. The customer service representative uses the ClaimCenter standard Claim Wizard to set up the new claim. The policy is verified in effect and based on the reported exposures the total loss points calculated is 38. There is also a note to have an expert inspection via approved vendor.
What is the most likely claim setup with regards to this reported auto accident?
Answer: D
Explanation:
ClaimCenter uses a logic-based process called Segmentation to categorize claims and Assignment to route them.
* Complexity (Points):The "Total Loss Points" score of38is significantly high. In standard configuration, high scores (typically indicating severe damage or total loss potential) trigger aHigh Complexitysegmentation.
* Assignment (Geography):The accident occurred inChicago (Midwest). The assignment rules will match the geography (Midwest) with the complexity (High/Complex). Therefore, it routes to the Midwest Complex Auto Adjusters Group.
* Workplan (Activity):The specific note regarding an "expert inspection" translates into a generated Activity(likely "Assign Vehicle Inspection" or similar) added to the claim's workplan.
Why other options are incorrect:
* A & D (Low/Mid Complexity):A score of 38 is too high for "Low Complexity" (which is usually for simple fender benders). Assigning a complex claim to a "Low Complexity" group would violate standard routing logic.
* C (Supervisor):Modern ClaimCenter configurations prefer Straight-Through Processing (STP) to a working group. Routing to a Supervisor is generally a fallback for exceptions, whereas this is a standard high-severity scenario that should go directly to the specialized adjusters.
NEW QUESTION # 36
An Adjuster at Succeed Insurance increases the reserve on a claim's exposure from $1,000 to $1,500 to account for inflation in repair costs. A week later, a Supervisor reviews the claim and wants to know specifically who made this change, the exact date and time it was made, and what the previous value was.
The Supervisor needs a chronological audit trail of changes to the claim file without navigating through complex financial ledgers.
Which screen in the ClaimCenter user interface should the Supervisor access to find this information?
Answer: C
NEW QUESTION # 37
An Adjuster at Succeed Insurance is handling a homeowners claim with a dwelling exposure for damage to the insured's home. The Adjuster's Authority Limit Profile has the following limits: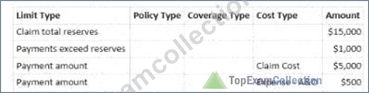
The table below is a view of the property claims organization within Succeed Insurance. The Adjuster is a member of the group Property - Team A.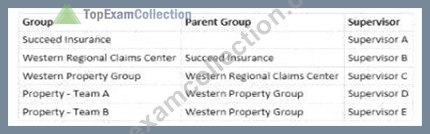
The Adjuster creates a payment in the amount of $6,500 for repairs to the insured's home. How will it be processed assuming that the claim has sufficient reserves for the payment?
Answer: D
Explanation:
This scenario involves checking financial Authority Limits and determining the correct Approval Routing hierarchy in Guidewire ClaimCenter.
* Check Authority Limits:First, compare the transaction amount against the user's specific limits.
* The payment is for "repairs to the insured's home," which is classified asClaim Cost(Indemnity).
* According to the provided Authority Limit Profile, the Adjuster has a "Payment amount" limit of
$5,000for Claim Cost.
* The transaction amount is$6,500.
* Since$6,500 > $5,000, the limit is exceeded, meaning the paymentrequires approval(Ruling out Option B).
* Determine Routing:When a financial transaction requires approval, ClaimCenter routes the approval activity to the supervisor of the group to which the user belongs.
* The Adjuster is a member ofProperty - Team A.
* According to the Organization chart provided, the Supervisor for "Property - Team A" is Supervisor D.
* Therefore, the system will generate an approval activity and assign it specifically to Supervisor D). Supervisor C is the manager of theparentgroup (Western Property Group), so the activity would only go to them if Supervisor Dalsolacked the authority to approve the $6,500, requiring further escalation. However, the initial routing is always to the immediate supervisor.
Why other options are incorrect:
* Option A:Supervisor C is the "Grand-boss" (Supervisor of the parent group), not the immediate supervisor.
* Option B:The amount ($6,500) clearly exceeds the defined limit ($5,000), so automatic processing is impossible.
* Option C:Supervisor A is at the top of the hierarchy (Succeed Insurance), far removed from the initial approval step.
NEW QUESTION # 38
......
Why is TopExamCollection Guidewire ClaimCenter-Business-Analysts certification training so popular, especially among the same trade? Firstly, we really know what the candidates need. Secondly, Our TopExamCollection Guidewire ClaimCenter-Business-Analysts dumps are concerned on one thing only – how to help the candidates to pass Guidewire ClaimCenter-Business-Analysts test. Thirdly, Our TopExamCollection Guidewire ClaimCenter-Business-Analysts study guide is very technical and original. We provide you with the latest test questions and test answers. And the price is very cost-effective.
Reliable ClaimCenter-Business-Analysts Exam Syllabus: https://www.topexamcollection.com/ClaimCenter-Business-Analysts-vce-collection.html
2026 Latest TopExamCollection ClaimCenter-Business-Analysts PDF Dumps and ClaimCenter-Business-Analysts Exam Engine Free Share: https://drive.google.com/open?id=1kXtKy_vgqpABkPJUEUX9NuYG8ggF747v