Our website gives detailed guidance to our candidates for the preparations of PF1 actual test and lead them toward the direction of success. Each question in PF1 pass guide is certified by our senior IT experts to improve candidates' ability and skills. The quality of training materials and the price of our PF1 Dumps Torrent are all created for your benefit. Just add it to your cart.
| Section | Objectives |
|---|---|
| Payroll Fundamentals and Compliance Framework | - Payroll system overview in Canada
|
| Earnings, Deductions, and Taxation | - Deductions and remittances
|
| Payroll Records and Compliance Reporting | - Recordkeeping requirements
|
>> Latest Study PF1 Questions <<
Our PF1 study guide offers you more than 99% pass guarantee. And we believe you will pass the PF1 exam just like the other customers. At the same time, if you want to continue learning, PF1 guide torrent will provide you with the benefits of free updates within one year and a discount of more than one year. In the meantime, as an old customer, you will enjoy more benefits whether you purchase other subject test products or continue to update existing PF1 learning test.
NEW QUESTION # 31
An employee has the use of a company-leased vehicle for both business and personal use. This is an example of:
Answer: C
Explanation:
This is a benefit because the employer is providing access to an automobile (leased by the employer) that the employee can use for personal driving as well as business. The CRA explains that when an employer-owned or employer-leased automobile is made available for personal use, the employee receives a taxable automobile benefit, generally made up of a standby charge (availability of the vehicle) and potentially an operating expense benefit (if the employer pays operating costs and the employee has personal kilometres).
It is not an allowance (which is typically a cash amount given to the employee), and it is not an expense reimbursement (repayment of employee-incurred business expenses). It is also not an earning (pay for work performed). Payroll's role is to track availability days/months, business vs personal kilometres, any employee reimbursements, apply the CRA calculation methods, and report the taxable benefit on the employee's information slip with the correct taxable benefit treatment.
NEW QUESTION # 32
Phillip is being paid a severance payment with his final pay. Which block should this payment be reported on the Record of Employment?
Answer: A
Explanation:
On the ROE, separation payments are reported in Block 17. Service Canada explains that Block 17C - Other monies is used to record "any other payments or benefits...paid...because of the separation," whether or not they are insurable.
The ROE Guide specifically lists "Severance pay" as a type of separation money to enter in Block 17C ("Enter 'Severance pay' and the amount").
Crucially, Block 15B and Block 15C are for insurable earnings totals/by pay period. The ROE Guide notes that some amounts reported in Block 17 (like vacation pay) are insurable and must be added into Blocks 15B
/15C; however, retirement leave credits/retiring allowances (a form of severance-type payment) are not insurable and are not added to Blocks 15B/15C even though they are recorded in Block 17C.
So, severance is reported in Block 17C only.
NEW QUESTION # 33
Ursula is 17 years old, works in Quebec and earns $750.00 weekly. Ursula pays weekly union dues of $18.00 along with a special weekly union assessment of $10.00 for construction of a new union hall for its members.
Ursula also has registered pension plan (RPP) contributions of $20.00 deducted from each pay. Calculate Ursula's net federal taxable income.
Answer:
Explanation:
$712.00
Explanation:
For payroll income tax purposes, net taxable income starts with the employee's gross taxable income and then subtracts only those deductions that are deductible for income tax and can be recognized at source. CRA payroll guidance shows this approach by subtracting items such as RPP contributions and union dues when determining net taxable income for calculating income tax deductions.
Gross taxable income (weekly): $750.00.
RPP contributions are deductible (the amounts reported from box 20 of the T4 are generally deductible).
Regular union dues are deductible; however, the CRA states that deductible annual union/professional dues do not include special assessments or charges for anything other than ordinary operating costs. A levy specifically for constructing a new union hall is a special assessment, so it is not deductible as union dues.
So the deductions that reduce federal taxable income here are: $18.00 (union dues) + $20.00 (RPP) = $38.00.
Net federal taxable income = $750.00 # $38.00 = $712.00.
NEW QUESTION # 34
In Block 6 of the Record of Employment, what pay period type is entered for employees who are paid salary plus regularly paid commission?
Answer: C
Explanation:
In Block 6 (Pay period type), Service Canada instructs employers to enter the employee's actual pay period type-one of the standard types such as weekly, biweekly, semi-monthly, monthly, or 13 pay periods a year.
Service Canada identifies a special rule only for employees "paid solely on commission or on salary plus irregularly paid commission": in those cases, the employer must use a weekly pay period and average earnings using the weekly averaging formula.
Because this question specifies salary plus regularly paid commission (not irregularly paid commission), the
"special situation" rule does not apply. Therefore, you enter the pay period type that matches the employer's normal payroll cycle for that employee (for example, weekly, biweekly, semi-monthly, monthly, etc.).
NEW QUESTION # 35
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)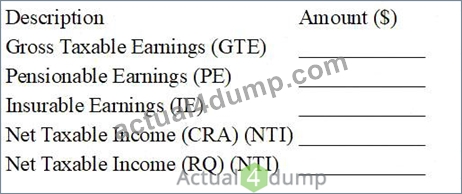
STATUTORY DEDUCTIONS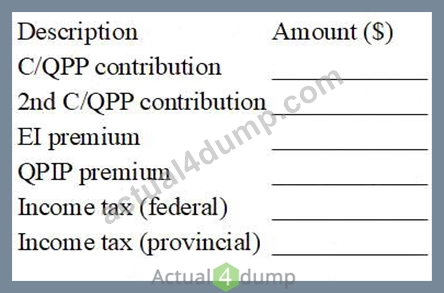
OTHER DEDUCTIONS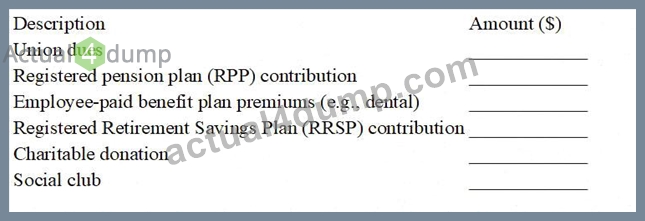
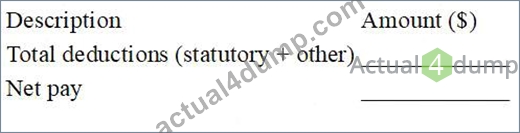
Given Data (Reference)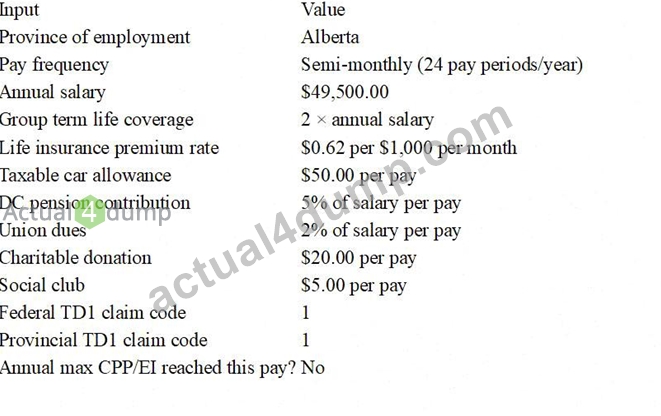
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 36
......
We have chosen a large number of professionals to make PF1 learning question more professional, while allowing our study materials to keep up with the times. Of course, we do it all for you to get the information you want, and you can make faster progress. You can also get help from PF1 exam training professionals at any time when you encounter any problems. We can be sure that with the professional help of our PF1 Test Guide you will surely get a very good experience. Good materials and methods can help you to do more with less. Choose PF1 test guide to get you closer to success.
Latest PF1 Braindumps Questions: https://www.actual4dump.com/National-Payroll-Institute/PF1-actualtests-dumps.html