まだPF1試験に昼夜を問わず滞在していますか? 答えが「はい」の場合は、CertJukenのPF1試験資料を試してください。 私たちNational Payroll Instituteは、最も正確で有用な情報を含むコンテンツだけでなく、最も迅速で最も効率的なアシスタントを提供するアフターサービスについても専門的です。 当社のPF1練習トレントを20〜30時間使用すると、PF1試験に参加する準備が整い、期待されるPayroll Fundamentals 1Examスコアを達成できると主張できます。
| Section | Objectives |
|---|---|
| Topic 1: Payroll Fundamentals and Compliance Framework | - Payroll system overview in Canada
|
| Topic 2: Earnings, Deductions, and Taxation | - Types of earnings
|
| Topic 3: Payroll Records and Compliance Reporting | - Recordkeeping requirements
|
持ってきた製品があなたにふさわしくないと感じることはよくありますか? PF1学習ガイドを使用することに決めた場合、問題に遭遇することは決してないことを伝えたいと思います。私たちのPF1学習教材は、あなたが期待できない高品質を持っています。 PF1学習教材のガイダンスで経験を積むと、以前よりも短時間で過ごすことができ、明らかに進歩を感じることができます。また、PF1のテストクイズは、進歩に役立つことがわかります。
質問 # 68
Helen is reimbursed for the cost of the protective clothing that is legally required for her job. The clothing she bought isnot supported by receiptsand is a reasonable reimbursement amount. This is considered:
正解:B
解説:
Even though the question uses the word "reimbursed," the key fact isno receipts. In CRA terms, when an employee is paid a set amount or is not required to substantiate the expense, the payment functions like an allowance, not an accountable reimbursement. CRA's guidance on uniforms/special or protective clothing states these amounts aregenerally taxable, and only in specific circumstances under CRA administrative policy would they be non-taxable.
CRA interpretations also reinforce that where employeesdo not have to provide receipts, a clothing allowance is generally ataxable employment benefit; non-taxable treatment is linked to substantiation and meeting strict conditions (for example, safety footwear with receipts).
So, because Helen's payment isnot supported by receipts, it is best classified as ataxable allowance(option A). Payroll should include the amount in taxable income, apply required withholdings as applicable, and ensure policy/records support whatever treatment is used.
質問 # 69
An employee who lives in Ontario and reports to work at a permanent establishment of the employer in Quebec will have income tax deducted based on which province?
正解:B
解説:
For payroll deductions, the key concept is the employee's province of employment (POE)-not where they live. The CRA states that the POE is determined primarily by the employer's establishment where the employee "reports for work." If an employee reports for work at an employer's establishment located in Quebec, then the POE is Quebec, even if the employee's province of residence is Ontario.
This matters because Quebec has distinct payroll requirements. The CRA notes that when the POE is Quebec, employers must apply Quebec-based payroll rules, including deducting Quebec Pension Plan (QPP) contributions instead of CPP, and deducting Quebec parental insurance plan (QPIP) premiums, along with Quebec provincial income tax withholding.
In practice, payroll must set up the employee using Quebec as the POE and ensure stakeholders (HR, finance, the employee) understand why deductions may differ from Ontario residents working in Ontario. Any over
/under-withholding due to POE vs. residence is typically reconciled when the employee files their personal tax return.
質問 # 70
(PF1 Exam - Net Pay Calculation Template Worksheet: Quebec)
Question ID: pf1-exam-npc-q-f
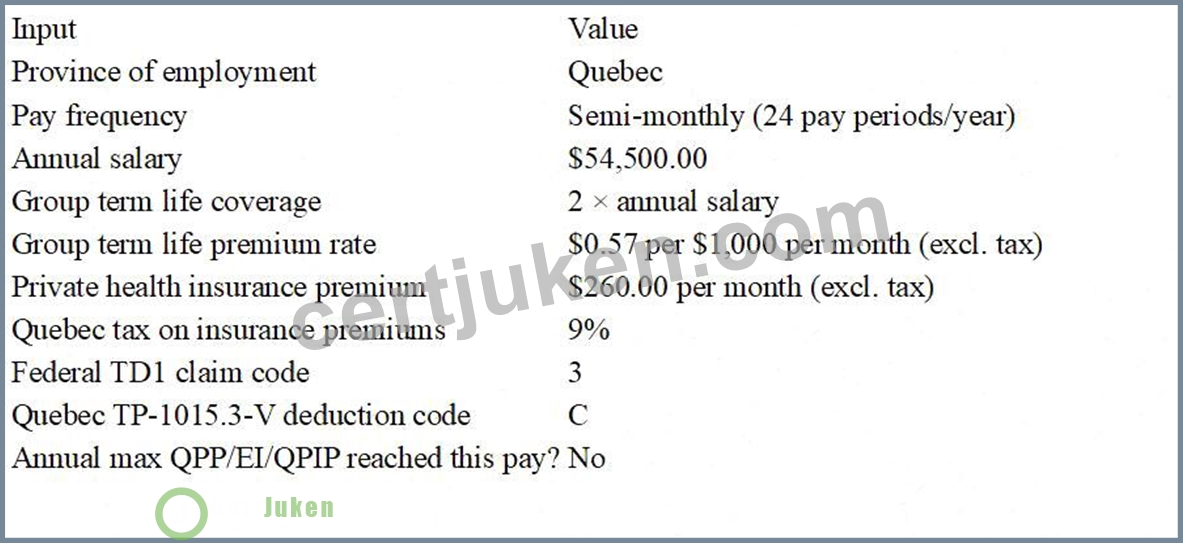
Mara Poirier works for Affordable Transport in Quebec and earns an annual salary of $54,500.00, paid on a semi-monthly basis.
In addition to her regular salary, Mara's employer provides the following benefits:
Group term life insurance coverage through a third party of two times her annual salary.
Monthly group term life insurance premiums are $0.57 per $1,000.00 of coverage, excluding taxes.
Private health insurance benefits with a monthly premium of $260.00, excluding taxes.
The tax on insurance premiums in Quebec is 9%.
Mara's federal TD1 claim code is 3 and her provincial TP-1015.3-V deduction code is C.
Mara will not reach the annual maximums for QPP, EI, or QPIP in this pay period.
Required: Calculate Mara's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)
Earnings / Income Bases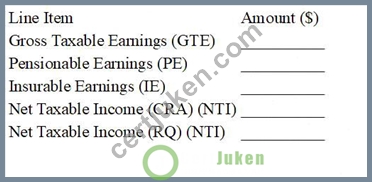
Step 1 - Calculate Mara's gross earnings for this pay period (GTE).
[ ____________________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ ____________________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ ____________________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ ____________________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ ____________________________________________ ]
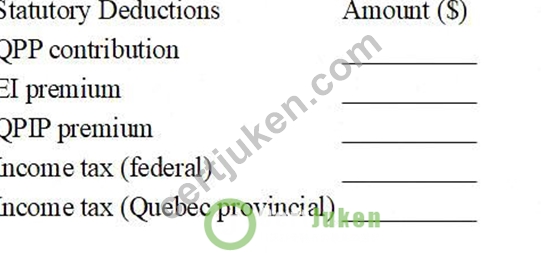
Step 6 - Calculate Mara's Quebec Pension Plan (QPP) contribution.
[ ____________________________________________ ]
Step 7 - Calculate Mara's Employment Insurance (EI) premium.
[ ____________________________________________ ]
Step 8 - Calculate Mara's Quebec Parental Insurance Plan (QPIP) premium.
[ ____________________________________________ ]
Step 9 - Determine Mara's federal income tax.
[ ____________________________________________ ]
Step 10 - Determine Mara's Quebec provincial income tax.
[ ____________________________________________ ]
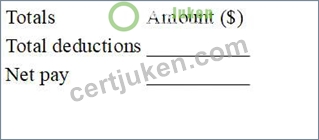
Step 11 - Calculate Mara's total deductions.
[ ____________________________________________ ]
Step 12 - Calculate Mara's net pay.
[ ____________________________________________ ]
正解:
解説:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Mara's gross earnings / taxable earnings components
Semi-monthly salary = $54,500.00 ÷ 24 = $2,270.83
Life insurance coverage = 2 × $54,500 = $109,000
Monthly premium (excl. tax) = 109 × $0.57 = $62.13
9% insurance premium tax = $62.13 × 1.09 = $67.72
Semi-monthly taxable benefit = $67.72 ÷ 2 = $33.86
Health premium (excl. tax) = $260.00
9% insurance premium tax = $260.00 × 1.09 = $283.40
Semi-monthly taxable benefit (Quebec) = $283.40 ÷ 2 = $141.70
GTE (total taxable in Quebec) = 2,270.83 + 33.86 + 141.70 = $2,446.39
Step 2 - Pensionable earnings (PE)
For this calculation, treat salary + taxable group term life as pensionable for QPP withholding, while EI remains non-insurable for non-cash benefits.
PE = 2,270.83 + 33.86 = $2,304.69
Step 3 - Insurable earnings (IE)
IE = salary only = $2,270.83
Step 4 - Net taxable income (CRA) (NTI)
Federal taxable income uses salary plus taxable benefits used for federal withholding tables here.
NTI (CRA) = $2,304.69
Step 5 - Net taxable income (RQ) (NTI)
NTI (RQ) = $2,446.39
Step 6 - QPP contribution
Use the QPP employee rate (basic + additional) and apply the basic exemption prorated per pay period.
Basic exemption per semi-monthly period = $3,500 ÷ 24 = $145.83
Contributory earnings = PE # 145.83 = 2,304.69 # 145.83 = $2,158.86
QPP = 2,158.86 × 6.4% = $138.17
QPP = $138.17
Step 7 - EI premium
Quebec EI employee rate for 2026: 1.30%.
EI = 2,270.83 × 0.0130 = $29.52
Step 8 - QPIP premium
Use the Revenu Quebec employee QPIP rate shown for 2026.
QPIP = 2,270.83 × 0.00430 = $9.76
Step 9 - Federal income tax
From the CRA Quebec federal tax deductions table (24 pay periods), at pay $2,304.69 (range 2288-2306) and claim code 3, the federal tax is:
Federal tax = $139.95
Step 10 - Quebec provincial income tax
From TP-1015.TI.24 (24 pay periods) at remuneration $2,446.39 (range 2445.00-2464.99) and deduction code C, the tax is:
Quebec tax = $214.81
Step 11 - Total deductions
QPP 138.17
EI 29.52
QPIP 9.76
Federal 139.95
Quebec 214.81
= $532.21
Total deductions = $532.21
Step 12 - Net pay
Net pay is based on cash pay (salary) minus deductions (tax still applies even when part of taxable income is a benefit).
Net pay = 2,270.83 # 532.21 = $1,738.62
質問 # 71
Benefits are:
正解:A
解説:
In Canadian payroll, a benefit generally means the employer has provided something of value to the employee (or paid for something on the employee's behalf), rather than paying cash for work performed. The CRA's Employers' Guide - Taxable Benefits and Allowances (T4130)explains that a benefit/allowance may be provided in cash (for example, an allowance) or in a manner other than cash (for example, a parking space or gift), and that employers may have to include the value of that benefit/allowance in the employee's income depending on the circumstances.
Option C best captures this "value of something provided or paid for" concept. Option B describes wages
/salary (earnings for work). Option A aligns more with reimbursements/expense coverage. Option D aligns with allowances for business use of personal property (often treated separately and may be taxable or non- taxable depending on CRA rules and documentation). Payroll's role is to determine whether the benefit is taxable, value it correctly, and apply the right statutory withholdings and reporting.
質問 # 72
How many pay periods will be used to calculate insurable earnings inBlock 15Bon the Record of Employment if the employee is paidweekly?
正解:B
解説:
For apaper ROE, Service Canada's ROE guidance uses a set number ofmost recent consecutive pay periods to support the reporting of insurable earnings. InBlock 15C(insurable earnings by pay period), the paper ROE provides27 fields, which allows reporting up to27 weekly pay periods(or fewer if the employee worked fewer periods).
Block15Bis thetotal insurable earningsfor the applicable number of consecutive pay periods, and for a weekly payroll this aligns with the same maximum count used on the paper ROE earnings grid-27periods.
Practically, this means payroll totals the employee's insurable earnings for thelast 27 consecutive weekly pay periodsleading up to the interruption of earnings (or the full period of employment if shorter). Using the correct number of pay periods ensures Service Canada has the right earnings history to adjudicate EI benefits accurately and reduces ROE processing issues.
質問 # 73
......
弊社のPF1問題集はIT業界で有名で、ブランドになっています。PF1問題集はすごく人気がある商品で、どこでも広告を掲載する必要がないです。従って、多くの受験者は弊社のPF1問題集を選びました。なぜ彼らがPF1問題集を選ぶかというと、弊社のPF1問題集は高品質で、便利で、勉強しやすいからです。弊社のPF1問題集を買う人は全部PF1試験にいい成績で合格しました。
PF1 PDF: https://www.certjuken.com/PF1-exam.html