DOWNLOAD the newest Pass4cram AFP-Exam-1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1MPbsECaaZLISVfjp3bxhV_VmdbC97LAD
This pdf covers all of the AFP-Exam-1 Exam Questions from the previous exams as well as those that will appear in the upcoming CSI AFP-Exam-1 exam. The AFP-Exam-1 PDF exam questions are compiled according to the latest exam syllabus to ensure your success. The CSI AFP-Exam-1 PDF exam questions are also printable to make handy notes.
| Section | Weight | Objectives |
|---|---|---|
| Technical Competencies | 84% | - Retirement Planning - Investment Planning - Risk Management and Insurance - Tax Planning - Estate Planning - Asset and Liability Management |
| Enabling Competencies | 16% | - Client Relationship and Practice Management - Professional Conduct and Regulatory Compliance |
>> Valid Study AFP-Exam-1 Questions <<
Pass4cram will provide you with actual Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam questions in pdf to help you crack the CSI AFP-Exam-1 exam. So, it will be a great benefit for you. If you want to dedicate your free time to preparing for the Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam, you can check with the soft copy of pdf questions on your smart devices and study when you get time. On the other hand, if you want a hard copy, you can print Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam questions.
NEW QUESTION # 27
Janet's non-registered account holds the funds listed in the following table: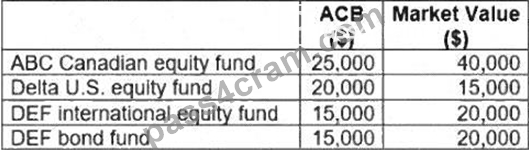
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: D
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 28
Edward is risk averse and has limited investment knowledge. He will only purchase 100% guaranteed products insured by the CDIC. Edward is meeting with his financial planner, Marissa, for the third time this year about rates, and starts the meeting by criticizing her employer for paying such low returns on GICs.
Edward says he is considering taking his business elsewhere. How should Marissa respond to Edward's comments?
Answer: A
Explanation:
Marissa should respond with empathy and accuracy. Edward is risk averse, has limited investment knowledge, and will only purchase CDIC-insured guaranteed products. The correct response is to acknowledge his frustration, explain that the displayed rates are the best she can offer, and allow him to compare alternatives without pressure. Matching competitor rates may be outside her authority and could misrepresent the firm's pricing. Telling him to increase risk tolerance to obtain a better return ignores his stated constraints and may lead to unsuitable advice. Claiming her rate is the highest in the market would be inappropriate unless she can substantiate it, and even then the statement may become stale quickly. In AFP client management, the planner preserves trust by respecting the client's risk profile, communicating honestly, and avoiding product pressure. Study Guide focus: client communication, risk tolerance, guaranteed products, suitability, and relationship management. This response protects suitability because Edward's product universe is defined by capital guarantee and deposit insurance.
NEW QUESTION # 29
Tom has two children from a previous marriage. He has been paying $1,000 per month for spousal support and $1,500 per month for child support to his ex-wife. Recently, his ex-wife was awarded increased child support payments from Tom to cover unanticipated university expenses for one of the children. What should Tom's financial planner advise him about how this increased monthly payment may impact his finances?
Answer: B
Explanation:
The increased child support payment reduces Tom's net cash flow by the full amount. Under the standard tax treatment, child support is not deductible to the payer and is not taxable to the recipient. That differs from qualifying periodic spousal support, which may be deductible to the payer and taxable to the recipient when the legal requirements are met. Because the increased amount relates to child support for university expenses, Tom receives no tax deduction and no offsetting tax credit merely because he pays more. The tuition tax credit belongs to the eligible student unless transferred under applicable rules; it is not automatically applied to Tom because he pays support. The planner should update Tom's cash-flow plan, debt ratios, retirement savings ability, and emergency reserve using the full increased payment. Study Guide focus: child support, spousal support, tax deductibility, cash-flow planning, and separation agreements. This distinction is essential when modelling separation settlements because gross payments and after-tax cost can differ sharply.
NEW QUESTION # 30
A client sends an email alleging that a mutual fund recommendation was unsuitable because the fund declined sharply after purchase. The client asks for compensation. What is the financial planner's first professional obligation?
Answer: D
Explanation:
The issue is complaint governance. A written allegation of unsuitable advice and a request for compensation must be treated as a complaint, even if the planner believes the recommendation was defensible. The planner should preserve the communication, record the relevant facts, notify the appropriate supervisory channel, and follow the firm's complaint process. The file should contain the original KYC information, risk-tolerance evidence, fund recommendation rationale, disclosure documents, trade record, and subsequent communications. Option A is improper because compensation should not be promised before the complaint is reviewed under firm policy. Option B is dismissive; market loss alone may not prove unsuitability, but the complaint still requires a formal response. Option C is unacceptable and would create a serious recordkeeping and conduct breach. A professional process protects both parties: the client receives a fair review, and the planner demonstrates procedural discipline, supervision, and documentation. References/topics: complaint handling, suitability review, recordkeeping, regulatory compliance.
NEW QUESTION # 31
A client wants to state her wishes about medical treatment if she becomes incapable of communicating.
Which document is most directly relevant?
Answer: A
Explanation:
A living will, advance health-care directive, or personal care directive records the client's wishes regarding medical and personal-care decisions if the client later lacks capacity or cannot communicate. The exact terminology varies by province, but the planning purpose is consistent: it guides substitute decision-makers and health-care providers about treatment preferences, end-of-life care, and personal values. Option A governs investment objectives and constraints. Option C authorizes trading activity and has no health-care function. Option D summarizes assets and liabilities but does not express medical wishes. A planner should not draft legal health-care documents unless qualified, but should identify the planning need and recommend legal advice. The document should be coordinated with any power of attorney for personal care or equivalent appointment, because naming the decision-maker and documenting wishes are complementary. Incapacity planning is distinct from a will, which operates after death. References/topics: living will, personal care directive, incapacity planning, substitute decision-making.
NEW QUESTION # 32
......
You can trust Pass4cram and download AFP-Exam-1 exam questions to start preparation with complete peace of mind and satisfaction. The AFP-Exam-1 exam questions have already helped countless CSI AFP-Exam-1 exam candidates. They got success in their dream AFP-Exam-1 Certification Exam with flying colors. They did this with the help of real, valid, and updated AFP-Exam-1 exam questions. You can also get success in the Applied Financial Planning Certification Exam 1 (AFP) certification exam with AFP-Exam-1 exam questions.
Frenquent AFP-Exam-1 Update: https://www.pass4cram.com/AFP-Exam-1_free-download.html
BTW, DOWNLOAD part of Pass4cram AFP-Exam-1 dumps from Cloud Storage: https://drive.google.com/open?id=1MPbsECaaZLISVfjp3bxhV_VmdbC97LAD