Test4Sure is website that can help a lot of IT people realize their dreams. If you have a IT dream, then quickly click the click of Test4Sure. It has the best training materials, which is Test4Sure;s Guidewire ClaimCenter-Business-Analysts Exam Training materials. This training materials is what IT people are very wanted. Because it will make you pass the exam easily, since then rise higher and higher on your career path.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
| Topic 5 |
|
>> Test ClaimCenter-Business-Analysts Online <<
Our company guarantees this pass rate from various aspects such as content and service on our ClaimCenter-Business-Analysts exam questions. We have hired the most authoritative professionals to compile the content Of the ClaimCenter-Business-Analysts study materials. And we offer 24/7 service online to help you on all kinds of the problems about the ClaimCenter-Business-Analysts learning guide. Of course, we also consider the needs of users, ourClaimCenter-Business-Analysts exam questions hope to help every user realize their dreams.
NEW QUESTION # 48
Which two actions may the Business Analyst (BA) perform based on the roles and permissions functionality of ClaimCenter? (Choose two.)
Answer: A,D
Explanation:
The Roles and Permissions functionality (part of the Role-Based Access Control or RBAC model) in ClaimCenter is designed to simplify security administration. A Business Analyst utilizes this functionality to define how users access the system.
* Defining Roles (Option A):A "Role" in Guidewire is fundamentally a named container for a set of System Permissions(e.g., claimview, activitycreate). The BA defines a role (like "Adjuster" or
"Supervisor") by consolidating the necessary individual permissions into one single set.
* Simplifying Management (Option B):The primary benefit of this model is efficiency. Instead of assigning 50 individual permissions to 100 different users, the BA/Admin creates a "Collection of permissions" (the Role) and assigns that single Role to the group of users. This simplifies onboarding and maintenance.
Why other options are incorrect:
* Authority Limits (C):While related to security,Authority Limits(financial caps on reserves/payments) are technically distinct from "Roles and Permissions" functionality in the ClaimCenter object model.
Authority is handled via Authority Profiles, whereas Roles handle system access rights.
* Unique Permissions (D):This is the opposite of best practice. Assigning unique permissions to every user creates a maintenance nightmare. The best practice is to use standard Roles.
NEW QUESTION # 49
An auto claim is owned by Adjuster1. The Customer Service Representative (CSR) that created the claim owns one follow-up activity on the claim. An Injury Specialist owns an injury exposure on the claim. All these persons are members of Auto Team 1.
The Team Lead determines that Adjuster1 is overworked and reassigns the claim to Adjuster2, a member of Auto Team 2.
Which three people now have access to the claim? (Choose three.)
Answer: A,D,E
Explanation:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
In Guidewire ClaimCenter, access to a claim file is determined by Access Control Lists (ACLs), which are dynamically updated based on user roles and ownership. A user is granted access to a claim if they own the claim itself, or if they own a sub-object within that claim, such as an Activity or an Exposure.
* Adjuster2 (Option E):Upon reassignment, Adjuster2 becomes the newClaim Owner. The owner of the claim record always has full view and edit access to the claim.
* CSR (Option C):The CSR retains ownership of a specificActivity(the follow-up task). In the ClaimCenter security model, owning an open activity on a claim grants the user "view" access to the parent claim so they can perform the necessary work to complete their task. Reassigning the claim header does not automatically reassign the activities owned by other users.
* Injury Specialist (Option D):This user owns anExposure(a distinct financial sub-record for a specific coverage feature). Similar to activities, owning an exposure grants access to the parent claim. The reassignment of the main claim file from Adjuster1 to Adjuster2 does not strip the Injury Specialist of their ownership of the specific injury exposure.
Why Adjuster1 loses access:Adjuster1 was the previous owner. Once ownership is transferred to Adjuster2 (who is in a different group, "Auto Team 2"), Adjuster1 no longer meets the criteria for ownership access.
Unless Adjuster1 is explicitly added to the ACL manually or has "Super User" privileges (not stated), they lose the automatic access rights associated with being the owner.
NEW QUESTION # 50
A car accident in a rural area of Durango, Colorado is reported to Succeed Insurance. The driver of the damaged car reportedly hit the base of a windmill tower while driving at night. There was no other passenger in the car when the accident happened, and the driver has a valid auto policy on file.
While the driver is not physically injured, the entire passenger side of the car has been severely damaged.
Although the windmill is still functioning, the base of the tower has sustained multiple broken parts.
Which two incidents need to be created for the claim based on the reported accident? (Choose two.)
Answer: A,C
Explanation:
In Guidewire ClaimCenter, an Incident is the data object used to capture the specific facts about "what" was damaged or affected during the loss event. It serves as the foundation for creating Exposures (the financial liabilities).
* Vehicle Incident (Option C):The scenario states that the insured's car has been "severely damaged" on the passenger side. To record these facts-including the point of impact, the severity, and the vehicle description-the Adjuster must create aVehicle Incident. This incident will eventually support the collision coverage exposure.
* Property Incident (Option B):The accident involved the car hitting a "windmill tower," resulting in
"broken parts" to the base. In ClaimCenter, damage to third-party non-vehicular objects (like fences, poles, buildings, or towers) is captured using aFixed Property Incident(often referred to generically as a Property Incident). This incident records the damage description and ownership of the windmill, which is necessary to handle the Property Damage Liability claim.
Why other options are incorrect:
* Option E (Injury):The scenario explicitly states the driver is "not physically injured." Therefore, an Injury Incident is not required.
* Option A ("Another structure"):The standard object for third-party fixed property damage is the Property Incident/Fixed Property Incident, not "Another structure."
* Option D (Loss of Use):While possible later, the primary immediate damage is physical. Loss of Use is usually a secondary exposure type, not the primary incident definition for the tower itself.
NEW QUESTION # 51
Whenever the Total Loss Calculator determines that a vehicle is a total loss, Succeed Insurance wants to create a custom history event with the exposure name and total loss score.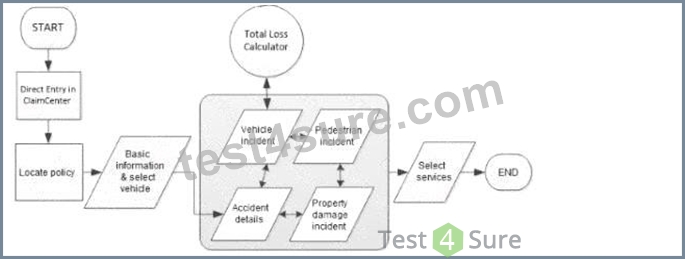
Which step in the claim setup process flow must be completed before the history event can be created?
Answer: B
Explanation:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
In Guidewire ClaimCenter workflow analysis and configuration, defining the correct sequence of operations is critically dependent on Data Availability and Data Dependency.
The specific requirement here dictates that the custom history event must capture theTotal Loss Score. In the context of the ClaimCenter object model and process flow, the Total Loss Score is anoutputvalue generated specifically by theTotal Loss Calculatorengine. Before this calculator runs, the score attribute is effectively null or non-existent.
Therefore, to satisfy the business requirement, the step that writes the history event must be placedafterthe step that generates the data it needs to record.
* Process Logic:If the Business Analyst were to place the history event creation stepbeforethe Total Loss Calculator (Option B) orbeforethe Vehicle Incident (Option D), the system would attempt to write a record containing a score that has not yet been calculated. This would result in either a system error or a history event with a blank/zero value, failing to meet the business requirement.
* Dependency Chain:The workflow dependency is: Vehicle Data Entry -> Total Loss Calculation -> Score Generation -> History Event Creation.
* Implementation Note:In a typical Guidewire implementation, this logic is often handled via "Event Fired" rules or specific "Exit Points" in the workflow. The system waits for the confirmation that the Total Loss calculation service has successfully returned a result. Once that transaction is committed and the score is persisted on the Vehicle or Exposure entity, the subsequent rule to generate the History Event can trigger successfully.
Consequently,Option Cis the only viable placement in the process flow. It ensures that the prerequisite action (calculation) is complete and the required data payload (the score) is available for the subsequent action (logging the history event).
NEW QUESTION # 52
A claim for an auto accident in Tampa, Florida has been reported and recorded in ClaimCenter. The ClaimCenter base product Global Claim Assignment Rule is utilized for automatic assignment to Adjusters regardless of complexity of claims.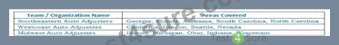
What is the likely path of assignment for this claim?
Answer: C
Explanation:
Claim Assignment in Guidewire ClaimCenter follows a two-step logic: Global Assignment (finding the right Group) and Group Assignment (finding the right User).
* Group Identification (Global Assignment):The first step relies on the geography of the loss.
According to the provided organization table, theSoutheastern Auto Adjustersgroup is responsible for
"Georgia,Florida, Alabama, South Carolina, North Carolina." Since the accident occurred inTampa, Florida, the Global Assignment rule will route the claim to the Southeastern Auto Adjusters group.
* User Assignment (Group Assignment):The prompt specifies the use of "automatic assignment...
regardless of complexity." In ClaimCenter's base configuration, the standard method for distributing claims automatically within a group isRound Robin(or Cyclical) assignment. This method assigns the claim to the next available adjuster in the list, ensuring an even distribution of volume without complex weighting calculations.
Why other options are incorrect:
* Option B (Midwest):Incorrect geography. The Midwest group covers IL, MI, OH, IN, WI, not Florida.
* Option C (Weighted Workload):While "Dynamic Assignment" (workload balancing) is a feature, the standard "automatic assignment" described implies a simple cyclical rotation (Round Robin). Weighted assignment is a more advanced configuration typically used when complexityisa factor (e.g., assigning fewer claims to junior adjusters).
* Option D (Supervisor):Assigning to a Supervisor is a manual fallback or "Assign to Supervisor" rule, usually triggered when no suitable adjuster is available or for complex exceptions. It is not the primary path for standard automatic assignment.
NEW QUESTION # 53
......
Your life will take place great changes after obtaining the ClaimCenter-Business-Analysts certificate. Many companies like to employ versatile and comprehensive talents. What you have learnt on our ClaimCenter-Business-Analysts study materials will meet their requirements. So you will finally stand out from a group of candidates and get the desirable job. Also, learning our ClaimCenter-Business-Analysts Study Materials will fulfill your dreams. Nothing will stop you as long as you are rich. Also, respect and power is gained through knowledge and skills. If you want to get a higher position in the company, you must have the ability to defeat other excellent colleagues.
ClaimCenter-Business-Analysts Reliable Test Answers: https://www.test4sure.com/ClaimCenter-Business-Analysts-pass4sure-vce.html