DOWNLOAD the newest Lead1Pass CIMAPRA19-F03-1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1dX5wCEYaRAj6DGXnLWKGoT_sMipqg3HN
Best practice indicates that people who have passed the CIMAPRA19-F03-1 exam would not pass the exam without the help of the CIMAPRA19-F03-1 study materials. So the study materials will be very important for all people. If you also want to pass the exam and get the related certification in a short, the good study materials are the best choice for you. Now we are going to make an introduction about the CIMAPRA19-F03-1 Study Materials from our company for you. We sincerely hope that our study materials will help you achieve your dream.
| Certification Vendor: | CIMA (Chartered Institute of Management Accountants) |
|---|---|
| Exam Name: | CIMA F3 Financial Strategy (Strategic Level Objective Test) |
| Exam Number: | CIMAPRA19-F03-1 |
| Passing Score: | 100/150 (scaled score, equivalent to ~60%) |
| Exam Price: | £120–£150 (varies by region and testing provider) |
| Exam Format: | Case-based questions, Multiple-choice questions, Computer-based Objective Test (OT) |
| Exam Duration: | 90 minutes |
| Certificate Validity Period: | No expiry for passed exams; CGMA designation requires ongoing CIMA membership |
| Related Certifications: | CIMA P3 Risk Management CGMA Designation CIMA E3 Strategic Management CIMA F3 Financial Strategy |
| Available Languages: | English |
| Real Exam Qty: | 60 questions |
| Recommended Training: | BPP CIMA Courses Kaplan CIMA Training |
| Exam Registration: | CIMA Official Exam Registration (My CIMA) CIMA Exam Booking Information |
| Sample Questions: | CIMA CIMAPRA19-F03-1 Sample Questions |
| Exam Way: | Computer-based exam delivered at authorised test centres or online proctoring where available. |
| Pre Condition: | Completion of CIMA Operational and Management levels is recommended (E3, P3, F3 sit within Strategic level of CIMA syllabus). |
| Official Syllabus URL: | https://www.aicpa-cima.com/cimaexams |
>> CIMAPRA19-F03-1 Pdf Format <<
Our team of experts updates actual CIMA CIMAPRA19-F03-1 questions regularly so you can prepare for the CIMAPRA19-F03-1 exam according to the latest syllabus. Additionally, we also offer up to 1 year of free CIMAPRA19-F03-1 exam questions updates. We have a 24/7 customer service team available for your assistance if you get stuck somewhere. Buy CIMAPRA19-F03-1 Latest Questions of Lead1Pass now and get ready to crack the CIMAPRA19-F03-1 certification exam in a single attempt.
CIMA CIMAPRA19-F03-1 is an essential exam for anyone looking to build a career in finance. The skills and knowledge gained from CIMAPRA19-F03-1 exam are in high demand by employers, and passing CIMAPRA19-F03-1 exam will open up a wide range of job opportunities. With the right preparation and dedication, candidates can successfully pass CIMAPRA19-F03-1 exam and move their finance career to the next level.
CIMA F3 exam is a computer-based test that assesses a candidate's knowledge related to financial management. CIMAPRA19-F03-1 exam is in three sections, which focus on topics such as financial strategy, financial risk management, and financial instruments. The F3 module evaluates a candidate's ability to analyze business situations and provide financial strategies for implementation. Additionally, it assesses a candidate's knowledge of financial instruments, including derivatives, and their ability to manage financial risk in various organizational contexts.
CIMA F3 (Financial Strategy) is a professional certification exam that is designed to test the knowledge and skills of candidates in the field of financial management. CIMAPRA19-F03-1 Exam is conducted by the Chartered Institute of Management Accountants (CIMA), which is a globally recognized professional body for management accountants. The CIMA F3 certification exam covers a broad range of financial management topics, including financial strategy, financial reporting, budgeting, risk management, and investment decisions.
NEW QUESTION # 260
An unlisted company has the following data: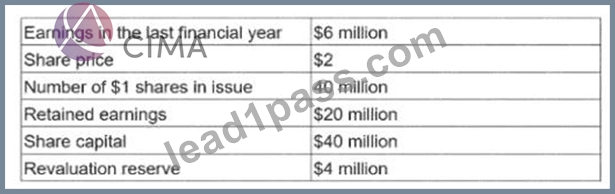
A listed company in the same industry has a P/E of 11.
The value of the unlisted company based on the P/E of this listed company is: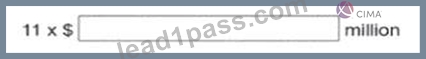
Give your answer to the nearest whole number.
Answer:
Explanation:
$66 million
Explanation:
This question applies the Price/Earnings (P/E) valuation method, which is covered in CIMA F3 under Business Valuation and Market-Based Valuation Techniques. The P/E method is commonly used to value unlisted companies by reference to a comparable listed company operating in the same industry, provided that earnings are representative and sustainable.
Under CIMA F3 guidance, when using a P/E multiple:
* The earnings figure used should be the most recent maintainable earnings.
* The P/E ratio should be taken from a listed comparator with similar business risk.
* The valuation focuses on equity value, not enterprise value.
In this scenario, the unlisted company reported earnings of $6 million in the last financial year. A listed company in the same industry has a P/E ratio of 11, which is assumed to appropriately reflect market expectations regarding growth and risk for businesses in this sector.
The valuation is therefore calculated as follows:
This gives an estimated equity value of $66 million.
It is important to note, in line with CIMA F3 principles, that balance sheet items such as retained earnings, share capital, and revaluation reserves are not directly relevant to a P/E-based valuation. The P/E approach is an income-based valuation method, relying solely on earnings and market multiples, rather than book values.
Rounding to the nearest whole number, as required by the question, confirms the final valuation.
NEW QUESTION # 261
Company P is a pharmaceutical company listed on an alternative investment market.
The company is developing a new drug which it hopes to market in approximately six years' time.
Company P is owned and managed by a group of doctors who wish to retain control of the company. The company operates from leased laboratories with minimal fixed assets.
Its value comes from the quality of its research staff and their research.
The company currently has one approved drug which generates sufficient cashflow to cover day to day operations but not sufficient for major new research and development.
Company P wish to raise debt finance to develop the new drug.
Recommend which of the following types of debt finance would be most appropriate for Company P to help finance the development of this new drug.
Answer: B
Explanation:
This question examines the appropriateness of debt financing instruments in the context of a high-risk, growth- oriented pharmaceutical company, which is a classic scenario discussed within CIMA F3 under Financing Decisions, Risk and Capital Structure, and Hybrid Finance.
Company P operates in a sector characterised by long development cycles, high uncertainty, and intangible asset bases. Its value derives primarily from human capital and intellectual property rather than tangible fixed assets. According to CIMA F3 study guidance, such firms face significant difficulty raising conventional straight debt, as lenders typically require stable cash flows and asset security. Furthermore, the company's existing cash flows are only sufficient for operational needs, not major R&D expenditure, increasing perceived credit risk.
A convertible bond is explicitly highlighted in CIMA F3 as a suitable financing instrument for companies with high growth potential but limited current cash flows. Convertible bonds combine features of debt and equity, offering investors downside protection through fixed interest payments while providing upside potential through conversion into equity if the company succeeds. This reduces the required coupon rate (4% in this case), easing short-term cash flow pressure, which is crucial for Company P during the development phase of the new drug.
Importantly, the doctors who own and manage Company P wish to retain control, a key strategic constraint.
Convertible bonds delay equity dilution until conversion occurs and only if the company performs well. This aligns with F3 principles that hybrid instruments are appropriate when firms wish to balance financing needs with control considerations.
The alternative options are unsuitable:
* Eurobonds and conventional bonds (Options A and B) require strong credit standing and asset backing.
* Commercial paper (Option C) is short-term, unsecured, and inappropriate for long-term R&D funding.
Therefore, consistent with CIMA F3 guidance on risk-adjusted financing strategy, the most appropriate choice is the convertible bond.
NEW QUESTION # 262
Listed company R is in the process of making a cash offer for the equity of unlisted company S.
Company R has a market capitalisation of $200 million and a price/earnings ratio of 10.
Company S has a market capitalisation of $50 million and earnings of $7 million.
Company R intends to offer $60 million and expects to be able to realise synergistic benefits of $20 million by combining the two businesses. This estimate excludes the estimated $8 million cost of integrating the two businesses.
Which of the following figures need to be used when calculating the value of the combined entity in $ millions?
Answer: C
Explanation:
EBIT = 5
Interest @5% on 10m = 0.5 # PBT = 4.5
Tax 20% = 0.9 # Earnings = 3.6
EPS = 3.6 / 10m = 0.36
Price = 3.60 # P/E = 10
Next year:
Interest @6% = 0.6 # PBT = 4.4
Tax 20% = 0.88 # Earnings = 3.52
EPS = 3.52 / 10m = 0.352
Expected P/E = 9.5 # price = 0.352 × 9.5 = 3.344 (# 3.34).
Drop = 3.60 # 3.34 = 0.26 # % drop = 0.26 / 3.60 # 7.2%.
NEW QUESTION # 263
A company has borrowings of S5 million on which it pays interest at 8%. It has an operating profit margin of
20%.
The company plans to increase borrowings by S2 million Interest on additional borrowings would be 10% and the operating profit margin would remain unchanged A debt covenant attached to the new borrowings requires interest cover to be at least 4 times throughout the period of the borrowing Interest cover is defined in the loan documentation as being based on operating profit What is the minimum sales value required each year to avoid a breach of the interest cover covenant'
Answer: B
Explanation:
Current debt interest:
Existing: 5m×8%=0.40m5\text{m} \times 8\% = 0.40\text{m}5m×8%=0.40m
New: 2m×10%=0.20m2\text{m} \times 10\% = 0.20\text{m}2m×10%=0.20m
Total interest = 0.60m
Let annual sales = SSS.
Operating profit margin = 20% # OP = 0.20 S.
Interest cover covenant:
0.20S0.60#4#0.20S#2.4#S#2.40.20=12.0 million\frac{0.20 S}{0.60} \ge 4 \Rightarrow 0.20 S \ge 2.4
\Rightarrow S \ge \frac{2.4}{0.20} = 12.0\ \text{million}0.600.20S#4#0.20S#2.4#S#0.202.4=12.0 million Correct answer: A. $12.00 million
NEW QUESTION # 264
Companies L. M N and O:
* are based in a country that uses the RS as its currency
* have an objective to grow operating profit year on year
* have the same total levels of revenue and cost
* trade with companies or individuals in the United States. All import and export trade with companies or individuals in the United States is priced in US$.
Typical import/export trade for each company in a year are as follows: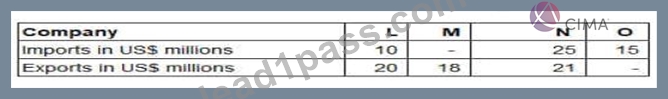
Which company's growth objective is most sensitive to a movement in the USS / RS exchange rate?
Answer: D
NEW QUESTION # 265
......
CIMAPRA19-F03-1 Pdf Free: https://www.lead1pass.com/CIMA/CIMAPRA19-F03-1-practice-exam-dumps.html
BTW, DOWNLOAD part of Lead1Pass CIMAPRA19-F03-1 dumps from Cloud Storage: https://drive.google.com/open?id=1dX5wCEYaRAj6DGXnLWKGoT_sMipqg3HN