P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by BraindumpsIT: https://drive.google.com/open?id=1QH581IB3ClBYiSzHoDgcQthrcTA5_iSF
The National Payroll Institute PF1 certification topics or syllabus are updated with the passage of time. To pass the National Payroll Institute Payroll Fundamentals 1Exam exam you have to know these topics. The BraindumpsIT PF1 certification exam trainers always work on these topics and add their appropriate National Payroll Institute PF1 Exam Questions And Answers in the PF1 exam dumps. These latest National Payroll Institute Payroll Fundamentals 1Exam exam topics are added in all National Payroll Institute Payroll Fundamentals 1Exam exam questions formats.
| Section | Objectives |
|---|---|
| Payroll Accounting | - Payroll accounting practices
|
| Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Year-End Processing | - Federal and provincial year-end reporting
|
| Provincial Remittances | - Provincial payroll requirements
|
| Non-Regular Payments | - Special payroll payments
|
| Employment Income – Regular Earnings | - Regular payroll calculations
|
| Record of Employment | - ROE processing
|
| Federal Remittances | - Government remittance obligations
|
| Workers’ Compensation | - Workers compensation administration
|
| Commission Payments | - Commission payroll processing
|
| New Employee Information | - Employee setup and documentation
|
| Termination of Employment | - Termination processing
|
| Non-Statutory Deductions | - Voluntary deductions
|
>> PF1 Reliable Dumps Questions <<
We have special online worker to solve all your problems. Once you have questions about our PF1 latest exam guide, you can directly contact with them through email. We are 7*24*365 online service. We are welcome you to contact us any time via email or online service. We have issued numerous products, so you might feel confused about which PF1 Study Dumps suit you best. You will get satisfied answers after consultation.
NEW QUESTION # 68
What is piecework?
Answer: C
Explanation:
Piecework (also called piece-rate pay) is a pay method where an employee's earnings are determined by output-they are paid a set amount per unit produced or completed, rather than by hours worked or a fixed salary. This aligns directly with option C. A time-based hourly/daily wage (option A) is a different earnings method, and a fixed pay-per-period arrangement (option B) describes salary. Therefore, "all of the above" is incorrect because these are three distinct compensation structures.
In payroll calculations, piecework earnings are typically calculated as: piece rate × number of units produced in the pay period. Employers still have to ensure compliance with employment standards, such as minimum wage and overtime rules, even where piecework is used. A Canadian payroll educational reference defines piecework as payment for each unit produced "regardless of the amount of time taken."
NEW QUESTION # 69
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.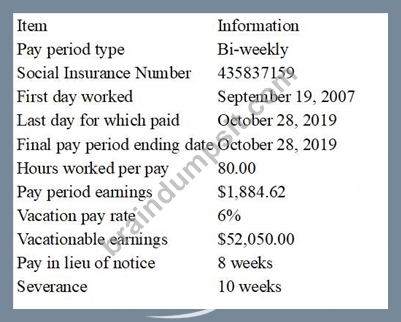
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)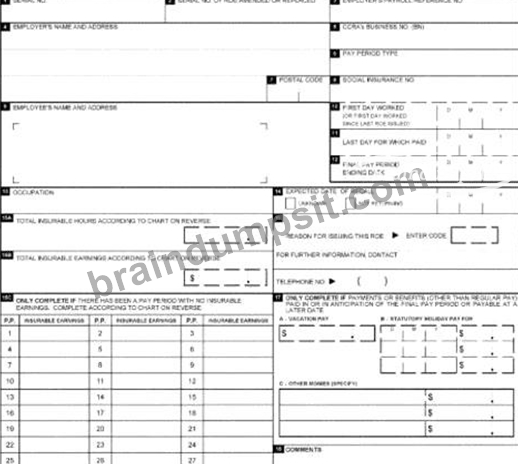
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 70
Ursula is 17 years old, works in Quebec and earns $750.00 weekly. Ursula pays weekly union dues of $18.00 along with a special weekly union assessment of $10.00 for construction of a new union hall for its members.
Ursula also has registered pension plan (RPP) contributions of $20.00 deducted from each pay. Calculate Ursula's net federal taxable income.
Answer:
Explanation:
$712.00
Explanation:
For payroll income tax purposes, net taxable income starts with the employee's gross taxable income and then subtracts only those deductions that are deductible for income tax and can be recognized at source. CRA payroll guidance shows this approach by subtracting items such as RPP contributions and union dues when determining net taxable income for calculating income tax deductions.
Gross taxable income (weekly): $750.00.
RPP contributions are deductible (the amounts reported from box 20 of the T4 are generally deductible).
Regular union dues are deductible; however, the CRA states that deductible annual union/professional dues do not include special assessments or charges for anything other than ordinary operating costs. A levy specifically for constructing a new union hall is a special assessment, so it is not deductible as union dues.
So the deductions that reduce federal taxable income here are: $18.00 (union dues) + $20.00 (RPP) = $38.00.
Net federal taxable income = $750.00 # $38.00 = $712.00.
NEW QUESTION # 71
The employee-employer relationship is deemed to be severed when:
Answer: C
Explanation:
In ROE administration, the key concept is whether the employment relationship is still "active" (that is, whether there is an ongoing expectation the employee will work again). Service Canada's ROE guidance ties ROE issuance to an interruption of earnings and specifically identifies situations where an employee is no longer on the employer's active employment list (for example, no expectation of future work) as a trigger for issuing an ROE.
Options A and B describe circumstances that can still align with an ongoing employment relationship. For example, employees may remain eligible for certain benefits after a last day worked, and a right to recall means the employer may still consider the employee attached to the workplace (often still "active" depending on the arrangement). In contrast, when there is no expectation of work to be performed, the relationship is effectively ended for ROE purposes, and the employer generally proceeds with separation reporting and ROE completion based on the interruption of earnings rules.
NEW QUESTION # 72
The authorization for hiring form should contain a checklist to ensure the organization obtains all required information. What is an example of an item that could be on that checklist?
Answer: C
Explanation:
A strong hire-authorization/onboarding checklist ensures payroll and HR collect documents needed to pay the employee accurately and enroll them in required programs. Abenefit enrollment formis a practical, common checklist item because many employers offer benefit plans that require employee elections (for example, health/dental coverage levels, beneficiary information, dependent details, etc.). Indeed's Canadian onboarding guidance explicitly notes employers often collectbenefits enrollmentpaperwork as part of essential new employee forms and onboarding checklists.
By contrast, aT1213(Request to Reduce Tax Deductions at Source) is not routinely required for all hires; it is only used when an employee applies for CRA authorization to reduce tax withheld. A "clearance certificate" is not a standard Canada-wide payroll onboarding requirement for typical employment relationships.
Therefore, "All of the above" is not correct.
Selectingbenefit enrollment formbest matches the purpose of a hiring authorization checklist: ensuring all employment setup steps are completed (pay setup, statutory forms, and benefits enrollment where offered) so payroll deductions and coverage are handled correctly from the start.
NEW QUESTION # 73
......
In accordance with the actual exam, we provide the latest PF1 exam dumps for your practices. With the latest PF1 test questions, you can have a good experience in practicing the test. Moreover, you have no need to worry about the price, we provide free updating for one year and half price for further partnerships, which is really a big sale in this field. After your payment, we will send the updated PF1 Exam to you immediately and if you have any question about updating, please leave us a message.
PF1 Certification Exam Cost: https://www.braindumpsit.com/PF1_real-exam.html
DOWNLOAD the newest BraindumpsIT PF1 PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1QH581IB3ClBYiSzHoDgcQthrcTA5_iSF