Managing time during the WGU Accounting-for-Decision-Makers exam is a challenging task. Most candidates cannot manage their time during the WGU Accounting-for-Decision-Makers exam, leave the questions, and fail. Time management skills can help students gain excellent marks in the Accounting-for-Decision-Makers Exam. WGU Accounting-for-Decision-Makers practice exam on the software helps you identify which kind of WGU Accounting for Decision Makers C213 VAC2 Accounting-for-Decision-Makers questions are more time-consuming, and they would be able to assess their efficiency in answering questions.
| Section | Weight | Objectives |
|---|---|---|
| Budgeting and Decision Making | 10–15% | - Master budget and components
|
| Cost Systems | 20–25% | - Costing methods
|
| Financial Analysis | 45–50% | - Purpose and components of financial statements
|
| Profit Planning | 10–15% | - Cost-volume-profit (CVP) analysis
|
| Controls and Regulations | 10–15% | - Internal control systems and principles
|
>> Pdf Accounting-for-Decision-Makers Free <<
The company is preparing for the test candidates to prepare the Accounting-for-Decision-Makers exam guide professional brand, designed to be the most effective and easiest way to help users through their want to get the test Accounting-for-Decision-Makers certification and obtain the relevant certification. In comparison with similar educational products, our training materials are of superior quality and reasonable price, so our company has become the top enterprise in the international market. Our Accounting-for-Decision-Makers practice materials have been well received by the users, mainly reflected in the following advantages.
NEW QUESTION # 54
A company prepared the following contribution margin income statement for the actual sale of 10,000 shoes:
Sales revenue = $600,000
Variable costs = $400,000
Contribution margin = $200,000
Less fixed costs = $150,000
Net income = $50,000
What would be the forecasted net income for the sale of 14,000 shoes based on the actual results above?
Answer: A
Explanation:
The correct answer is C. $130,000 . A contribution margin income statement separates variable costs from fixed costs , which makes it useful for forecasting profit at different sales levels. OpenStax explains that contribution margin analysis shows how much sales revenue remains after variable costs to cover fixed costs and profit.
First calculate the per-unit amounts based on 10,000 shoes:
Sales per unit = $600,000 / 10,000 = $60
Variable cost per unit = $400,000 / 10,000 = $40
Contribution margin per unit = $20
For 14,000 shoes , total contribution margin would be:
14,000 × $20 = $280,000
Now subtract fixed costs, which stay the same at $150,000 :
Forecasted net income = $280,000 - $150,000 = $130,000
So the company would expect to earn $130,000 if it sells 14,000 shoes. This is exactly why CVP and contribution margin statements are useful for planning: they allow managers to estimate the profit impact of volume changes quickly, as long as selling price, variable cost per unit, and fixed costs remain stable.
Therefore, Option C is correct.
NEW QUESTION # 55
How are activity-based costing systems different from traditional costing systems?
Answer: C
Explanation:
The correct answer is C . Activity-based costing (ABC) is generally more precise than traditional costing when a company makes multiple products that consume overhead resources differently. ABC assigns overhead by identifying activities and using multiple cost drivers that better reflect how products actually use resources. Sources on ABC explain that it improves cost accuracy compared with traditional systems, especially in more complex production environments.
Option A is incorrect because the statement is reversed. Traditional costing often uses a single volume-based driver such as labor hours or machine hours, while ABC commonly uses multiple cost drivers . Option B is incorrect because ABC is usually more time-consuming and expensive to administer, not less. Option D is also incorrect because ABC is especially useful when products are heterogeneous , meaning they differ in the amount and type of overhead resources they consume. Therefore, the key difference is that ABC gives a more precise assignment of overhead costs than traditional costing when multiple products are produced. That makes Option C the correct answer.
NEW QUESTION # 56
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.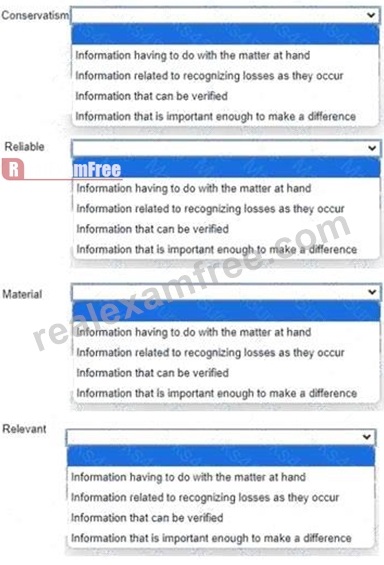
Answer:
Explanation: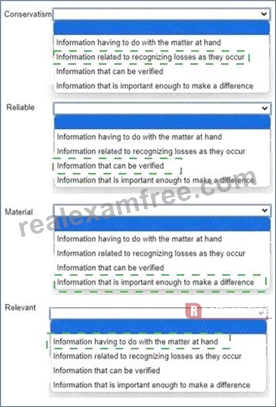
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 57
Which two details can management determine through a cost-volume-profit analysis?
Choose 2 answers.
Answer: A,B
Explanation:
The correct answers are A and B . Cost-volume-profit (CVP) analysis is a forward-looking planning tool used to study how changes in costs , sales volume , and selling price affect contribution margin, break-even point, and target profit. OpenStax describes CVP analysis as one of the most useful tools in managerial accounting for analyzing how changing business situations affect profit.
Option A is correct because CVP helps management estimate how a future change in variable costs or fixed costs would influence profit. Option B is also correct because CVP can determine how many units must be sold to achieve a desired target income or profit level. In contrast, Options C and D focus on past transactions and past tax costs, which are not the primary purpose of CVP analysis. CVP is mainly a planning and decision-making method rather than a historical reporting tool. It helps managers ask "what happens if" questions about future operations, such as what sales volume is needed to earn a target profit or how a change in cost structure would affect margins. Therefore, the correct choices are A and B .
NEW QUESTION # 58
What can be deduced when a company has an asset turnover of 0.95?
Answer: B
Explanation:
The correct answer is A. The company was able to generate $0.95 in sales for each dollar in assets . The asset turnover ratio is calculated as:
Asset turnover = Total sales / Total assets
This ratio measures how efficiently a company uses its assets to produce revenue. If a company has an asset turnover of 0.95 , it means that for every $1.00 invested in assets , the company generated $0.95 in sales during the period.
This ratio is especially useful in comparing operating efficiency across time or between similar companies. A higher asset turnover usually indicates more efficient use of assets in generating sales, while a lower ratio may suggest underused resources or a more asset-intensive business model.
Option B is incorrect because asset turnover does not measure equity generation. Option C is incorrect because it does not compare liabilities to assets. Option D is incorrect because profit per dollar of assets is more closely related to return on assets, not asset turnover. Since the formula directly links sales with assets , the only correct interpretation of a 0.95 asset turnover is $0.95 in sales per $1.00 of assets , which is Option A .
NEW QUESTION # 59
......
Now we can say that with the Accounting-for-Decision-Makers Exam Dumps you will get the updated and verified WGU Accounting-for-Decision-Makers exam practice Test all the time. With the WGU Accounting for Decision Makers C213 VAC2 Accounting-for-Decision-Makers Exam Questions, you will get the opportunity to download the updated and real WGU Accounting for Decision Makers C213 VAC2 Accounting-for-Decision-Makers exam practice questions.
New Accounting-for-Decision-Makers Braindumps Ebook: https://www.realexamfree.com/Accounting-for-Decision-Makers-real-exam-dumps.html