2026 Latest PracticeTorrent LLQP PDF Dumps and LLQP Exam Engine Free Share: https://drive.google.com/open?id=1SqhMh89hHfMlNQ32RBXUCe8sCkuyxcsv
Because our IFSE Institute LLQP practice test is a web-based mock test, there is no need for software installation as it works with all of the popular web browsers, including Internet Explorer, MS Edge, Firefox, Chrome, Opera, and Safari. Your preparation for the LLQP Certification Exam will go more smoothly because our IFSE Institute LLQP online practice exam precisely replicates the environment of the actual exam.
| Certification Vendor: | IFSE Institute |
|---|---|
| Exam Name: | Life License Qualification Program (LLQP) |
| Exam Number: | LLQP |
| Exam Duration: | 75 per module |
| Exam Price: | USD 0 |
| Passing Score: | 60% |
| Exam Format: | Multiple Choice, Scenario-Based |
| Related Certifications: | Accident and Sickness Insurance Licence Life Insurance Agent Licence |
| Real Exam Qty: | 110-140 |
| Certificate Validity Period: | 1 year to apply for licence after first pass |
| Available Languages: | French, English |
| Sample Questions: | IFSE Institute LLQP Sample Questions |
| Exam Way: | Online proctored and in-person testing |
| Pre Condition: | Completion of an approved LLQP certification course and possession of a CIPR number are required before taking the exam. |
| Official Syllabus URL: | https://www.fsrao.ca/licensing/life-and-accident-sickness-agent/life-licence-qualification-program-llqp |
>> Practice LLQP Exam Online <<
If you are sure that you want to pass IFSE Institute certification LLQP exam, then your selecting to purchase the training materials of PracticeTorrent is very cost-effective. Because this is a small investment in exchange for a great harvest. Using PracticeTorrent's test questions and exercises can ensure you pass IFSE Institute Certification LLQP Exam. PracticeTorrent is a website which have very high reputation and specifically provide simulation questions, practice questions and answers for IT professionals to participate in the IFSE Institute certification LLQP exam.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
NEW QUESTION # 13
Emeka, a new insurance agent with Sunrise Insurance, meets with her client, Mosi. After analyzing Mosi's needs, Emeka determines that Mosi's current life insurance coverage with Starlight Insurance is more than sufficient. Nevertheless, she persuades Mosi to cancel his existing coverage and buy a new life insurance policy with Sunrise Insurance. She believes this is a good compromise because Mosi will have the coverage he needs, and the new transaction will pay her a commission. Which of the following offences did Emeka commit?
Answer: B
Explanation:
Twisting involves persuading a client to replace an existing insurance policy with a new one from a different insurer, often to earn a commission, without a clear benefit to the client. Emeka's action of convincing Mosi to cancel his sufficient coverage with Starlight Insurance to purchase a new policy with Sunrise Insurance, primarily for her commission, constitutes twisting. This practice isgenerally considered unethical, as it may not be in the best interest of the client and can lead to unnecessary costs and potential coverage gaps.
Churning, on the other hand, usually involves replacing policies within the same company to generate additional commissions, which does not apply here.
NEW QUESTION # 14
Emery is a healthy wife and mother of two who spends her days caring for her children and volunteering at the local food bank. Emery would like to purchase disability insurance coverage because she is worried about how she would be able to take care of her family if she becomes disabled.
What type of disability policy, if any, is likely to be issued to her?
Answer: D
Explanation:
Emery is a non-income earning individual, as she is a stay-at-home mother and volunteer. Traditional disability insurance policies, likeGuaranteed RenewableorCancellable policies, typically require proof of income and are generally issued to individuals who can demonstrate earned income. However,Non- traditional disability insurance policiesare often designed for individuals without a conventional source of earned income, such as homemakers, who may still wish to secure coverage against the potential loss of the ability to perform daily tasks due to disability.
Non-traditional policies may offer benefits that help cover the costs associated with hiring help or obtaining services that Emery could no longer provide if disabled. These types of policies acknowledge that a disability could impact Emery's ability to care for her family, even though she does not earn a regular income.
Therefore, option C is the best answer, as it aligns with the LLQP guidelines that recognize the suitability of non-traditional disability policies for individuals like Emery who have significant responsibilities but no formal income.
NEW QUESTION # 15
Claudie's mother has been the policyholder and beneficiary of an insurance policy on the life of Claudie since she was five years of age. Claudie is now the mother of a three-month-old boy. Claudie would like for Marc- Andre, her de facto spouse, to be the beneficiary of the policy. What steps need to be taken in order for this to happen?
Answer: A
Explanation:
Comprehensive and Detailed In-Depth Explanation: In life insurance, the policyholder owns the contract and has the authority to change the beneficiary, per the Civil Code of Quebec (Article 2425). Claudie's mother, as the policyholder, must submit a written request to the insurer to designate Marc-Andre as the new beneficiary, making option A correct. Option B is incorrect because the beneficiary (Claudie's mother) has no control over changing the designation-only the policyholder does. Option C is wrong, as the insured (Claudie) has no inherent right to alter the beneficiary unless she is also the policyholder, which she is not. Option D misstates the goal-Claudie wants a beneficiary change, not a policyholder change. The Ethics and Professional Practice manual stresses that advisors must ensure clients understand policy ownership rights and procedures for beneficiary changes.
References: Civil Code of Quebec, Article 2425; Ethics and Professional Practice (Civil Law) Manual, Section on Policy Ownership and Beneficiary Designations.
NEW QUESTION # 16
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
Answer: A
Explanation:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence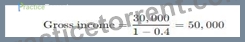
Calculate Required Capital for Income Replacement:
Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence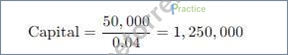
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
NEW QUESTION # 17
Juliette owns a medium-sized business with approximately 100 employees. Three years ago, she set up a small group benefits plan. Her employees, however, are unhappy with the coverages offered under the plan.
Moreover, for tax purposes, the group plan shares the cost of disability premiums with the employees-an expense they do not welcome. What should Juliette's agent tell her?
Answer: C
Explanation:
Comprehensive and Detailed Explanation:
A Private Health Services Plan (PHSP) offers flexible, tax-free benefits (employer-paid premiums are deductible, benefits non-taxable), addressing employee dissatisfaction and tax concerns (Chapter 8:Group Plan Specifics).
Option A: Incorrect; EHT (Employer Health Tax) isn't insurance.
Option B: Correct; PHSP fits needs.
Option C-D: Incorrect; group plan isn't optimal or tax-free for employees.
Reference: LLQP Accident and Sickness Insurance Manual, Chapter 8:Group Plan Specifics.
NEW QUESTION # 18
......
LLQP Actualtest: https://www.practicetorrent.com/LLQP-practice-exam-torrent.html
P.S. Free & New LLQP dumps are available on Google Drive shared by PracticeTorrent: https://drive.google.com/open?id=1SqhMh89hHfMlNQ32RBXUCe8sCkuyxcsv