あらゆる種類の試験を扱う場合、最も重要なことは、効果的にレビューするための科学的な方法を見つけることです。最も専門的な専門家によって編集された当社のAFP-Exam-1練習資料。現在まで、世界中の何万人ものお客様がAFP-Exam-1試験トレントをサポートしています。 AFP-Exam-1学習教材に不慣れな場合は、参考のために無料のデモをダウンロードしてください。一部の未学習の試験の受験者は、AFP-Exam-1練習教材で必需品をすばやく習得できます。したがって、教材は欠かすことのできない要素教材です。
| Section | Objectives |
|---|---|
| Topic 1: Retirement Planning | - Retirement savings vehicles and planning principles |
| Topic 2: Investment Planning | - Investment products and risk-return profiles - Asset allocation and portfolio basics |
| Topic 3: Insurance and Risk Management | - Life and health insurance fundamentals - Risk mitigation strategies in financial planning |
| Topic 4: Financial Planning Foundations | - Ethics and professional standards in financial advising - Financial planning process and client relationship management |
| Topic 5: Taxation Concepts | - Tax-efficient investment strategies - Personal income tax principles |
今の競争が激しい社会にあたり、あなたは努力して所有したいことがあります。IT職員にとって、AFP-Exam-1試験認定書はあなたの実力を証明できる重要なツールです。だから、CSI AFP-Exam-1試験に合格する必要があります。それで、弊社の質高いAFP-Exam-1試験資料を薦めさせてください。
質問 # 55
Sunil and Shashi are married and both age 45. Each is the personal care Power of Attorney (POA) for the other. They have no children. Shashi would like to revise the personal care POA to ensure that it reflects her medical wishes. How should their financial planner advise Shashi to help her achieve her goal?
正解:A
解説:
Shashi already has a personal care power of attorney; her issue is that she wants the document framework to reflect her medical wishes. A living will, advance directive, or health-care directive records instructions about treatment preferences, end-of-life care, and medical decisions if she is unable to communicate. It gives guidance to the appointed attorney for personal care rather than merely naming the decision-maker. Using a last will and testament would not solve the problem because a will operates at death, not during incapacity.
Appointing an alternate attorney may provide backup authority but does not describe Shashi's specific medical wishes. Replacing Sunil with another attorney also changes who decides; it does not document what Shashi wants. The planner should recommend that she speak with legal counsel to ensure the directive is valid under the applicable provincial rules and coordinated with the POA. Study Guide focus: incapacity planning, personal care POA, living wills, and estate planning documents.
質問 # 56
Janet's non-registered account holds the funds listed in the following table: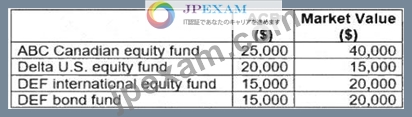
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
正解:B
解説:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
質問 # 57
In which life cycle stage would a financial planner identify his client to be if they have a high mortgage balance and an unstable or lower income, and are willing to take on investment risk because of their longer time horizon?
正解:B
解説:
The accumulation stage is characterized by asset building while major liabilities and career uncertainty may still exist. Clients in this stage often have mortgages, young families or early career responsibilities, and a long time horizon before retirement. Because the investment horizon is long, they may be able to accept more growth exposure, provided cash flow, emergency reserves, and debt servicing are under control. The consolidation stage usually occurs later, when income is stronger, debts are falling, and retirement funding accelerates. Financial independence refers to clients who can maintain lifestyle without employment income.
Gifting generally occurs after core lifetime needs are secure and surplus wealth can be transferred. The scenario states high mortgage balance, unstable or lower income, and willingness to take investment risk due to a long horizon; that is the accumulation phase. Study Guide focus: client life-cycle stages, risk capacity, accumulation planning, mortgage debt, and time horizon. Insurance planning and emergency reserves are usually reviewed alongside investments because human-capital protection is critical in this stage.
質問 # 58
Robert is meeting with his wealth advisor to review options to put a plan in place to save for his children's education. He has a daughter, age seven, and a disabled son, age four Robert would like to maximize his savings towards this goal, ensure the strategy is tax efficient and utilize available grants. Which option is most appropriate for Robert's plan?
正解:B
解説:
A family RESP is the most appropriate education savings structure for Robert's two children. It permits multiple related beneficiaries and provides flexibility if one child does not use all of the education funding.
Contributions can attract available education savings grants, and growth is tax-deferred until paid as educational assistance payments. A group RESP is less flexible and may impose restrictions that are not ideal for a family with different education paths. Individual RESPs can work, but they reduce the ability to shift unused resources between siblings compared with a family plan. An education-purpose trust lacks the RESP grant structure and tax treatment. The disabled son's broader planning may also require RDSP analysis, but that option is not offered and does not replace RESP education funding. The planner should confirm grant limits, contribution limits, beneficiary eligibility, and withdrawal rules. Study Guide focus: RESPs, family plans, education grants, tax-deferred education savings, and beneficiary flexibility.
質問 # 59
Bill was recently declined for a loan application at his financial institution, and he is concerned that a liability has been added to his credit bureau that does not belong to him. He asks his financial planner to review his credit bureau with him to help him identify why he may have been declined. Which area of the credit bureau might his financial planner advise Bill to review?
正解:B
解説:
Bill should review the account history section of the credit bureau. If a liability has been added that does not belong to him, it would normally appear as an account entry showing creditor name, account type, balance, payment status, opening date, and ownership or responsibility. Inquiries show who accessed the credit file, not whether an incorrect liability exists. Public record information may show bankruptcies, judgments, liens, or collections, but the question specifically asks about a liability added to the bureau. The number of previous declines is not the relevant bureau section for identifying a disputed account. The planner should advise Bill to obtain the full credit report, identify unfamiliar accounts, contact the credit bureau and creditor, and dispute inaccurate information in writing. Accurate credit reporting is critical before another loan application. Study Guide focus: credit bureau review, account history, credit disputes, borrowing capacity, and liability management. A documented dispute process is important because unresolved bureau errors can affect pricing, approval, and future borrowing capacity.
質問 # 60
......
私たちは本当にお客様の貴重な意見をAFP-Exam-1試験資料の作りの考慮に入れます。おそらく、君たちは私たちのAFP-Exam-1試験資料について何も知らないかもしれません。でも、私たちのAFP-Exam-1試験資料のデモをダウンロードしてみると、全部わかるようになります。そのデモはAFP-Exam-1試験資料の一部を含めています。
AFP-Exam-1再テスト: https://www.jpexam.com/AFP-Exam-1_exam.html