2026 Latest Prep4sureExam AFP-Exam-1 PDF Dumps and AFP-Exam-1 Exam Engine Free Share: https://drive.google.com/open?id=1e9AeUkiONCNOxrWpSUZVsqKTOFNkOT7x
No matter where you are, we will ensure that you can use our AFP-Exam-1 guide quiz at any time. We have provided you with three versions for your choice: the PDF, Software and APP online. At home, you can use the Software. Outside, you can use the APP version of our AFP-Exam-1 Study Materials. If you like the aroma of paper, you can choose the PDF version. You can carry the printed material with you and write your own notes on it. If you want to know more about them, just free download the demos of our AFP-Exam-1 exam questions.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Retirement Planning | 17% | - Retirement Income Strategies - Pension Plans - Retirement Needs Analysis - Registered Retirement Savings Plans |
| Topic 2: Client Relationship and Practice Management | 6% | - Practice Management - Communication and Advisory Process - Client Discovery |
| Topic 3: Tax Planning | 14% | - Tax Deductions and Credits - Tax-Efficient Strategies - Income Tax Fundamentals - Registered Plans |
| Topic 4: Asset and Liability Management | 11% | - Cash Flow Management - Debt Management - Personal Balance Sheet Analysis - Budgeting |
| Topic 5: Investment Planning | 17% | - Investment Products - Investment Theory - Asset Allocation - Portfolio Construction |
| Topic 6: Risk Management and Insurance | 12% | - Disability and Health Insurance - Life Insurance - Risk Transfer Strategies - Risk Assessment |
| Topic 7: Professional Conduct and Regulatory Compliance | 10% | - Ethics and Professional Standards - Regulatory Requirements - Compliance Responsibilities |
| Topic 8: Estate Planning | 13% | - Estate Transfer Strategies - Wills - Trust and Beneficiary Planning - Powers of Attorney |
>> Pass4sure AFP-Exam-1 Pass Guide <<
Experts at Prep4sureExam have also prepared CSI AFP-Exam-1 practice exam software for your self-assessment. This is especially handy for preparation and revision. You will be provided with an examination environment and you will be presented with actual exam CSI AFP-Exam-1 Exam Questions. This sort of preparation method enhances your knowledge which is crucial to excelling in the actual certification exam.
NEW QUESTION # 66
What information is least important for Harry as a financial planner in his assessment for insurance coverage for his client with respect to estate planning purposes?
Answer: C
Explanation:
Estate insurance analysis focuses on amounts that create liquidity needs at death. Age affects underwriting, premium cost, and life expectancy assumptions. Income may indicate lifestyle replacement needs, support obligations, or survivor dependency. The fair market value of a non-principal residence is directly relevant because accrued capital gains may create a tax liability on deemed disposition at death. Work location, by contrast, has little bearing on estate liquidity unless the scenario adds an occupational risk or employer benefit issue, which it does not. The planner should gather asset values, ownership form, liabilities, beneficiary designations, tax exposure, family obligations, and existing insurance before recommending coverage. In this question, option B is least important because it does not help calculate probate exposure, final tax, debt repayment, or survivor capital requirements. Study Guide focus: estate liquidity, deemed disposition, life insurance needs analysis, taxable assets, and client data collection. The file should therefore emphasize estate value, tax exposure, liquidity, and beneficiary obligations rather than workplace geography.
NEW QUESTION # 67
Henry, age 48, has been working for Bac Inc, which is a federally regulated corporation, for over eight years.
He is looking to retire at age 50 and has decided to take the commuted value of his pension: $450,000, electing to transfer the eligible remainder to his RRSP (Income Tax Act maximum pension benefit transfer value of $210,000). Henry estimates he would need $1,800 (pre-tax every month) from his registered investments to meet his retirement income goal and is looking to maximize his RRSP contribution room.
Assume no inflation, an average tax rate of 15%, an unused RRSP contribution room of $90,000, and a life expectancy to age 90. What would be the required rate of return to meet Henry's goals?
Answer: D
Explanation:
Henry's required rate of return is approximately 6.71%. He is retiring at age 50 and expects to need $1,800 per month before tax from registered investments until age 90, a 40-year income period. Of the $450,000 commuted value, $210,000 can be transferred under the Income Tax Act maximum pension transfer rule, and he has $90,000 of unused RRSP contribution room. That gives $300,000 of registered capital available for the retirement-income objective. Solving the present-value annuity problem for $1,800 monthly withdrawals over
480 months produces a monthly return that annualizes to about 6.71%. Option D is too low to sustain the withdrawals. Options A and B require more return than the calculation supports. The planner should also discuss inflation, locked-in restrictions, taxation, investment risk, and the danger of relying on a single return assumption. Study Guide focus: commuted values, RRSP room, locked-in transfers, annuity math, and retirement income sustainability.
NEW QUESTION # 68
Richard pays periodic spousal support and child support under a written separation agreement. Which statement is generally correct?
Answer: D
Explanation:
Tax treatment depends on the type of support. Periodic spousal support paid under a qualifying written agreement or court order is generally deductible to the payer and taxable to the recipient. Child support is generally not deductible to the payer and not taxable to the recipient. Option B wrongly treats child support like deductible spousal support. Option C confuses payment frequency with tax character; monthly payment does not make child support taxable. Option D is plainly incorrect because spousal support can materially affect after-tax cash flow for both parties. A financial planner should distinguish periodic support from lump- sum settlements, property transfers, arrears, legal fees, and combined agreements because classification changes projections. The planner should also ensure tax assumptions follow the wording of the agreement and should recommend legal or tax advice where facts are unclear. The planning result is measured on after-tax cash flow, not simply the gross support amount. References/topics: support payments, divorce planning, cash flow, tax deductibility.
NEW QUESTION # 69
Consider the following information for a client's portfolio: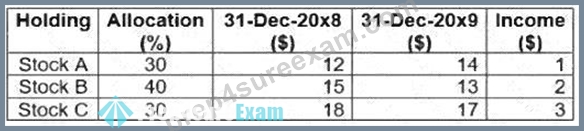
What is the annual rate of return for this portfolio?
Answer: A
Explanation:
The portfolio return must combine price change and income for each holding, then weight each holding by its allocation. Stock A rises from $12 to $14 and pays $1 of income, producing a return of ($14 + $1 - $12) / $12
= 25%. Stock B falls from $15 to $13 but pays $2, producing a 0% total return. Stock C falls from $18 to $17 and pays $3, producing ($17 + $3 - $18) / $18 = 11.11%. Applying the allocation weights gives 30% × 25%, plus 40% × 0%, plus 30% × 11.11%, which is approximately 10.8%. The answer is not based only on market value movement and not on a simple average of the three returns. AFP investment calculations require total return and allocation weighting. Study Guide focus: portfolio return, income return, capital return, weighted averages, and performance measurement. This is why the answer is a weighted total-return figure, not a yield figure or a price-only performance measure.
NEW QUESTION # 70
Priya grants her brother trading authority over her non-registered investment account. Her brother calls the financial planner and asks for Priya's full net worth statement, tax return, and beneficiary information so he can "help with planning." What should the planner do?
Answer: A
Explanation:
Trading authority is limited authority. It normally permits the authorized person to place transactions on the specified account; it does not automatically permit disclosure of all client records, tax documents, beneficiary designations, estate information, or broader financial planning data. The planner must protect confidentiality unless the client provides clear consent or a valid legal authority requires disclosure. Option A overstates the scope of trading authority. Option B still assumes the planner may disclose account details without confirming whether that disclosure is within the authority granted. Option C confuses identity verification with authority; confirming who someone is does not prove that person is entitled to confidential information. The proper response is to explain the limitation, ask Priya to contact the planner directly, and obtain written authorization if she wants her brother involved in broader planning. The file should clearly record what authority exists, what was requested, and what was declined. References/topics: confidentiality, third-party authorization, trading authority, client information protection.
NEW QUESTION # 71
......
Many don't find real Applied Financial Planning Certification Exam 1 (AFP) exam questions and face loss of money and time. Prep4sureExam made an absolute gem of study material which carries actual Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) Exam Questions for the students so that they don't get confused in order to prepare for Applied Financial Planning Certification Exam 1 (AFP) (AFP-Exam-1) exam and pass it with a good score. The AFP-Exam-1 practice test questions are made by examination after consulting with a lot of professionals and receiving positive feedback from them.
Pdf AFP-Exam-1 Free: https://www.prep4sureexam.com/AFP-Exam-1-dumps-torrent.html
2026 Latest Prep4sureExam AFP-Exam-1 PDF Dumps and AFP-Exam-1 Exam Engine Free Share: https://drive.google.com/open?id=1e9AeUkiONCNOxrWpSUZVsqKTOFNkOT7x