P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by Real4Prep: https://drive.google.com/open?id=13Cg--WPrCFB_F951fY3XQAZ_aeDjTquG
Passing National Payroll Institute actual test will make you stand out from other people and you will have access to the big companies. But it is not an easy thing for you to prepare PF1 practice test. The best way for you is choosing a training tool to practice PF1 Study Materials. If you have no idea about the training tools, Real4Prep will be your best partner in the way of passing the IT certification.
| Section | Objectives |
|---|---|
| Payroll Fundamentals and Compliance Framework | - Payroll legislation and regulatory bodies
|
| Payroll Records and Compliance Reporting | - Recordkeeping requirements
|
| Earnings, Deductions, and Taxation | - Types of earnings
|
If you want to get PF1 certification and get hired immediately, you’ve come to the right place. Real4Prep offers you the best exam dump for PF1 certification. With the guidance of no less than seasoned PF1 professionals, we have formulated updated actual questions for PF1 Certified exams, over the years. To keep our questions up to date, we constantly review and revise them to be at par with the latest PF1 syllabus for PF1 certification.
NEW QUESTION # 54
An organization pays the premiums for a sickness or accident plan for their president only. This would be considered:
Answer: D
Explanation:
Because the plan is for the president only, it is a non-group insurance plan (a plan offered to an individual employee). The CRA states that when an employer pays premiums or makes contributions to a non-group insurance plan, the amounts paid are a taxable benefit. The CRA explicitly includes sickness or accident, disability, and income maintenance plans in this non-group category.
This benefit is generally treated as a non-cash taxable benefit because the employer is paying the premium directly to the insurer (the employee receives the coverage, not cash). CRA guidance distinguishes cash benefits (paid as money, reimbursements, or allowances) from benefits provided in a manner other than cash.
Payroll must therefore include the value of the employer-paid premium in the employee's taxable income and report it on the appropriate slip (commonly T4 code 40 for current employees, as noted in CRA instructions for insurance premiums).
NEW QUESTION # 55
Tanya submitted a letter of resignation to her employer on April 2 of the current year advising that she would be resigning her position effective April 27 for the pay period ending April 28. What date will appear in Block
11 of Tanya's Record of Employment?
Answer: A
Explanation:
Block 11 on the ROE is "Last day for which paid." Service Canada instructs employers to enter the last day for which the employee received insurable earnings. This date usually coincides with the last day of work, unless the employee continues to receive insurable earnings after the last day worked (for example, paid leave like vacation/sick leave or salary continuance).
In Tanya's case, she gave notice on April 2, but her resignation is effective April 27. There's no information indicating paid leave after April 27 or salary continuance. So Block 11 should be April 27 (the last day she worked/received insurable earnings).
The question also mentions the pay period ending April 28-that date belongs in Block 12 (Final pay period ending date), which is the end date of the final pay period that includes the Block 11 date, and is often different from Block 11.
NEW QUESTION # 56
When would a Record of Employment be issued for an employee paid mainly by commission?
Answer: B
Explanation:
Commission employees have a specific ROE rule. Service Canada's ROE Guide explains that for employees whose earnings consist mainly of commissions, an interruption of earnings occurs only when the employment contract is terminated-unless the employee stops working due to specified EI-related reasons such as illness
/injury/quarantine, maternity/pregnancy, parental leave, or compassionate care/family caregiver leaves.
This means the usual 7-day rule (7 consecutive days with no work and no insurable earnings) generally does not trigger an interruption of earnings for mainly-commission employees as long as the contract continues. In other words, if the employee stops working for reasons like vacation or a leave of absence but remains under contract, Service Canada indicates there is no interruption of earnings and therefore no ROE is issued just because of time without commissions/work.
So the correct choice is when the employment relationship/contract is terminated (option C).
NEW QUESTION # 57
Ursula is 17 years old, works in Quebec and earns $750.00 weekly. Ursula pays weekly union dues of $18.00 along with a special weekly union assessment of $10.00 for construction of a new union hall for its members.
Ursula also has registered pension plan (RPP) contributions of $20.00 deducted from each pay. Calculate Ursula's net federal taxable income.
Answer:
Explanation:
$712.00
Explanation:
For payroll income tax purposes, net taxable income starts with the employee's gross taxable income and then subtracts only those deductions that are deductible for income tax and can be recognized at source. CRA payroll guidance shows this approach by subtracting items such as RPP contributions and union dues when determining net taxable income for calculating income tax deductions.
Gross taxable income (weekly): $750.00.
RPP contributions are deductible (the amounts reported from box 20 of the T4 are generally deductible).
Regular union dues are deductible; however, the CRA states that deductible annual union/professional dues do not include special assessments or charges for anything other than ordinary operating costs. A levy specifically for constructing a new union hall is a special assessment, so it is not deductible as union dues.
So the deductions that reduce federal taxable income here are: $18.00 (union dues) + $20.00 (RPP) = $38.00.
Net federal taxable income = $750.00 # $38.00 = $712.00.
NEW QUESTION # 58
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.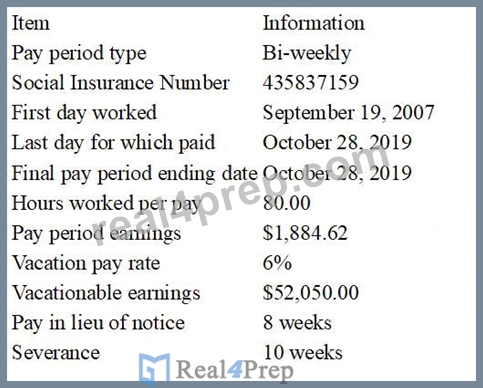
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)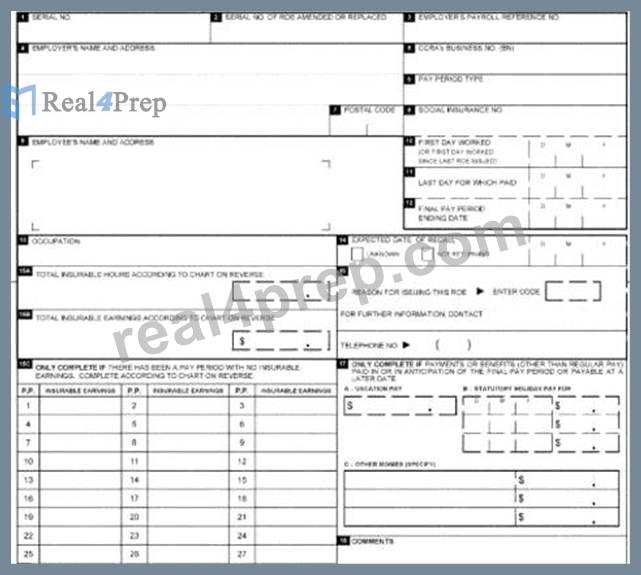
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 59
......
As a professional dumps vendors, we provide the comprehensive PF1 pass review that is the best helper for clearing PF1 actual test, and getting the professional certification quickly. It is a best choice to improve your professional skills and ability to face the challenge of PF1 Practice Exam with our online training. We have helped thousands of candidates to get succeed in their career by using our PF1 study guide.
PF1 Latest Exam Dumps: https://www.real4prep.com/PF1-exam.html
P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by Real4Prep: https://drive.google.com/open?id=13Cg--WPrCFB_F951fY3XQAZ_aeDjTquG