2026 Latest DumpsFree Accounting-for-Decision-Makers PDF Dumps and Accounting-for-Decision-Makers Exam Engine Free Share: https://drive.google.com/open?id=1RRrTHZuYKbQVkBWds5Q_Vbsz6rsyDqKg
It can be difficult to prepare for the WGU Accounting-for-Decision-Makers exam successfully, but with actual and updated WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) exam questions, it can be much simpler. The difference between successful and failed Accounting-for-Decision-Makers Certification Exam attempts can be determined by studying with real Accounting-for-Decision-Makers exam questions.
| Section | Objectives |
|---|---|
| Decision Making and Performance Evaluation | - Capital budgeting techniques (NPV, IRR, Payback Period) - Balanced Scorecard concepts - Relevant costs for decision making - Make-or-buy and special order decisions - Responsibility accounting and performance metrics |
| Managerial Accounting Concepts | - Contribution margin and break-even analysis - Cost-Volume-Profit (CVP) analysis - Job order and process costing - Cost classification and behavior (fixed, variable, mixed costs) |
| Budgeting and Planning | - Master budget components - Financial budgets (cash budget, budgeted income statement, budgeted balance sheet) - Operating budgets (sales, production, direct materials, direct labor, overhead) - Variance analysis |
| Financial Accounting Fundamentals | - Accrual vs. cash basis accounting - Preparing financial statements (Income Statement, Balance Sheet, Statement of Cash Flows) - Understanding the accounting cycle - Recording transactions and adjusting entries |
| Financial Statement Analysis | - Interpreting financial data for decision-making purposes - Horizontal and vertical analysis - Ratio analysis (liquidity, profitability, solvency, efficiency ratios) |
>> Exam Accounting-for-Decision-Makers Question <<
The latest technologies have been applied to our Accounting-for-Decision-Makers actual exam as well since we are at the most leading position in this field. You can get a complete new and pleasant study experience with our Accounting-for-Decision-Makers study materials. Besides, you have varied choices for there are three versions of our Accounting-for-Decision-Makers practice materials. At the same time, you are bound to pass the exam and get your desired certification for the validity and accuracy of our Accounting-for-Decision-Makers training guide.
NEW QUESTION # 65
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.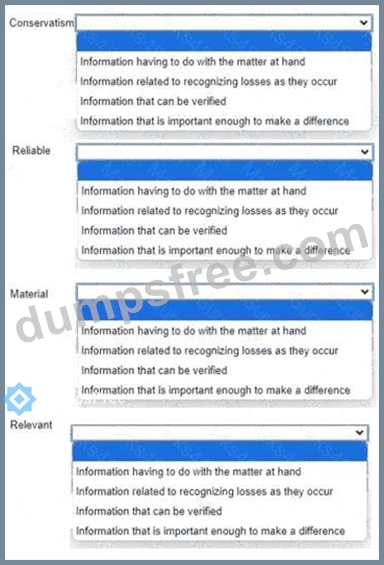
Answer:
Explanation: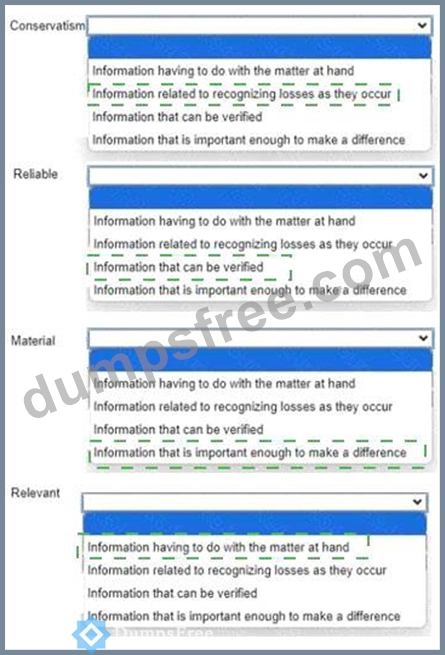
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 66
A company plans to purchase inventory for the second half of a year as follows:
July = $100,000
August = $75,000
September = $225,000
October = $125,000
November = $250,000
December = $30,000
The company usually pays 50% of inventory purchases in the month of purchase, 35% in the following month, and 15% in the second month.
What are the forecasted October cash payments based on this information?
Answer: C
Explanation:
The correct answer is D. $152,500 . To find October cash payments , include the portions of purchases paid in October from three different months:
* 15% of August purchases
* 35% of September purchases
* 50% of October purchases
Now calculate each amount:
15% of August ($75,000) = $11,250
35% of September ($225,000) = $78,750
50% of October ($125,000) = $62,500
Now add them:
$11,250 + $78,750 + $62,500 = $152,500
This is the total forecasted cash payment for October under the company's payment pattern. Budgeted cash disbursement questions often require tracking the timing of payments across multiple months, not just the current month's purchases.
Option B includes only 50% of October purchases. Option C includes only 35% of September purchases.
Option A includes only part of the earlier-month carryover. Since October cash payments must include all three applicable portions, the correct total is $152,500 , making Option D the right answer.
NEW QUESTION # 67
Which two details can management determine through a cost-volume-profit analysis?
Choose 2 answers.
Answer: A,B
Explanation:
The correct answers are A and B . Cost-volume-profit (CVP) analysis is a forward-looking planning tool used to study how changes in costs , sales volume , and selling price affect contribution margin, break-even point, and target profit. OpenStax describes CVP analysis as one of the most useful tools in managerial accounting for analyzing how changing business situations affect profit.
Option A is correct because CVP helps management estimate how a future change in variable costs or fixed costs would influence profit. Option B is also correct because CVP can determine how many units must be sold to achieve a desired target income or profit level. In contrast, Options C and D focus on past transactions and past tax costs, which are not the primary purpose of CVP analysis. CVP is mainly a planning and decision-making method rather than a historical reporting tool. It helps managers ask "what happens if" questions about future operations, such as what sales volume is needed to earn a target profit or how a change in cost structure would affect margins. Therefore, the correct choices are A and B .
NEW QUESTION # 68
What are the costs associated with two or more business units called?
Answer: A
Explanation:
The correct answer is B. Indirect costs . Indirect costs are costs that cannot be economically traced to a single specific cost object, department, product, or business unit because they support multiple activities or units at the same time . Sources defining indirect costs explain that these costs are involved in more than one activity and therefore must often be allocated rather than directly assigned.
Option A is incorrect because variable costs are defined by behavior relative to activity level, not by whether they relate to more than one business unit. Option C, direct costs , are the opposite of indirect costs because they can be traced specifically to one cost object. Option D, product costs , refer to costs attached to manufacturing a product, such as direct materials, direct labor, and manufacturing overhead, and do not necessarily imply multiple business units. In cost accounting, when a cost supports shared operations and cannot be directly attributed to just one unit, it is treated as an indirect cost . Therefore, Option B is the correct answer.
NEW QUESTION # 69
What is the impact on costs as sales volume decreases?
Answer: D
Explanation:
The correct answer is C. Total variable costs will decrease in direct proportion . Variable costs change in total as activity or sales volume changes. When sales volume decreases, total variable costs also decrease proportionally because fewer units are produced or sold. Multiple accounting references explain that total variable cost rises and falls with the level of activity, while the variable cost per unit remains constant within the relevant range.
Option A is the opposite of what happens when volume falls. Options B and D are incorrect because total fixed costs generally remain unchanged within the relevant range regardless of short-term changes in sales volume. OpenStax notes that fixed costs are present regardless of production or sales levels, while variable costs occur only as items or services are produced and sold.
This distinction is central to cost behavior analysis and profit planning. As volume declines, total variable costs go down in direct proportion, but total fixed costs do not normally move with sales in the short run.
Therefore, the correct answer is Option C .
NEW QUESTION # 70
......
Are you preparing for taking the WGU Accounting for Decision Makers C213 VAC2 (Accounting-for-Decision-Makers) certification exam? We understand that passing the Accounting-for-Decision-Makers exam with ease is your goal. However, many people struggle because they rely on the wrong study materials. That's why it's crucial to prepare for the Accounting-for-Decision-Makers Exam using the right Accounting-for-Decision-Makers Exam Questions learning material. Look no further than DumpsFree, where we take responsibility for providing accurate and reliable WGU Accounting-for-Decision-Makers questions prepared by our team of experts.
New Accounting-for-Decision-Makers Test Objectives: https://www.dumpsfree.com/Accounting-for-Decision-Makers-valid-exam.html
DOWNLOAD the newest DumpsFree Accounting-for-Decision-Makers PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1RRrTHZuYKbQVkBWds5Q_Vbsz6rsyDqKg