DOWNLOAD the newest FreeCram LLQP PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=1RW5jC-Dqg3odRYAp7PXR1gpo0dPLdhIp
While Life License Qualification Program (LLQP) (LLQP) exam preparing for the Life License Qualification Program (LLQP) (LLQP) exam, candidates have to pay extra money when IFSE Institute introduces new changes. With FreeCram you can save money in this scenario as up to 365 days of free updates are available. You can also download a free demo to understand everything about FreeCram LLQP Exam Material before buying. While there are many LLQP exam question preparation guides available online, it's crucial to be vigilant while making purchases due to the prevalence of online scams. FreeCram offers IFSE Institute LLQP exam questions for the best exam preparation experience.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
In order to meet all demands of all customers, our company has employed a lot of excellent experts and professors in the field to design and compile the LLQP test dump with a high quality. It has been a generally accepted fact that the LLQP exam reference guide from our company are more useful and helpful for all people who want to pass exam and gain the related exam. We believe this resulted from our constant practice, hard work and our strong team spirit. With the high class operation system, the LLQP study question from our company has won the common recognition from a lot of international customers for us. If you decide to buy our LLQP test dump, we can assure you that you will pass exam in the near future.
NEW QUESTION # 289
Financial security advisor Juliette meets Pierre during a business meeting. Pierre gives her the name of a prospect, one of his friends. Juliette wants to start by contacting the prospect by email, then plans to follow up with a phone call to set up an appointment. Why should Juliette cease to proceed in this manner with her prospect?
Answer: D
Explanation:
Comprehensive and Detailed In-Depth Explanation: Canada's Anti-Spam Legislation (CASL) governs unsolicited electronic communications, including emails for commercial purposes (Sections 6-8). Contrary to option A, CASL does not prohibit all email solicitation; it allows it withprior consent (express or implied) or under specific exemptions (e.g., existing business relationships). Juliette has no prior relationship with the prospect, and Pierre's referral does not constitute implied consent under CASL, as consent must come from the recipient (Section 10). Option B is correct because Juliette must obtain the prospect's consent before sending an unsolicited email, aligning with CASL's opt-in requirement. Option C is incorrect, as Pierre has no legal obligation to facilitate the contact, though it might be courteous. Option D is impractical and not required by law. The Ethics and Professional Practice manual reinforces that advisors must respect privacy laws and obtain consent before initiating contact, making Juliette's proposed action non-compliant without prior approval.
References: Canada's Anti-Spam Legislation, Sections 6-10; Ethics and Professional Practice (Civil Law) Manual, Section on Privacy and Consent.
NEW QUESTION # 290
Emma, an employee at MagicLand, is part of the company's group registered retirement savings plan (RRSP).
During her tenure, she accumulated over $70,000 in the plan and all of her contributions are invested in segregated funds. She meets with Jun to invest in an individual segregated fund. Jun tells her that there are some differences between group and individual segregated funds.
How are Emma's group segregated funds DIFFERENT from an individual segregated fund?
Answer: A
Explanation:
Group segregated funds typically have lower Management Expense Ratios (MERs) than individual segregated funds because group plans benefit from economies of scale and pooled investment options. LLQP highlights that group plans often have reduced fees compared to individual plans due to collective investment and reduced administrative costs.
Options A and B are incorrect as group plans typically feature lower costs and don't often charge switching fees. Option C is incorrect as individual segregated funds typically have more flexible death benefit guarantee options, not special rates in group plans.
NEW QUESTION # 291
Jasper is the sole breadwinner in his family. His wife Stephanie has chosen to dedicate all of her time to raising their 3 young children. Luckily, Jasper earns a monthly after-tax income of $25,000 working as a family doctor in the local clinic. Jasper meets with his insurance agent Odda to purchase a life insurance policy that will ensure his family will be able to continue to enjoy their current lifestyle in the event of his death. If his average tax rate is 40% and theinvestment return is 4%, how much life insurance should Jasper purchase based on the income replacement approach?
Answer: B
Explanation:
The income replacement approach calculates the amount of life insurance needed to replace Jasper'safter-tax income for his dependents over a given period, accounting for an investment return. To maintain the family's current lifestyle, we need to determine the capital required to generate a monthly after-tax income of $25,000.
Calculate the Annual Income Needed:Monthly income required: $25,000Annual income required: $25,000 ×
12 = $300,000
Adjust for Tax:Since Jasper's income needs to be replaced at a pre-tax level with a tax rate of 40%, his gross income requirement is calculated as follows:
A close-up of a math Description automatically generated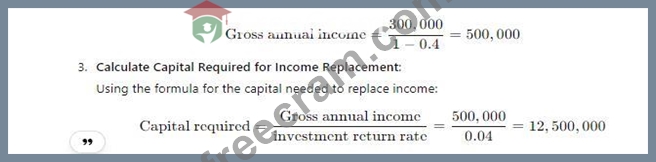
Thus, Jasper needs a life insurance policy worth$12,500,000to replace his income, allowing his family to maintain their lifestyle with a 4% investment return. This calculation aligns with LLQP principles, ensuring that the income replacement fully addresses both current lifestyle needs and tax implications.
NEW QUESTION # 292
(Matthew, 40 years old, is leaving his employer (XYZ Corp) and has $100,000 in a group RRSP.
What should Shawn, the advisor, do?)
Answer: D
Explanation:
Upon termination of employment, employees cantransfer group RRSP funds to an individual RRSPto maintain tax-deferred growth without triggering a taxable event.
Exact Extract:
"Upon leaving employment, a member may transfer their group RRSP assets to an individual RRSP to maintain tax deferral." (Reference:Segfunds-E313-2020-12-7ED, Chapter 1.3.11.2 Group Plans#45:5†Segfunds-E313-2020-12-7ED.
pdf**)
NEW QUESTION # 293
Life insurance agent Travis is preparing to meet with a new client. Over the phone, the client mentioned having about $3,000 that he intends to invest in a segregated fund within his TFSA. Travis and the client have not interacted much previously, so he expects there will be some discussion before a suitable product is selected. Still, Travis believes it is likely the client will end up signing an application form today.
Besides the application form, which of the following documents must Travis bring to ensure that the requirements for opening the account are met?
* A Pre-Authorized Contribution (PAC) form
* An information folder
* A third-party determination form
* The Fund Facts
* Annual audited financial statements for the funds
Answer: A
Explanation:
According to the LLQP Segregated Funds and Annuities curriculum and regulatory requirements governing insurance-based investments, certain documents must be provided or completed at the time a segregated fund contract is sold. These requirements are designed to ensure client disclosure, informed consent, and compliance with anti-money laundering (AML) and consumer protection rules.
First, an information folder is mandatory. The LLQP study guide explains that insurers must provide clients with an information folder before or at the time the contract is issued. This folder outlines the nature of segregated funds as insurance contracts, explains guarantees, fees, risks, and the client's right of rescission.
Without this document, the disclosure requirement is not met.
Second, Fund Facts (also referred to in insurance as Fund Facts-like disclosure documents) must be provided for each segregated fund selected. These documents summarize key information such as investment objectives, historical performance, fees, and risks in a standardized format. The LLQP curriculum emphasizes that Fund Facts must be delivered before or at the point of sale, even if the final fund selection occurs during the meeting.
Third, a third-party determination form is required under AML legislation whenever there is a possibility that someone other than the client may be contributing funds or exercising control. Since the client is investing a lump sum and Travis has limited prior relationship with him, the third-party determination form must be completed to confirm whether the funds belong solely to the client or to someone else.
The other documents are not mandatory in this scenario. A Pre-Authorized Contribution (PAC) form is only required if the client chooses to set up automatic ongoing contributions, which has not been indicated. Annual audited financial statements are publicly available but do not have to be physically provided at the time of sale.
Therefore, based strictly on LLQP Segregated Funds and Annuities regulatory and disclosure requirements, the correct answer is Option C: 2, 3, and 4 only.
NEW QUESTION # 294
......
The IFSE Institute LLQP exam PDF is the collection of real, valid, and updated IFSE Institute LLQP practice questions. The IFSE Institute LLQP PDF dumps file works with all smart devices. You can use the LLQP PDF Questions on your tablet, smartphone, or laptop and start LLQP exam preparation anytime and anywhere.
Top LLQP Questions: https://www.freecram.com/IFSE-Institute-certification/LLQP-exam-dumps.html
P.S. Free & New LLQP dumps are available on Google Drive shared by FreeCram: https://drive.google.com/open?id=1RW5jC-Dqg3odRYAp7PXR1gpo0dPLdhIp