Außerdem sind jetzt einige Teile dieser ITZert IFC Prüfungsfragen kostenlos erhältlich: https://drive.google.com/open?id=1C4rf9cqYClnaGiHoNoVo9RPugEXu40-L
Haben Sie CISI IFC Dumps von ITZert benutzt? Diese Dumps beinhalten die aktualisierten Prüfungsfragen, die auch alle mögliche Prüfungsfragen in der aktuellen Prüfung vorhanden sind. Es kann Ihnen garantieren, nur einmal die CISI IFC Prüfung zu bestehen. Diese Dumps kann Ihnen helfen, unglaubliche Ergebnisse zu bekommen. Wenn Sie in der CISI IFC Prüfung durchgefallen sind, geben wir Ihnen voll Geld zurück. Deshalb müssen Sie sorglos diese Dumps benutzen. Sie können den Erfolg erreichen, wenn Sie die Prüfungsunterlagen von ITZert benutzen.
| Thema | Einzelheiten |
|---|---|
| Thema 1 |
|
| Thema 2 |
|
| Thema 3 |
|
| Thema 4 |
|
| Thema 5 |
|
| Thema 6 |
|
Die neuesten Schulungsunterlagen zur CISI IFC (Investment Funds in Canada (IFC) Exam) Zertifizierungsprüfung von ITZert sind von den Expertenteams bearbeitet, die vielen beim Verwirklichen ihres Traums verhelfen. In der konkurrenzfähigen Gesellschaft muss man die Fachleute seine eigenen Kenntinisse und Technikniveau unter Beweis stellen, um seine Position zu verstärken. Durch die CISI IFC Zertifizierungsprüfung kann man seine Fähigkeiten beweisen. Mit dem CISI IFC Zertifikat werden große Veränderungen in Ihrer Arbeit stattfinden. Ihr Gehalt wird erhöht und Sie werden sicher befördert.
295. Frage
Saheed is a retiree who is considering splitting his pension income with his wife, Minu.
Which of the following outcomes may occur if he shares his pension benefits?
Antwort: D
Begründung:
Whether the couple saves on income tax will be dependent on Minu's marginal tax rate. Pension income splitting is a tax planning strategy that allows a spouse or common-law partner who receives eligible pension income to allocate up to 50% of that income to their spouse or common-law partner1. This may result in tax savings if the transferring spouse or common-law partner is in a higher tax bracket than the receiving spouse or common-law partner1. The tax savings depend on the difference between the marginal tax rates of the spouses or common-law partners1. The other statements are incorrect. Minu will not be exposed to a pension adjustment (PA) if she receives income from Saheed's pension. A PA is a measure of the value of benefits accrued in a registered pension plan or deferred profit sharing plan during a calendar year2. It reduces the RRSP contribution room of the plan member, not the spouse or common-law partner who receives part of their pensionincome2. Pension income splitting is not a form of tax evasion and is not illegal based on income tax legislation. It is a legitimate way to reduce taxable income and taxes payable by shifting income from a higher-income spouse or common-law partner to a lower-income spouse or common-law partner1. Pension income splitting may change the total amount of income taxes paid by the couple, depending on their marginal tax rates. If the transferring spouse or common-law partner is in a higher tax bracket than the receiving spouse or common-law partner, pension income splitting may lower their combined taxes payable1. However, if they are in the same tax bracket, pension incomesplitting may not have any effect on their taxes payable1. References: Pension income splitting, Pension adjustment
296. Frage
What type of fee does a mutual fund sponsor often reduce the longer an investor holds a back-end load fund?
Antwort: B
Begründung:
Back-end load funds often have a decreasing redemption fee (deferred sales charge) schedule, which reduces the longer the investor holds the fund. The feedback from the document states:
"Fund sponsors use a decreasing redemption fee (deferred sales charges) schedule to recover their costs from investors who opt out of the fund early. In most cases, redemption fees on a back-end load fund decrease the longer the investor holds the fund." Reference: Chapter 16 - Mutual Fund Fees and ServicesLearning Domain: Evaluating and Selecting Mutual Funds
297. Frage
One of your clients, Fernando, is approaching 71 years of age and has a few questions regarding life income funds (LIFs).
Which of the following statements about LIFs is TRUE?
Antwort: C
Begründung:
A life income fund (LIF) is a type of registered retirement income fund (RRIF) that can be used to hold locked-in pension funds as well as other assets for an eventual payout as retirement income. A LIF cannot be withdrawn in a lump sum and has minimum and maximum withdrawal amounts each year. A LIF can only be funded by transferring money from a locked-in retirement account (LIRA) or another LIF. Therefore, D is the correct answer. References: Life Income Fund (LIF): Definition and How Withdrawals Work - Investopedia, Retraite Quebec - Characteristics of an LIF
298. Frage
The following chart outlines data for various fund managers: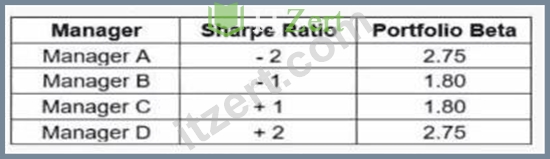
Which manager likely has the highest return for a given level of risk?
Antwort: A
Begründung:
The correct answer is C. Manager D, because the Sharpe ratio is the primary measure used to evaluate risk- adjusted return, which is return earned per unit of total risk. The Investment Funds in Canada curriculum defines the Sharpe ratio as a tool that "measures how much excess return a portfolio generates relative to the risk taken." A higher Sharpe ratio indicates superior risk-adjusted performance.
Manager D has the highest Sharpe ratio (+2) among all managers listed, meaning this manager generated the greatest excess return for each unit of risk, regardless of the portfolio's beta. Although Manager D has a higher beta (2.75), beta measures systematic market risk, not total volatility. The Sharpe ratio already accounts for total risk (standard deviation), making it the preferred comparison metric when the question asks for return for a given level of risk.
Manager C has a positive Sharpe ratio (+1) but lower than Manager D, indicating inferior risk-adjusted performance. Managers A and B both have negative Sharpe ratios, which the CIFC text explains means the portfolio underperformed the risk-free rate, making them clearly inferior choices.
The CIFC curriculum stresses that when comparing managers across different risk profiles, "the Sharpe ratio is the most appropriate measure." Since Manager D delivers the highest risk-adjusted return, Option C is the correct and fully CIFC-verified answer.
299. Frage
Which statement best describes one of the main differences between short and long transactions?
Antwort: D
Begründung:
Long transactions involve buying a security with the expectation that its price will increase, while short transactions involve borrowing and selling a security with the hope of buying it back at a lower price. The feedback from the document states:
"Short transactions are a common feature of the capital markets, although not as common as long transactions
- the transactions taken by investors who anticipate a price increase in the security. Investors who short sell stocks must first borrow the shares. They must also declare their short transactions." Reference: Chapter 7 - Types of Investment Products and How They Are TradedLearning Domain:
Understanding Investment Products and Portfolios
300. Frage
......
Viele IT-Fachleute wollen CISI IFC Zertifikate erhalten. Die IT-Zertifikate werden Ihnen helfen, in der IT-Branche befördert zu werden. Das CISI IFC Zertifikat ist ein beliebtes unter den vielen Zertifikaten. Obwohl es nicht so leicht ist, die CISI IFC Zertifizierungsprüfung zu bestehen, gibt es doch Methoden. Sie können viel Zeit und Energie für die Prüfung benutzen, um Ihr Know-How zu konsolidieren, oder an den effizienten Kursen teilnehmen. Die speziellen Simulationsprüfungen von ITZert, die Ihnen viel Zeit und Energie ersparen und Ihr Ziel erreichen können, ist sehr effizient. ITZert ist eine gute Wahl für Sie.
IFC Prüfungs: https://www.itzert.com/IFC_valid-braindumps.html
Übrigens, Sie können die vollständige Version der ITZert IFC Prüfungsfragen aus dem Cloud-Speicher herunterladen: https://drive.google.com/open?id=1C4rf9cqYClnaGiHoNoVo9RPugEXu40-L