P.S. Free & New LLQP dumps are available on Google Drive shared by ActualPDF: https://drive.google.com/open?id=1pXH3Nmyye0BP8YsqEf_kwjNvtDk9IoFg
We are now in a fast-paced era, and for this we have no right to choose. Just as a proverb says "Time is money." This is the reason why we must value time. That is to say, we should make full use of our time to do useful things. As examinee whose want to pass the LLQP, you shouldn’t waste your time on some useless books or materials. Our LLQP Materials are tool that can not only to help you save a lot of time, but also help you pass the LLQP exam. In this way, you can much time to complete your other goals and improve yourself better. What a rare opportunity it is! Never miss it because of your hesitation.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
>> LLQP Certification Materials <<
Confronting a tie-up during your review of the exam? Feeling anxious and confused to choose the perfect LLQP Latest Dumps to pass it smoothly? We understand your situation of susceptibility about the exam, and our LLQP test guide can offer timely help on your issues right here right now. Without tawdry points of knowledge to remember, our experts systematize all knowledge for your reference. You can download our free demos and get to know synoptic outline before buying.
NEW QUESTION # 70
Rowan works for a construction company that employs 40 employees. The company is newly established, and the owners have yet to implement a group insurance policy. Rowan falls off the side of a building and breaks his collar bone. The doctor informs him that he will be unable to work for five months.
Who will pay him disability benefits while he is recuperating?
Answer: B
Explanation:
In this scenario, Rowan, an employee of a construction company, suffers an injury while on the job. Since the injury occurred in the workplace, he would be eligible for benefits under Workers' Compensation. Workers' Compensation is designed to cover employees who suffer work-related injuries or illnesses, providing them with benefits that include coverage for medical expenses and income replacement during their period of disability.
As the accident happened while Rowan was performing work duties, Workers' Compensation will likely cover his wage loss for the duration he is unable to work due to the injury. Employment Insurance (EI) would not be applicable here, as EI sickness benefits are intended for non-work-related illnesses or injuries. The Canada Pension Plan (CPP) also would not apply, as it provideslong-term disability benefits primarily for severe and prolonged disabilities that prevent individuals from working in any capacity. Therefore, option D is the correct answer, as Workers' Compensation is specifically designed for cases like Rowan's.
NEW QUESTION # 71
Danny purchases a $1,000,000 whole life insurance policy. He names his three daughters, Donna-Joe, Stephanie, and Michelle, as revocable beneficiaries with each receiving one-third of the death benefit.
If Michelle predeceases Danny, and Danny did not have a chance to modify his beneficiary designation, how will Danny's death benefit be paid out?
Answer: A
Explanation:
When a beneficiary predeceases the policyholder and no alternate or contingent beneficiary has been named, the portion allocated to the deceased beneficiary is typically redistributed among the surviving beneficiaries.
Since Michelle was named as a revocable beneficiary and predeceased Danny, her one-third share will be divided equally between the remaining two beneficiaries, Donna-Joe and Stephanie.
Thus, Donna-Joe and Stephanie will each receive half of the total death benefit ($500,000 each), as per LLQP guidelines which state that a predeceased beneficiary's share is typically redistributed among surviving beneficiaries unless otherwise specified.
NEW QUESTION # 72
Juliette owns a medium-sized business with approximately 100 employees. Three years ago, she set up a small group benefits plan. Her employees, however, are unhappy with the coverages offered under the plan.
Moreover, for tax purposes, the group plan shares the cost of disability premiums with the employees-an expense they do not welcome. What should Juliette's agent tell her?
Answer: B
Explanation:
Comprehensive and Detailed Explanation:
A Private Health Services Plan (PHSP) offers flexible, tax-free benefits (employer-paid premiums are deductible, benefits non-taxable), addressing employee dissatisfaction and tax concerns (Chapter 8:Group Plan Specifics).
Option A: Incorrect; EHT (Employer Health Tax) isn't insurance.
Option B: Correct; PHSP fits needs.
Option C-D: Incorrect; group plan isn't optimal or tax-free for employees.
Reference: LLQP Accident and Sickness Insurance Manual, Chapter 8:Group Plan Specifics.
NEW QUESTION # 73
Irwin recently retired after thirty years of service with a trucking company. He has a lump sum of money in a LIRA from a prior employer that he wishes to use to purchase an annuity to cover the costs of his personal health insurance once his group coverage runs out in four months' time, when he turns 65. Although he appreciates the reduced risk an annuity provides, he would like to see the payments increase gradually over time, because he is sure the rates on his private health coverage will steadily rise in the years to come.
What type of annuity would best meet Irwin's needs?
Answer: D
Explanation:
According to the LLQP Segregated Funds and Annuities curriculum, selecting an appropriate annuity requires matching the source of funds, risk tolerance, and income objectives. In Irwin's case, several key facts clearly guide the recommendation.
First, Irwin's funds are held in a LIRA, which is a registered, locked-in retirement account. Under LLQP and pension legislation principles, funds from a LIRA must be used to purchase a registered annuity (or transferred to another registered retirement income vehicle). This immediately eliminates any non-registered annuity option, making Option B incorrect.
Second, Irwin wants stable, low-risk income, which is a core feature of traditional life annuities. Although variable annuities can offer income that fluctuates based on investment performance, they do not provide predictable increases and expose the annuitant to market risk. Since Irwin specifically appreciates the reduced risk of an annuity, a variable income annuity is not suitable. This rules out Option A.
Irwin's most important objective is that his annuity payments increase gradually over time to help offset rising private health insurance costs. The LLQP study guide explains that an indexed income annuity is designed precisely for this purpose. Indexed annuities provide income that increases each year by a fixed percentage or in line with an inflation index. While initial payments are lower than a level annuity, the increasing payments help preserve purchasing power over time, which is especially important for retirees facing rising expenses such as health care.
A registered level income annuity (Option D) would provide constant payments that do not increase, leaving Irwin vulnerable to rising costs in later years.
Therefore, considering that the funds are registered, Irwin values income security, and he specifically wants payments that grow over time, the LLQP-approved solution is a registered indexed income annuity.
Accordingly, the correct and fully verified answer is Option C.
NEW QUESTION # 74
Jasper is the sole breadwinner in his family. His wife Stephanie has chosen to dedicate all of her time to raising their 3 young children. Luckily, Jasper earns a monthly after-tax income of $25,000 working as a family doctor in the local clinic. Jasper meets with his insurance agent Odda to purchase a life insurance policy that will ensure his family will be able to continue toenjoy their current lifestyle in the event of his death. If his average tax rate is 40% and the investment return is 4%, how much life insurance should Jasper purchase based on the income replacement approach?
Answer: B
Explanation:
The income replacement approach calculates the amount of life insurance needed to replace Jasper'safter-tax income for his dependents over a given period, accounting for an investment return. To maintain the family's current lifestyle, we need to determine the capital required to generate a monthly after-tax income of $25,000.
Calculate the Annual Income Needed:Monthly income required: $25,000Annual income required: $25,000 ×
12 = $300,000
Adjust for Tax:Since Jasper's income needs to be replaced at a pre-tax level with a tax rate of 40%, his gross income requirement is calculated as follows:
A close-up of a math Description automatically generated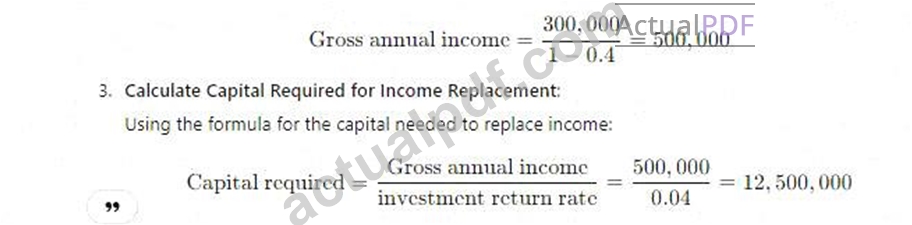
Thus, Jasper needs a life insurance policy worth$12,500,000to replace his income, allowing his family to maintain their lifestyle with a 4% investment return. This calculation aligns with LLQP principles, ensuring that the income replacement fully addresses both current lifestyle needs and tax implications.
NEW QUESTION # 75
......
We are carrying out renovation about LLQP test engine all the time to meet the different requirements of the diversified production market. Thus we have prepared three kinds of versions on LLQP preparation materials. If you are used to study with paper-based materials you can choose the PDF version of our LLQP Study Guide. If you would like to get the mock test before the real LLQP exam you can choose the software version, and if you want to study in anywhere at any time then our online APP version is your best choice since you can download it in any electronic devices.
Real LLQP Dumps Free: https://www.actualpdf.com/LLQP_exam-dumps.html
What's more, part of that ActualPDF LLQP dumps now are free: https://drive.google.com/open?id=1pXH3Nmyye0BP8YsqEf_kwjNvtDk9IoFg