P.S. JpexamがGoogle Driveで共有している無料かつ新しいCSC2ダンプ:https://drive.google.com/open?id=13_HBY3zxvpXolKp2iRPVsrNgh8b_EnRe
世界大手の企業の中で、大部分の企業はCSI製品を主として運用しています。だから、CSIの認証を取得したら、激しい競争の中でもいい仕事を探せます。受験生は試験に合格したいなら、CSC2問題集をしようするのは一番迅速の方法です。多くの受験生たちはこの方法を通して試験に合格しました。
| トピック | 出題範囲 |
|---|---|
| トピック 1 |
|
| トピック 2 |
|
| トピック 3 |
|
| トピック 4 |
|
| トピック 5 |
|
資格試験の意味は、いくつかの点で、さまざまな専門分野での能力を示すCSC2資格を取得する受験者の能力を証明することです。 CSC2学習ガイド教材を選択すると、限られた学習時間でより多くの価値を創造し、より多くの知識を学び、受験できる試験を受けることができます。資格のあるCSC2試験を通じて、これは私たちのCSC2の実際の質問であり、すべてのユーザーの共通の目標であり、私たちは信頼できるヘルパーなので、このような良い機会をお見逃しなく。
質問 # 18
What bond should an advisor recommend to someone who wants to hold bonds and maximize potential cap- tai gams when interest rates are expected to fall?
正解:D
解説:
Along-term bond with a low couponwill maximize capital gains when interest rates fall. Here's why:
* Long-term bondsare more sensitive to interest rate changes due to their longer duration, which amplifies the price movement.
* Low coupon bondsare more affected by changes in interest rates compared to high coupon bonds because more of their value comes from the principal repayment rather than periodic interest payments.
Other options:
* Short-term bonds: Have lower duration and less sensitivity to interest rate changes, so they do not maximize capital gains.
* High coupon bonds: Are less sensitive to interest rate changes because of their higher periodic cash flows.
References:
* Volume 1, Chapter 7:Fixed-Income Securities: Pricing and Trading, section on "Impact of Maturity and Coupon on Bond Prices" explains the relationship between interest rate changes, bond duration, and price sensitivity.
質問 # 19
Anwar is placing a market order to purchase 100 shares of AJL when the bid/ask is $10.25."$ 10.75. Before the trade is complete, the bid/ask moves to $10.207S1Q70. What is the share price that Anwar will pay on the purchase transaction?
正解:C
解説:
A market order executes immediately at the best availableask pricefor a purchase transaction. In this case, the bid/ask initially was $10.25/$10.75. However, before execution, the ask price updated to $10.70, meaning Anwar will pay $10.70 per share.
* B. $10.75: This was the previous ask price but is no longer valid after the update.
* C. $10.29: This value is not relevant to the current bid/ask spread.
* D. $10.20: This represents the updated bid price, which applies to sell orders, not buy orders.
質問 # 20
For institutional trading, when does the investor need to provide trade-matching elements?
正解:C
解説:
Trade-matching is a critical process in institutional trading, ensuring that details of a trade (e.g., price, quantity, and settlement terms) align among the involved parties, including the investor, dealer, and custodian.
In Canada, institutional trade matching must occur within a specific timeline, and the investor is responsible for providing trade-matching elementsafter the trade execution notice is issued by the dealer.
Step-by-Step Explanation:
* What is Trade Matching?Trade matching involves the comparison of trade details between the buyer and seller (and their intermediaries) to confirm accuracy and reduce settlement risks.
* When Does the Investor Provide Trade-Matching Elements?
* After the dealer executes the trade, the dealer issues atrade execution noticeto the investor.
* The investor must then provide the necessary trade-matching details, such as account information, settlement instructions, and any other required confirmations.
* This process ensures that the trade can move seamlessly through to settlement.
* Why Not Other Options?
* Option B (Once the custodian confirms the trade):Incorrect. The custodian's role is typically involved in the final settlement process and not in providing trade-matching details.
* Option C (With the initial order):Incorrect. Trade-matching details are provided after the trade is executed, not at the time the order is placed.
* Option D (Once the trade clears):Incorrect. Trade matching occurs before the trade clears to ensure settlement.
References to Canadian Securities Course Exam 2 Study Materials:
* Volume 2, Chapter 27 - Institutional Clearing and Settlement
* Highlights the process of institutional trade matching, the roles of the investor, dealer, and custodian, and the required timelines.
* Volume 2, Chapter 27 - The Sell Side and the Buy Side of the Market
* Explains trade execution and the responsibilities of institutional clients and their intermediaries in completing trades.
Final answer:
* Option A (After the dealer issues a trade execution notice): Correct.
* Other options are incorrectbased on the standard processes for institutional trade matching in Canada.
質問 # 21
What obligation dues an IA have when communicating information about a preliminary prospectus to prospective investors?
正解:D
解説:
Investment advisors (IAs) are required to record the names and addresses of all individuals who have requested and received a preliminary prospectus. This ensures compliance with securities regulations and provides a record for follow-ups and potential disclosures related to the offering.
* A. The IA must ensure a proxy is mailed: Proxy voting is related to shareholder meetings, not the prospectus distribution.
* B. The IA must provide a greensheet: A greensheet is used internally by investment firms, not distributed to clients.
* C. The IA must make a tombstone advertisement: Tombstone advertisements are created by the issuer, not the IA.
Reference:CSC Volume 1, Chapter 12, "Preliminary Prospectus - IA Obligations" explains the compliance requirements during prospectus distribution.
質問 # 22
An investor has the following separate stock transactions: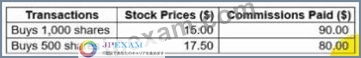
What is the investor's overall adjusted cost base per share? (Round two decimal points.)
正解:D
質問 # 23
......
大方の人は成功への近道がないとよく言われますけど、IT人材にとって、私達のCSC2問題集はあなたの成功へショートカットです。JpexamのCSC2問題集を通して、他の人が手に入れない資格認証を簡単に受け取ります。早めによりよい仕事を探しできて、長閑な万元以上の月給がある生活を楽しみます。
CSC2模擬モード: https://www.jpexam.com/CSC2_exam.html
無料でクラウドストレージから最新のJpexam CSC2 PDFダンプをダウンロードする:https://drive.google.com/open?id=13_HBY3zxvpXolKp2iRPVsrNgh8b_EnRe