BTW, DOWNLOAD part of TestKingFree ClaimCenter-Business-Analysts dumps from Cloud Storage: https://drive.google.com/open?id=1AQB8_Q7LZZdpTyJtGm4aLT-_oatrnpKD
Each question and answer of our ClaimCenter-Business-Analysts training questions are researched and verified by the industry experts. Our team updates the ClaimCenter-Business-Analysts certification material periodically and the updates include all the questions in the past thesis and the latest knowledge points. So our service team is professional and top-tanking on the ClaimCenter-Business-Analysts Exam braindump. And if you have any questions on our study guide, our services will help you with the right and helpful suggestions. Just have a try on our ClaimCenter-Business-Analysts learning prep!
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
| Topic 5 |
|
>> Guidewire ClaimCenter-Business-Analysts Pdf Dumps <<
Our ClaimCenter-Business-Analysts practice materials are suitable for a variety of levels of users, no matter you are in a kind of cultural level, even if you only have high cultural level, you can find in our ClaimCenter-Business-Analysts study materials suitable for their own learning methods. So, for every user of our study materials are a great opportunity, a variety of types to choose from, more and more students also choose our ClaimCenter-Business-Analysts Study Materials, then why are you hesitating?
NEW QUESTION # 24
A car accident in a rural area of Durango, Colorado is reported to Succeed Insurance. The driver of the damaged car reportedly hit the base of a windmill tower while driving at night. There was no other passenger in the car when the accident happened, and the driver has a valid auto policy on file.
While the driver is not physically injured, the entire passenger side of the car has been severely damaged.
Although the windmill is still functioning, the base of the tower has sustained multiple broken parts.
Which two incidents need to be created for the claim based on the reported accident? (Choose two.)
Answer: C,E
Explanation:
In Guidewire ClaimCenter, an Incident is the data object used to capture the specific facts about "what" was damaged or affected during the loss event. It serves as the foundation for creating Exposures (the financial liabilities).
* Vehicle Incident (Option C):The scenario states that the insured's car has been "severely damaged" on the passenger side. To record these facts-including the point of impact, the severity, and the vehicle description-the Adjuster must create aVehicle Incident. This incident will eventually support the collision coverage exposure.
* Property Incident (Option B):The accident involved the car hitting a "windmill tower," resulting in
"broken parts" to the base. In ClaimCenter, damage to third-party non-vehicular objects (like fences, poles, buildings, or towers) is captured using aFixed Property Incident(often referred to generically as a Property Incident). This incident records the damage description and ownership of the windmill, which is necessary to handle the Property Damage Liability claim.
Why other options are incorrect:
* Option E (Injury):The scenario explicitly states the driver is "not physically injured." Therefore, an Injury Incident is not required.
* Option A ("Another structure"):The standard object for third-party fixed property damage is the Property Incident/Fixed Property Incident, not "Another structure."
* Option D (Loss of Use):While possible later, the primary immediate damage is physical. Loss of Use is usually a secondary exposure type, not the primary incident definition for the tower itself.
NEW QUESTION # 25
Whenever the Total Loss Calculator determines that a vehicle is a total loss, Succeed Insurance wants to create a custom history event with the exposure name and total loss score.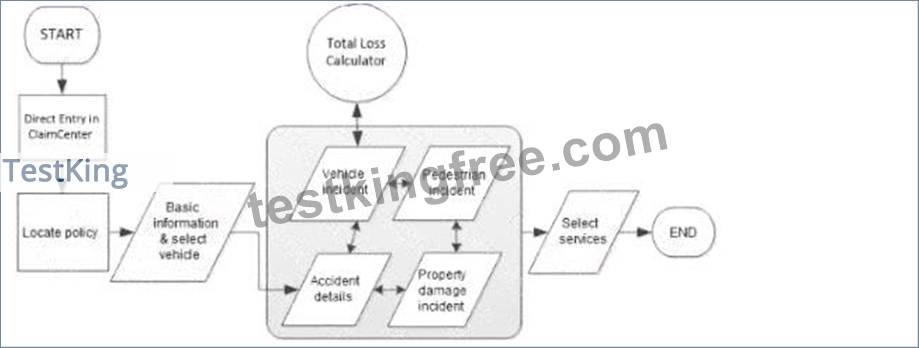
Which step in the claim setup process flow must be completed before the history event can be created?
Answer: B
Explanation:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
In Guidewire ClaimCenter workflow analysis and configuration, defining the correct sequence of operations is critically dependent on Data Availability and Data Dependency.
The specific requirement here dictates that the custom history event must capture theTotal Loss Score. In the context of the ClaimCenter object model and process flow, the Total Loss Score is anoutputvalue generated specifically by theTotal Loss Calculatorengine. Before this calculator runs, the score attribute is effectively null or non-existent.
Therefore, to satisfy the business requirement, the step that writes the history event must be placedafterthe step that generates the data it needs to record.
* Process Logic:If the Business Analyst were to place the history event creation stepbeforethe Total Loss Calculator (Option B) orbeforethe Vehicle Incident (Option D), the system would attempt to write a record containing a score that has not yet been calculated. This would result in either a system error or a history event with a blank/zero value, failing to meet the business requirement.
* Dependency Chain:The workflow dependency is: Vehicle Data Entry -> Total Loss Calculation -> Score Generation -> History Event Creation.
* Implementation Note:In a typical Guidewire implementation, this logic is often handled via "Event Fired" rules or specific "Exit Points" in the workflow. The system waits for the confirmation that the Total Loss calculation service has successfully returned a result. Once that transaction is committed and the score is persisted on the Vehicle or Exposure entity, the subsequent rule to generate the History Event can trigger successfully.
Consequently,Option Cis the only viable placement in the process flow. It ensures that the prerequisite action (calculation) is complete and the required data payload (the score) is available for the subsequent action (logging the history event).
NEW QUESTION # 26
An auto accident in Chicago, Illinois has been reported to Succeed Insurance. The customer service representative uses the ClaimCenter standard Claim Wizard to set up the new claim. The policy is verified in effect and based on the reported exposures the total loss points calculated is 38. There is also a note to have an expert inspection via approved vendor.
What is the most likely claim setup with regards to this reported auto accident?
Answer: D
Explanation:
ClaimCenter uses a logic-based process called Segmentation to categorize claims and Assignment to route them.
* Complexity (Points):The "Total Loss Points" score of38is significantly high. In standard configuration, high scores (typically indicating severe damage or total loss potential) trigger aHigh Complexitysegmentation.
* Assignment (Geography):The accident occurred inChicago (Midwest). The assignment rules will match the geography (Midwest) with the complexity (High/Complex). Therefore, it routes to the Midwest Complex Auto Adjusters Group.
* Workplan (Activity):The specific note regarding an "expert inspection" translates into a generated Activity(likely "Assign Vehicle Inspection" or similar) added to the claim's workplan.
Why other options are incorrect:
* A & D (Low/Mid Complexity):A score of 38 is too high for "Low Complexity" (which is usually for simple fender benders). Assigning a complex claim to a "Low Complexity" group would violate standard routing logic.
* C (Supervisor):Modern ClaimCenter configurations prefer Straight-Through Processing (STP) to a working group. Routing to a Supervisor is generally a fallback for exceptions, whereas this is a standard high-severity scenario that should go directly to the specialized adjusters.
NEW QUESTION # 27
Succeed Insurance allows field Adjusters to write checks directly to the insured to cover damage costs for minor claims such as:
* Personal auto claims involving cracked windshields
* Homeowners claims involving minor glass breakage
The Adjuster uses the Manual Check Wizard to record the check number and amount against a reserve line.
Succeed requires Supervisor approval for all manual checks to ensure that the paper checks are verified against the payment information in ClaimCenter.
Which two limits or rules must be configured in ClaimCenter to ensure that these manual payments are sent to the correct person for approval? (Choose two.)
Answer: A,C
Explanation:
To enforce an approval workflow for a specific type of financial transaction (like "Manual Checks") regardless of the dollar amount, a Business Analyst must leverage both Authority Limits and Transaction Approval Rules.
* Authority Limits (D):These are the primary controls for financial exposure. While typically used for amounts (e.g., "Limit of $5,000"), they are the foundational mechanism that triggers the system's
"Pending Approval" state. For this scenario, an authority limit could be set to $0 for the specific payment method of "Manual Check" to force all such payments into the approval workflow.
* Transaction Approval Rules (C):These rules allow for more granular, logic-based approval triggers beyond simple amounts. Since the requirement specifies "all manual checks" (implying a condition based on themethodof payment, not just the amount), aTransaction Approval Ruleis the best practice configuration. The rule would be written to state:"If Payment Method is Manual, then Approval is Required."
* Why not A (Approval Routing)?While Approval Routing rules determinewhoreceives the request (the
"correct person"), the default behavior in ClaimCenter is to route approvals to the user's Supervisor.
Since the requirement is simply "Succeed requires Supervisor approval," the standard routing logic likely suffices without needing new custom configuration. The critical configuration needed is the trigger(C and D) to stop the payment in the first place.
NEW QUESTION # 28
An Adjuster at Succeed Insurance is handling a homeowners claim with a dwelling exposure for damage to the insured's home. The Adjuster's Authority Limit Profile has the following limits: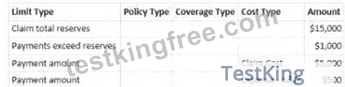
The table below is a view of the property claims organization within Succeed Insurance. The Adjuster is a member of the group Property - Team A.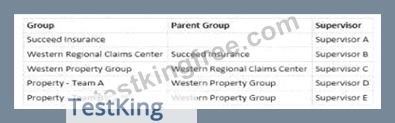
The Adjuster creates a payment in the amount of $6,500 for repairs to the insured's home. How will it be processed assuming that the claim has sufficient reserves for the payment?
Answer: B
Explanation:
This scenario involves checking financial Authority Limits and determining the correct Approval Routing hierarchy in Guidewire ClaimCenter.
* Check Authority Limits:First, compare the transaction amount against the user's specific limits.
* The payment is for "repairs to the insured's home," which is classified asClaim Cost(Indemnity).
* According to the provided Authority Limit Profile, the Adjuster has a "Payment amount" limit of
$5,000for Claim Cost.
* The transaction amount is$6,500.
* Since$6,500 > $5,000, the limit is exceeded, meaning the paymentrequires approval(Ruling out Option B).
* Determine Routing:When a financial transaction requires approval, ClaimCenter routes the approval activity to the supervisor of the group to which the user belongs.
* The Adjuster is a member ofProperty - Team A.
* According to the Organization chart provided, the Supervisor for "Property - Team A" is Supervisor D.
* Therefore, the system will generate an approval activity and assign it specifically to Supervisor D). Supervisor C is the manager of theparentgroup (Western Property Group), so the activity would only go to them if Supervisor Dalsolacked the authority to approve the $6,500, requiring further escalation. However, the initial routing is always to the immediate supervisor.
Why other options are incorrect:
* Option A:Supervisor C is the "Grand-boss" (Supervisor of the parent group), not the immediate supervisor.
* Option B:The amount ($6,500) clearly exceeds the defined limit ($5,000), so automatic processing is impossible.
* Option C:Supervisor A is at the top of the hierarchy (Succeed Insurance), far removed from the initial approval step.
NEW QUESTION # 29
......
The great advantage of the APP online version is if only the clients use our ClaimCenter-Business-Analysts certification guide in the environment with the internet for the first time on any electronic equipment they can use our ClaimCenter-Business-Analysts test materials offline later. So the clients can carry about their electronic equipment available on their hands and when they want to use them to learn our qualification test guide. So the clients can break through the limits of the time and environment and learn our ClaimCenter-Business-Analysts Certification guide at their own wills. This is an outstanding merit of the APP online version.
Latest ClaimCenter-Business-Analysts Exam Duration: https://www.testkingfree.com/Guidewire/ClaimCenter-Business-Analysts-practice-exam-dumps.html
2026 Latest TestKingFree ClaimCenter-Business-Analysts PDF Dumps and ClaimCenter-Business-Analysts Exam Engine Free Share: https://drive.google.com/open?id=1AQB8_Q7LZZdpTyJtGm4aLT-_oatrnpKD