P.S. Free & New PF1 dumps are available on Google Drive shared by TestInsides: https://drive.google.com/open?id=1KMqBPHvyPGH57Ttqs6-FRWXft8S8MS_G
As to the rapid changes happened in this PF1 exam, experts will fix them and we assure your PF1 exam simulation you are looking at now are the newest version. Materials trends are not always easy to forecast on our study guide, but they have predictable pattern for them by ten-year experience who often accurately predict points of knowledge occurring in next PF1 Preparation materials.
| Section | Objectives |
|---|---|
| Topic 1: Non-Regular Payments | - Special payroll payments
|
| Topic 2: New Employee Information | - Employee setup and documentation
|
| Topic 3: Non-Statutory Deductions | - Voluntary deductions
|
| Topic 4: Payroll Accounting | - Payroll accounting practices
|
| Topic 5: Year-End Processing | - Federal and provincial year-end reporting
|
| Topic 6: Employment Income – Regular Earnings | - Regular payroll calculations
|
| Topic 7: Provincial Remittances | - Provincial payroll requirements
|
| Topic 8: Commission Payments | - Commission payroll processing
|
| Topic 9: Employment Income – Allowances, Expenses and Benefits | - Taxable and non-taxable benefits
|
| Topic 10: Record of Employment | - ROE processing
|
| Topic 11: Termination of Employment | - Termination processing
|
| Topic 12: Federal Remittances | - Government remittance obligations
|
| Topic 13: Workers’ Compensation | - Workers compensation administration
|
>> National Payroll Institute PF1 PDF Question <<
First of all, you are able to make full use of our PF1 study torrent through three different versions: PDF, PC and APP online version of our PF1 training guide. For each version, there is no limit and access permission if you want to download our study materials, and at the same time the number of people is not limited. After you purchase PF1 Study Materials, we guarantee that your PF1 study material is tailor-made. The last but not least, we can provide you with a free trial service on the PF1 exam questions.
NEW QUESTION # 13
National Hardware, an Ontario organization, will be terminating the employment of Emilie St. Germain on October 28, 2019, the last day of the pay period. Emilie started with National Hardware on September 19,
2007. Complete the paper Record of Employment (ROE) for Emilie based on the information provided in the following chart.
Note: Vacationable earnings already include the pay in lieu of notice.
All dates must be entered in the format DDMMYYYY.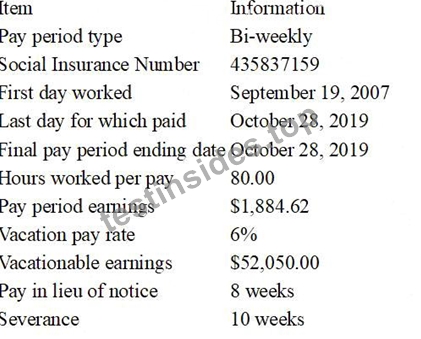
Paper ROE (Form Reference)
Complete the following paper ROE blocks for Emilie:
Block 6 - Pay period type
Block 8 - Social Insurance Number
Block 10 - First day worked
Block 11 - Last day for which paid
Block 12 - Final pay period ending date
Block 15A - Total insurable hours
Block 15B - Total insurable earnings
Block 17A - Vacation pay
Block 17C - Other monies (Pay in lieu of notice)
Block 17C - Other monies (Severance)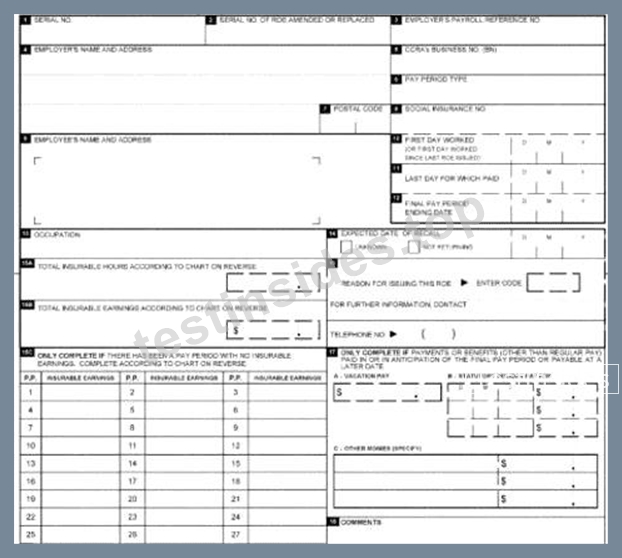
Step 1 - Complete Block 6
Enter the pay period type for Emilie.
Step 2 - Complete Block 8
Enter Emilie's Social Insurance Number.
Step 3 - Complete Block 10
Enter Emilie's first day worked in DDMMYYYY format.
Step 4 - Complete Block 11
Enter Emilie's last day for which paid in DDMMYYYY format.
Step 5 - Complete Block 12
Enter the final pay period ending date in DDMMYYYY format.
Step 6 - Complete Block 15A
Calculate and enter total insurable hours.
Given:
Hours worked per pay period = 80.00
Bi-weekly ROE pay period chart captures 27 pay periods
Step 7 - Complete Block 15B
Calculate and enter total insurable earnings.
Given:
Pay period earnings = $1,884.62
Bi-weekly ROE pay period chart captures 27 pay periods
Step 8 - Complete Block 17A
Calculate and enter vacation pay.
Given:
Vacation pay rate = 6%
Vacationable earnings = $52,050.00
(already includes pay in lieu of notice)
Step 9 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Pay in lieu of notice.
Given:
Pay in lieu of notice = 8 weeks
Use weekly earnings derived from the bi-weekly pay period earnings.
Step 10 - Complete Block 17C
Enter the correct amount in 17C for "Other monies" specified as Severance.
Given:
Severance = 10 weeks
Use the same weekly earnings used in Step 9.
Answer:
Explanation:
See the Below Explanation for complete Solution.
Explanation:
Step 1 - Block 6
Bi-weekly
Step 2 - Block 8
435837159
Step 3 - Block 10
September 19, 2007 # 19092007
Step 4 - Block 11
October 28, 2019 # 28102019
Step 5 - Block 12
October 28, 2019 # 28102019
Step 6 - Block 15A (Total insurable hours)
80.00 × 27 = 2160
Block 15A = 2160
Step 7 - Block 15B (Total insurable earnings)
$1,884.62 × 27 = $50,884.74
Block 15B = 50,884.74
Step 8 - Block 17A (Vacation pay)
$52,050.00 × 6% = $3,123.00
Block 17A = 3,123.00
Step 9 - Block 17C (Pay in lieu of notice)
Weekly earnings = $1,884.62 ÷ 2 = $942.31
Pay in lieu = $942.31 × 8 = $7,538.48
Block 17C (Pay in lieu of notice) = 7,538.48
Step 10 - Block 17C (Severance)
Severance = $942.31 × 10 = $9,423.10
Block 17C (Severance) = 9,423.10
NEW QUESTION # 14
A 900-series Social Insurance Number is issued to:
Answer: C
Explanation:
A SIN that begins with "9" (often called a 900-series SIN) is issued to temporary workers-people who are neither Canadian citizens nor permanent residents-and who are authorized to work in Canada. Service Canada's employer guidance explicitly states that SINs beginning with "9" are issued to temporary workers who are neither Canadian citizens nor permanent residents, and these SINs are valid only until the expiry date shown on the immigration document that authorizes the person to work in Canada.
Service Canada also advises employers to confirm that employees with a SIN starting with "9" remain authorized to work and that their immigration document has not expired.
So, options A-C are incorrect because a 900-series SIN is not for permanent residents ("landed immigrants"), not for Canadians whose SIN "expires," and not based on working outside Canada. It specifically signals temporary status tied to work authorization in Canada.
NEW QUESTION # 15
Which of the following company-compulsory deductions would reduce the employee's gross taxable income for purposes of withholding income taxes?
Answer: A
Explanation:
For payroll withholding, income tax is calculated on taxable income for the pay period, so only deductions that are income-tax deductible (or otherwise reduce taxable income at source) will reduce the employee's taxable base for withholding. Employee contributions to an RRSP are generally deductible for the employee, which is why payroll-deducted RRSP contributions (such as contributions to a group RRSP taken off the paycheque) reduce the amount of income tax withheld when the payroll system is set up to treat them as deductible contributions. The CRA confirms that deductible RRSP contributions can be used to reduce your tax.
By contrast, paying provincial health care premiums (where applicable) and paying an employee share of group benefit plan premiums are not automatic "reduce taxable income at source" deductions in the same way for payroll withholding; they may be personal expenses and, depending on the plan/premium type, may only affect the employee's personal tax situation through credits/deductions when filing, not the standard payroll withholding base. Therefore, the only correct choice is A.
NEW QUESTION # 16
Anthony earns $750.00 per week. He has a cash taxable benefit of $25.00 per week. Anthony is exempt from CPP contributions. Calculate the net taxable income for the week.
Answer:
Explanation:
$775.00
Explanation:
"Net taxable income" for payroll withholding purposes is the amount of income on which income tax is calculated for the pay period. It generally starts with the employee's gross taxable earnings for the period (regular wages plus any taxable benefits/allowances that must be included in income), then subtracts only those deductions that are deductible for tax at source (for example, certain registered pension plan contributions, union dues, etc., if applicable). A cash taxable benefit is treated like additional remuneration and is included in taxable income. (canada.ca) Here, Anthony's weekly taxable earnings are:
$750.00 wages + $25.00 cash taxable benefit = $775.00.
Being exempt from CPP contributions affects whether CPP is deducted, but CPP is not a "net taxable income" subtraction in this question (and in any case, no CPP is being deducted). The question also does not mention any other tax-deductible payroll deductions (like RPP contributions), so there is nothing to subtract from taxable earnings.
Therefore, Anthony's net taxable income for the week is $775.00.
NEW QUESTION # 17
A retiring allowance includes:
Answer: D
Explanation:
The CRA defines a retiring allowance (also called severance pay) as an amount paid when or after an employee retires or loses their job, in recognition of long service or for the loss of employment.
However, the CRA is also explicit about what a retiring allowance does not include. It does not include
"salary, wages, bonuses, [or] overtime," which rules out bonus/incentive pay and accumulated overtime in the options. It also does not include "payments for accumulated vacation leave not taken," which rules out vacation pay as a retiring allowance. Finally, it does not include wages in lieu of termination notice, which rules out wages in lieu (including legislated notice pay) as a retiring allowance.
Because every listed item is specifically excluded by CRA guidance, the correct answer is None of the above (E).
NEW QUESTION # 18
......
This type of National Payroll Institute PF1 actual exam simulation helps to calm your exam anxiety. Since the software keeps a record of your attempts, you can overcome mistakes before the National Payroll Institute PF1 final exam attempt. Knowing the style of the National Payroll Institute PF1 examination is a great help to pass the test and this feature is one of the perks you will get in the desktop practice exam software.
PF1 Exam Duration: https://www.testinsides.top/PF1-dumps-review.html
2026 Latest TestInsides PF1 PDF Dumps and PF1 Exam Engine Free Share: https://drive.google.com/open?id=1KMqBPHvyPGH57Ttqs6-FRWXft8S8MS_G