P.S. Free & New ICWIM dumps are available on Google Drive shared by Prep4sureExam: https://drive.google.com/open?id=16d66PAiLsiIbQYx6g8dkSec1KPDrQ-bD
Our website aimed to help you to get through your certification test easier with the help of our valid ICWIM vce braindumps. You just need to remember the answers when you practice ICWIM real questions because all materials are tested by our experts and professionals. Our ICWIM Study Guide will be your first choice of exam materials as you just need to spend one or days to grasp the knowledge points of ICWIM practice exam.
| Section | Objectives |
|---|---|
| Investment and Financial Markets | - Market participants and their roles - Asset classes and investment products - Structure of financial markets |
| Regulation and Ethics | - Regulatory environment in financial services - Conduct of business and compliance principles - Ethical standards in investment advice |
| Wealth Management Principles | - Risk and return concepts - Client investment needs and objectives - Portfolio construction basics |
| Investment Products and Suitability | - Suitability and client profiling - Taxation and charges overview - Equities, bonds, and collective investments |
>> Reliable ICWIM Exam Cost <<
The price for ICWIM learning materials is reasonable, and no matter you are a student or an employee, you can afford the expense. In addition, ICWIM exam dumps are edited by professional experts, and therefore the quality can be guaranteed. ICWIM exam materials cover most of the knowledge points for the exam, and you can master them through study. In order to let you know the latest information for the exam ,we offer you free update for 365 days after purchasing, and the update version for ICWIM Exam Dumps will be sent to you automatically.
NEW QUESTION # 32
The beneficiaries of a typical shareholder protection policy:
Answer: A
Explanation:
Shareholder protection is a business protection arrangement designed to ensure that, on the death of a shareholder, the surviving shareholders can retain control of the company while the deceased's beneficiaries receive fair value for the shares. The policy is usually set up so that, if a shareholder dies, the payout provides funds to the surviving shareholders to buy the deceased shareholder's shares. This is commonly paired with a cross-option agreement, which gives the surviving shareholders the option to buy and the deceased's estate the option to sell, creating a clean, pre-agreed route to transfer ownership. As a result, the practical "benefit" of the protection arrangement is that the remaining shareholders have the financial means to purchase the shares and maintain continuity of control, while the estate receives cash rather than an illiquid minority stake.
Although the deceased's estate receives the sale proceeds, the policy is typically structured to support the purchase by the remaining shareholders, making them the intended beneficiaries for control purposes. The company itself is normally the beneficiary in key person cover, not shareholder protection.
NEW QUESTION # 33
Why is a flat yield measurement regarded as an inaccurate measure of the return on a bond investment?
Answer: D
Explanation:
Flat yield measures a bond's return using the annual coupon expressed as a percentage of the bond's current market price. This is a quick, simple measure of the income return, but it is not a complete measure of the investor's total return if the bond is held to redemption. The key weakness is that it ignores the fact that most bonds redeem at par, so if a bond is bought at a discount, the investor will also earn a capital gain as the price moves towards par at maturity. Conversely, if the bond is bought at a premium, the investor will suffer a capital loss as it pulls back towards par by redemption. Flat yield also does not capture the time value of money across all cash flows in the way that a redemption yield measure does. For exam purposes, the most direct reason it is inaccurate is that it omits the capital gain or loss component that arises between purchase price and redemption value, which can materially change the true return.
NEW QUESTION # 34
An investor would regard a company's Interest Cover ratio as significant because it provides:
Answer: C
Explanation:
Interest Cover Ratio measures how easily a company can meet interest payments on its debt.
A black text with black letters AI-generated content may be incorrect.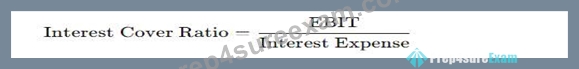
* Why is Option A Correct?
* A higher ratio means a company comfortably covers interest costs.
* A low ratio signals higher financial risk and potential default risk.
* Why Not Other Options?
* B (Interest rate paid) # The ratio assesses coverage, not cost of debt.
* C (Debt vs equity breakdown) # This is measured by the debt-to-equity ratio.
* D (Cash for dividends) # Interest cover assesses debt serviceability, not dividend affordability
.
# Reference: CFA Institute (Financial Ratios), CISI Wealth & Investment Management.
NEW QUESTION # 35
When creating a portfolio for a risk-averse client, why would you select stocks with a beta of less than one?
Answer: C
Explanation:
Stocks with abeta of less than oneare less volatile than the overall market. Including such stocks in a portfolio helps reduce its overall volatility, aligning with the risk-averse nature of the client.
* Easier to understand (A): Simplicity is not a factor in beta selection.
* Moves in line with the market (B): A beta of less than one means the portfolio moves less than the market.
* High-volatility portfolio (D): This would involve stocks with a beta greater than one, contrary to the client's risk profile.
References:
* International Certificate in Wealth & Investment Management: Beta as a measure of systematic risk and its implications for portfolio construction.
* CAPM (Capital Asset Pricing Model) principles on beta and risk.
NEW QUESTION # 36
An active portfolio manager is deliberately holding securities in a portfolio in differing proportions from that in which they are weighted within the benchmark. Why are they doing this?
Answer: B
Explanation:
Active management involves taking positions that differ from the benchmark to try to generate excess return, often referred to as alpha. If a portfolio held securities in exactly the same weights as the benchmark, before fees it would deliver benchmark-like performance and would be classified as passive or index tracking. By overweighting securities expected to outperform and underweighting or excluding those expected to underperform, the manager is expressing investment views and accepting active risk, commonly measured by tracking error. This deliberate deviation is the defining feature of active management and is undertaken to outperform after costs. Liquidity considerations and dealing costs can influence how active bets are implemented, but they are not the primary reason for deviating from benchmark weights. Anticipating a benchmark re-weighting is possible, but that is just one specific type of active view and is not the broad objective being tested. The examinable principle is that active managers differ from the benchmark in order to outperform it.
NEW QUESTION # 37
......
You don't need to install any separate software or plugin to use it on your system to practice for your actual International Certificate in Wealth & Investment Management (ICWIM) exam. CISI web-based practice software is supported by all well-known browsers like Chrome, Firefox, Opera, Internet Explorer, etc.
Top ICWIM Questions: https://www.prep4sureexam.com/ICWIM-dumps-torrent.html
BTW, DOWNLOAD part of Prep4sureExam ICWIM dumps from Cloud Storage: https://drive.google.com/open?id=16d66PAiLsiIbQYx6g8dkSec1KPDrQ-bD