BTW, DOWNLOAD part of Actual4test ClaimCenter-Business-Analysts dumps from Cloud Storage: https://drive.google.com/open?id=1qfyoc8EKFEd7MSpY7OEl-nO-ltWBlkAG
Our ClaimCenter-Business-Analysts exam guide question is recognized as the standard and authorized study materials and is widely commended at home and abroad. Our ClaimCenter-Business-Analysts study materials boost superior advantages and the service of our products is perfect. We choose the most useful and typical questions and answers which contain the key points of the test and we try our best to use the least amount of questions and answers to showcase the most significant information. Our ClaimCenter-Business-Analysts learning guide provides a variety of functions to help the clients improve their learning and pass the ClaimCenter-Business-Analysts exam.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
>> ClaimCenter-Business-Analysts Study Test <<
The ClaimCenter-Business-Analysts practice test of Actual4test is created and updated after feedback from thousands of professionals. Additionally, we also offer up to free ClaimCenter-Business-Analysts exam dumps updates. These free updates will help you study as per the Guidewire ClaimCenter-Business-Analysts latest examination content. Our valued customers can also download a free demo of our Guidewire ClaimCenter-Business-Analysts exam dumps before purchasing.
NEW QUESTION # 36
Under the Travel loss type, Succeed Insurance offers personal travel policies as part of its travel line of business.
Which two pieces of information in the user interface (UI) will be different for a personal travel claim than for a personal auto or homeowners claim? (Choose two.)
Answer: A,C
Explanation:
Guidewire ClaimCenter is designed to support multiple Lines of Business (LOB), and the User Interface adapts dynamically based on the policy type associated with the claim.
* Incident Types (Option B):The "Incident" is the object that describes what was damaged or lost.
* ForAuto, the UI displaysVehicle Incidents(describing cars).
* ForHomeowners, the UI displaysDwellingorFixed Property Incidents.
* ForTravel, the UI will display distinct incident types such asBaggage Incident(for lost luggage) orTrip Cancellation Incident. These are fundamentally different data objects with different fields.
* Loss Causes (Option C):The LossCause typelist is filtered by the Line of Business.
* Autoclaims show causes like "Collision," "Rear-end," or "Theft of Vehicle."
* Travelclaims will show completely different values such as "Trip Delay," "Lost Baggage,"
"Medical Emergency," or "Cancellation."
Why other options are incorrect:
* Financial Summary (A):The structural format of the Financial Summary screen (displaying Reserve Lines, Payments, and Remaining Reserves) is a core system framework that remains consistent across all lines of business.
* Contact Information (E):The Contact entity (Name, Address, Phone) is a shared entity. The fields used to capture a person's details are generally the same whether they are a driver, a homeowner, or a traveler.
NEW QUESTION # 37
Which scenario shows a Business Analyst (BA) demonstrating an important way to use Guidewire's Business Process Flows during a product implementation?
Answer: C
Explanation:
One of the primary value drivers of a Guidewire implementation is the "Adopt" or "Fit-to-Standard" approach, which encourages insurers to align their operations with industry best practices embedded in the software.
* Best Practice (Option B):The most effective use of Guidewire's standard Business Process Flows is to use them as a reference tochange the customer's internal processes. Instead of customizing the software to match a legacy (and potentially inefficient) way of doing things, the BA uses the base product flow to demonstrate how the system works out-of-the-box and guides the business to adapt their assignment logic to match this standard. This reduces customization costs and simplifies future upgrades.
* Why Option A is incorrect:This describes the "Gap" approach where the software is heavily customized to fit the old process ("continue using our current process"). This is considered an anti- pattern in modern implementations as it increases technical debt.
* Why Option C is incorrect:Comparing FNOL (intake) to Reserves (financials) is comparing two completely different lifecycle stages, making the gap analysis invalid.
* Why Option D is incorrect:Lack of documentation is not a valid reason to ignore the standard flows; in fact, the standard flows can serve as thenewdocumentation for the undocumented process.
Based on the Guidewire ClaimCenter Business Analyst documentation and the provided exhibits, here is the verified answer for Question 42.
NEW QUESTION # 38
An auto claim is owned by Adjuster1. The Customer Service Representative (CSR) that created the claim owns one follow-up activity on the claim. An Injury Specialist owns an injury exposure on the claim. All these persons are members of Auto Team 1.
The Team Lead determines that Adjuster1 is overworked and reassigns the claim to Adjuster2, a member of Auto Team 2.
Which three people now have access to the claim? (Choose three.)
Answer: A,D,F
Explanation:
250 to 350 words From Exact Extract of Guidewire ClaimCenter Business Analyst documentation:
In Guidewire ClaimCenter, access to a claim file is determined by Access Control Lists (ACLs), which are dynamically updated based on user roles and ownership. A user is granted access to a claim if they own the claim itself, or if they own a sub-object within that claim, such as an Activity or an Exposure.
* Adjuster2 (Option E):Upon reassignment, Adjuster2 becomes the newClaim Owner. The owner of the claim record always has full view and edit access to the claim.
* CSR (Option C):The CSR retains ownership of a specificActivity(the follow-up task). In the ClaimCenter security model, owning an open activity on a claim grants the user "view" access to the parent claim so they can perform the necessary work to complete their task. Reassigning the claim header does not automatically reassign the activities owned by other users.
* Injury Specialist (Option D):This user owns anExposure(a distinct financial sub-record for a specific coverage feature). Similar to activities, owning an exposure grants access to the parent claim. The reassignment of the main claim file from Adjuster1 to Adjuster2 does not strip the Injury Specialist of their ownership of the specific injury exposure.
Why Adjuster1 loses access:Adjuster1 was the previous owner. Once ownership is transferred to Adjuster2 (who is in a different group, "Auto Team 2"), Adjuster1 no longer meets the criteria for ownership access.
Unless Adjuster1 is explicitly added to the ACL manually or has "Super User" privileges (not stated), they lose the automatic access rights associated with being the owner.
NEW QUESTION # 39
What are two recommended best practices with user interface (UI) mock-ups in a ClaimCenter implementation project? (Choose two.)
Answer: A,C
Explanation:
In a Guidewire implementation, User Interface (UI) mock-ups serve as critical visual aids to bridge the gap between written business requirements and the final technical solution.
* Best Practice 1 (Option B):While sophisticated prototyping tools (like Balsamiq or Axure) are valuable, they are not always strictly necessary for every change. A "low-fidelity" mock-up is often sufficient and highly effective for minor adjustments. If a BA lacks access to specialized software, the recommended best practice is to take a screenshot of the existing ClaimCenter screen and overlay it with text boxes, arrows, or simple graphics (using tools like Paint or PowerPoint) to clearly indicate where fields should be added, moved, or removed. The goal is clarity of intent, not artistic perfection.
* Best Practice 2 (Option D):Traceability is fundamental to the Agile and hybrid methodologies used in Guidewire projects. Every artifact, including mock-ups, must be traceable back to the specificUser StoryorRequirement Numberit supports. By explicitly documenting the requirement number on or with the mock-up, the BA ensures that developers understand exactly which functionality is being visualized and that QA testers can validate the final screen against the correct scope.
Why other options are incorrect:
* Option A:A live demo shows thecurrentstate. It cannot effectively demonstratefuturechanges (fields that don't exist yet) without a visual mock-up to accompany the explanation.
* Option C:Stating that tools "should not be used" is incorrect; tools are generally encouraged when available to create high-fidelity prototypes.
NEW QUESTION # 40
An Adjuster at Succeed Insurance is handling a personal auto claim for an insured who hit a tree after swerving to avoid a child who ran into the road.
The Adjuster has this Authority Limit Profile: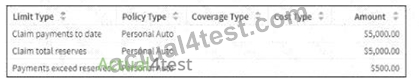
The Adjuster creates a collision exposure and sets the initial reserves so that payments can be made to the insured for repairs to the damaged vehicle. No payments have been created yet.
The current financials for the claim are as follows:
Which two financial transactions will not require approval given that each option is the only transaction change rather than a cumulative change? (Choose two.)
Answer: B,D
Explanation:
To determine if a transaction requires approval, we must compare the proposed transaction against the Adjuster's Authority Limits and the current financial state of the claim.
* Current State:Total Reserves = $3,000 ($2,500 Indemnity + $500 Expense). Total Paid = $0.
* Adjuster Limits:
* Claim Total Reserves Limit: $5,000
* Payments Exceed Reserves Limit: $500
Evaluation of Options:
* Option B (No Approval Required):Making a $2,000 payment against the "Claim Cost - Auto body" reserve.
* The available reserve is $2,500. Since $2,000 < $2,500, the payment does not exceed the reserve.
* The total payments on the claim would be $2,000, which is well below the "Claim payments to date" limit of $5,000.
* Option D (No Approval Required):Increasing the Expense reserve to $550.
* This increases the total claim reserves from $3,000 to $3,050 ($2,500 + $550).
* Since $3,050 is below the Adjuster's "Claim total reserves" limit of $5,000, no approval is triggered.
Why other options require approval:
* Option A:A payment of $1,100 against a $500 reserve means the payment exceeds the reserve by$600.
The Adjuster's limit for "Payments exceed reserves" is only$500. Since $600 > $500, approval is required.
* Option C:Increasing the Auto body reserve to $6,000 would raise the total claim reserves to$6,500 ($6,000 + $500). This exceeds the Adjuster's "Claim total reserves" limit of $5,000, triggering an approval.
NEW QUESTION # 41
......
Guidewire ClaimCenter-Business-Analysts dumps PDF version is printable and embedded with valid Guidewire ClaimCenter-Business-Analysts questions to help you get ready for the ClaimCenter-Business-Analysts exam quickly. ClaimCenter Business Analyst - Mammoth Proctored Exam (ClaimCenter-Business-Analysts) exam dumps pdf are also usable on several smart devices. You can use it anywhere at any time on your smartphones and tablets.
Interactive ClaimCenter-Business-Analysts Course: https://www.actual4test.com/ClaimCenter-Business-Analysts_examcollection.html
P.S. Free & New ClaimCenter-Business-Analysts dumps are available on Google Drive shared by Actual4test: https://drive.google.com/open?id=1qfyoc8EKFEd7MSpY7OEl-nO-ltWBlkAG