さらに、JPNTest Financial-Managementダンプの一部が現在無料で提供されています:https://drive.google.com/open?id=1L_bGClzIeZO7CkQ2XN911CSGdH14IP3O
JPNTestは認定で優秀なIT資料のウエブサイトで、ここでWGU Financial-Management認定試験の先輩の経験と暦年の試験の材料を見つけることができるとともに部分の最新の試験の題目と詳しい回答を無料にダウンロードこともできますよ。弊社のIT技術専門家たち は質が高い問題集と答えを提供し、お客様が合格できるように努めています。
| Section | Weight | Objectives |
|---|---|---|
| Risk and Return | 12% | - Systematic vs unsystematic risk - Beta and Capital Asset Pricing Model - Portfolio risk and diversification |
| Financial Statement Analysis | 20% | - Income statement, balance sheet, cash flow statement - Ratio analysis: liquidity, profitability, solvency, efficiency - Common-size and trend analysis |
| Capital Budgeting | 10% | - NPV, IRR, payback period, profitability index - Cash flow estimation and project evaluation |
| Capital Structure and Financing | 10% | - Dividend policy and payout decisions - Leverage and cost of capital |
| Time Value of Money | 18% | - Present value, future value, annuities, perpetuities - Discounted cash flow valuation - Effective vs nominal interest rates |
| Financial Markets and Corporate Objectives | 15% | - Types of financial markets and instruments - Goal of the firm: shareholder wealth maximization - Role of financial institutions |
| Valuation of Securities | 15% | - Cost of capital components - Bond valuation, yield to maturity, risk characteristics - Stock valuation: dividend growth model, CAPM |
>> Financial-Management無料過去問 <<
IT領域での主要な問題が質と実用性が欠くということを我々ははっきり知っています。JPNTestのWGUのFinancial-Managementの試験問題と解答はあなたが必要とした一切の試験トレーニング資料を準備して差し上げます。実際の試験のシナリオと一致で、选択問題(多肢選択問題)はあなたが試験を受かるために有効な助けになれます。JPNTestのWGUのFinancial-Management「WGU Financial Management VBC1」の試験トレーニング資料は検証した試験資料で、JPNTestの専門的な実践経験に含まれています。
質問 # 20
What does the DuPont equation decompose return on equity (ROE) into?
正解:D
解説:
The DuPont equation breaks return on equity (ROE) into three key components to show how profitability, efficiency, and leverage interact to drive shareholder returns. The classic three-step DuPont formula expresses ROE as:
ROE = Net Profit Margin × Total Asset Turnover × Equity Multiplier (or leverage measure).
Net profit margin reflects operating and cost efficiency, total asset turnover measures how effectively assets generate sales, and the equity multiplier (closely related to the debt-to-equity ratio) captures the impact of financial leverage. This decomposition allows analysts and managers to identify whether changes in ROE are driven by margins, asset utilization, or financing decisions. Option D correctly aligns with this framework by identifying net margin and asset turnover along with a leverage measure (debt-to-equity). The other options include ratios not used in the DuPont framework or omit a critical component. The DuPont analysis is widely used in financial management to diagnose performance issues and guide strategic improvements.
質問 # 21
Kretsmart anticipates its sales will grow by10% each year for the next two years. Information from the company's current income statement is given below, andCost of Goods Sold (COGS) is assumed to be a spontaneous account.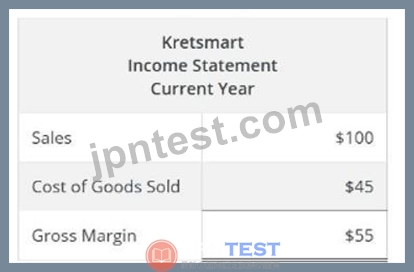
What would the company'sprojected gross margin for Year 2?
正解:B
解説:
When sales grow and cost of goods sold (COGS) is assumed to be a spontaneous account, COGS increases proportionally with sales. In the current year, Kretsmart's gross margin ratio is calculated as Gross Margin ÷ Sales = $55 ÷ $100 =55%, while COGS represents45%of sales.
Sales are projected to grow by 10% per year for two years. Therefore, projected sales for Year 2 are:
$100 × 1.10 × 1.10 =$121.00.
Since COGS remains 45% of sales, projected COGS for Year 2 equals:
$121.00 × 0.45 =$54.45.
Gross margin is then calculated as:
$121.00 # $54.45 =$66.55.
Financial management forecasting techniques commonly use percentage-of-sales assumptions for spontaneous accounts such as COGS, inventory, and receivables. This method allows managers to project future income statements consistently with expected growth. Option B ($66.55) correctly reflects the projected gross margin for Year 2 under these assumptions.
質問 # 22
What is the purpose of covenants in a bond indenture?
正解:A
解説:
Covenants in a bond indenture are contractual provisions designed to protect bondholders by restricting or requiring certain actions by the issuer. These provisions help reduce agency problems between shareholders and debtholders after the debt has been issued. For example, covenants may limit additional borrowing, restrict dividend payments, require the maintenance of certain financial ratios, or prohibit the sale of important assets without approval. Some covenants are affirmative, meaning the issuer must do something, while others are negative, meaning the issuer must avoid certain actions. Their purpose is not to set the bond's coupon rate or determine its market price directly. Instead, they reduce risk for lenders by helping preserve the issuer's ability to repay interest and principal. In financial management, stronger covenants can sometimes allow a company to borrow at a lower interest rate because investors perceive less risk. The other answer choices are incorrect because interest rate, par value, and coupon amounts are bond terms, not the purpose of covenants. Therefore, A is correct because covenants are specifically used to protect bondholders' interests through enforceable conditions placed on the issuer.
質問 # 23
A stock has a dividend per share of $5 and is expected to grow at a constant rate of 3% indefinitely. The required rate of return is 9%.
What is the value of the stock?
正解:C
解説:
This question applies the Gordon growth (constant growth dividend discount) model, which values a stock as the present value of an infinite stream of dividends growing at a constant rate. The model assumes that dividends grow steadily and that the required rate of return exceeds the growth rate, ensuring a finite value. The formula is:
Stock Value = D# ÷ (r # g),
where D# is the dividend expected next year, r is the required rate of return, and g is the growth rate. If the current dividend is $5, the next dividend equals $5 × (1 + 0.03) = $5.15. Substituting into the formula gives:
$5.15 ÷ (0.09 # 0.03) = $5.15 ÷ 0.06 = $85.83.
This valuation approach is commonly used for mature firms with stable dividend policies and predictable growth. Financial managers and analysts rely on this model to estimate intrinsic stock value and assess whether a stock is overvalued or undervalued relative to its market price.
質問 # 24
What is an advantage of using the Gordon growth model to estimate the cost of common equity?
正解:A
解説:
A major advantage of the Gordon growth model is that it explicitly incorporates expectations about future dividend growth. By linking the stock's value to anticipated dividends and their growth rate, the model aligns valuation with investors' forward-looking expectations rather than solely historical data.
This forward-looking nature is consistent with modern financial management principles, which emphasize expected future cash flows as the primary driver of value. Unlike CAPM, which focuses on risk via beta, the Gordon growth model directly reflects dividend policy and growth prospects. For mature firms with stable growth, this provides a practical and intuitive estimate of the cost of equity.
Option C correctly identifies this strength of the model.
質問 # 25
......
Financial-Management実践用紙の信頼できる、効率的で思慮深いサービスは、最高のユーザーエクスペリエンスを提供し、Financial-Management学習資料で必要なものを取得することもできます。私たちのFinancial-Management学習教材があなたの夢を追求するためにあなたと同行できることを願っています。 Financial-Management無料のトレーニング資料を選択できる場合、私たちは非常に満足しています。お会いできることを楽しみにしています。 Financial-Management学習ガイドの助けを借りて、他の人よりも多くの機会を得ることができ、近い将来、あなたの夢が現実になるかもしれません。
Financial-Management試験問題解説集: https://www.jpntest.com/shiken/Financial-Management-mondaishu
無料でクラウドストレージから最新のJPNTest Financial-Management PDFダンプをダウンロードする:https://drive.google.com/open?id=1L_bGClzIeZO7CkQ2XN911CSGdH14IP3O