P.S. Free 2026 Guidewire ClaimCenter-Business-Analysts dumps are available on Google Drive shared by NewPassLeader: https://drive.google.com/open?id=1xElDDWvep7VDKCFYPBIIYeVuLCxznEgA
Our ClaimCenter-Business-Analysts real quiz boosts 3 versions: the PDF, the Softwate and the APP online which will satisfy our customers by their varied functions to make you learn comprehensively and efficiently. The learning of our ClaimCenter-Business-Analysts study materials costs you little time and energy and we update them frequently. We can claim that you will be ready to write your exam after studying with our ClaimCenter-Business-Analysts Exam Guide for 20 to 30 hours. To understand our ClaimCenter-Business-Analysts learning questions in detail, just come and try!
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
>> ClaimCenter-Business-Analysts Exam Objectives <<
No matter you are exam candidates of high caliber or newbies, our Guidewire ClaimCenter-Business-Analysts exam quiz will be your propulsion to gain the best results with least time and reasonable money. Not only because the outstanding content of ClaimCenter-Business-Analysts Real Dumps that produced by our professional expert but also for the reason that we have excellent vocational moral to improve our ClaimCenter-Business-Analysts learning materials quality.
NEW QUESTION # 30
An auto accident in Chicago, Illinois has been reported to Succeed Insurance. The customer service representative uses the ClaimCenter standard Claim Wizard to set up the new claim. The policy is verified in effect and based on the reported exposures the total loss points calculated is 38. There is also a note to have an expert inspection via approved vendor.
What is the most likely claim setup with regards to this reported auto accident?
Answer: A
Explanation:
ClaimCenter uses a logic-based process called Segmentation to categorize claims and Assignment to route them.
* Complexity (Points):The "Total Loss Points" score of38is significantly high. In standard configuration, high scores (typically indicating severe damage or total loss potential) trigger aHigh Complexitysegmentation.
* Assignment (Geography):The accident occurred inChicago (Midwest). The assignment rules will match the geography (Midwest) with the complexity (High/Complex). Therefore, it routes to the Midwest Complex Auto Adjusters Group.
* Workplan (Activity):The specific note regarding an "expert inspection" translates into a generated Activity(likely "Assign Vehicle Inspection" or similar) added to the claim's workplan.
Why other options are incorrect:
* A & D (Low/Mid Complexity):A score of 38 is too high for "Low Complexity" (which is usually for simple fender benders). Assigning a complex claim to a "Low Complexity" group would violate standard routing logic.
* C (Supervisor):Modern ClaimCenter configurations prefer Straight-Through Processing (STP) to a working group. Routing to a Supervisor is generally a fallback for exceptions, whereas this is a standard high-severity scenario that should go directly to the specialized adjusters.
NEW QUESTION # 31
Succeed Insurance has a requirement to add a new high-risk indicator to the Claim Status screen for property claims that have a lien on the property. A new icon will be added to the configuration to provide a visual indicator making it easier for Adjusters and other ClaimCenter users to determine that a claim has a lien.
Which two common areas of the user interface (UI) can display the new lien icon? (Choose two.)
Answer: B,D
Explanation:
In the standard Guidewire ClaimCenter User Interface architecture, high-priority alerts and claim indicators are displayed in two primary locations to ensure visibility:
* The Info Bar (Option D):This is the persistent strip located at the top of the claim file (just below the Tab Bar). It remains visible regardless of which specific claim sub-screen (Medical, Financials, Notes) the user is navigating. It is designed specifically to host "High Risk Indicators" such as Litigation, Fatalities, Coverage issues, and in this scenario, a "Lien" indicator. This ensures the adjuster is aware of the critical status immediately upon opening the claim.
* The Screen Area (Option A):Specifically, theClaim Status(or Summary) screen-which resides in the main Screen Area-contains a dedicated section for "Claim Indicators." Here, the icon is displayed along with a text description and potential toggle status (On/Off). The prompt explicitly mentions the requirement to "add a new high-risk indicator to the Claim Status screen," confirming the Screen Area as the second location.
Why other options are incorrect:
* Sidebar (B):The sidebar (left panel) is used for the "Actions" menu and navigation links (steps) to move between screens. It does not typically host status icons for the claim object itself.
* Workspace (C):While "Workspace" can refer to the application frame, in UI terminology, it often refers to the specific worksheets (bottom pane) or the container, not the specific UI element for indicators.
* Tab Bar (E):The Tab Bar is for high-level navigation (Claim, Desktop, Administration, Search) and does not display claim-specific data icons.
NEW QUESTION # 32
Succeed Insurance has a requirement to add a new high-risk indicator to the Claim Status screen for property claims that have a lien on the property. A new icon will be added to the configuration to provide a visual indicator making it easier for Adjusters and other ClaimCenter users to determine that a claim has a lien.
Which two common areas of the user interface (UI) can display the new lien icon? (Choose two.)
Answer: B,D
Explanation:
In the standard Guidewire ClaimCenter User Interface architecture, high-priority alerts and claim indicators are displayed in two primary locations to ensure visibility:
* The Info Bar (Option D):This is the persistent strip located at the top of the claim file (just below the Tab Bar). It remains visible regardless of which specific claim sub-screen (Medical, Financials, Notes) the user is navigating. It is designed specifically to host "High Risk Indicators" such as Litigation, Fatalities, Coverage issues, and in this scenario, a "Lien" indicator. This ensures the adjuster is aware of the critical status immediately upon opening the claim.
* The Screen Area (Option A):Specifically, theClaim Status(or Summary) screen-which resides in the main Screen Area-contains a dedicated section for "Claim Indicators." Here, the icon is displayed along with a text description and potential toggle status (On/Off). The prompt explicitly mentions the requirement to "add a new high-risk indicator to the Claim Status screen," confirming the Screen Area as the second location.
Why other options are incorrect:
* Sidebar (B):The sidebar (left panel) is used for the "Actions" menu and navigation links (steps) to move between screens. It does not typically host status icons for the claim object itself.
* Workspace (C):While "Workspace" can refer to the application frame, in UI terminology, it often refers to the specific worksheets (bottom pane) or the container, not the specific UI element for indicators.
* Tab Bar (E):The Tab Bar is for high-level navigation (Claim, Desktop, Administration, Search) and does not display claim-specific data icons.
NEW QUESTION # 33
Succeed Insurance requires that a new 'Driver under 18?' field be added to the vehicle incident screen for personal auto claims to indicate whether or not the driver of the vehicle was a minor when the loss occurred.
The field will be set by calculating the driver's age using the date of loss and the driver's date of birth.
There are two validation requirements:
* The field must be set if the 'Date of Birth' field for the driver is not null.
* No payments can be made for collision exposures if the 'Date of Birth' field for the driver of the vehicle is null.
A Business Analyst (BA) documents the validation requirements in the validation tab of the User Story Card
'Adjudicate - Update Maintain Vehicle Incident for Personal Auto Claims' as shown in the exhibit.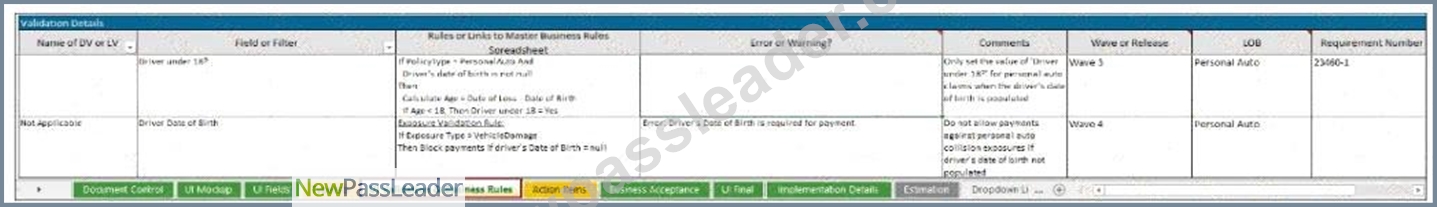
What information in the two validation examples is either missing or incorrectly documented? (Choose two.)
Answer: A,C
Explanation:
The User Story Card exhibit contains several documentation errors when compared to standard Guidewire requirements gathering best practices and the specific scenario provided.
* Missing Requirement Number and Logic Gap (Option C):
* Traceability:In the second row of the exhibit (the payment validation rule), the "Requirement Number" column is completely blank. Traceability back to the original requirements document is mandatory for all entries.
* Logic Precision:The requirement explicitly states that the rule applies to"personal auto claims"
. However, the logic documented in the "Rules" column (If Exposure Type = VehicleDamage Then Block...) doesnotcheck the Policy Type. It relies solely on the Exposure Type, which could exist on Commercial Auto policies as well. To accurately reflect the business requirement, the condition If PolicyType = Personal Auto must be added (similar to how it was done in the first row).
* Missing DV/LV Context for Validation (Option D):
* UI Anchoring:The second requirement is a validation rule that triggers an error ("Driver's Date of Birth is required..."). For the system to highlight the specific field on the screen (the "Driver Date of Birth" widget) when the error occurs, the rule must be associated with the specificDetail View (DV)orList View (LV)where that field resides (e.g., VehicleIncidentDV). The exhibit lists
"Not Applicable" in the "Name of DV or LV" column. This is incorrect because providing the DV name ensures the error message is displayed contextually next to the field rather than as a generic page-level error, improving the user experience.
Why other options are incorrect:
* Option A:The LOB column is used for filtering, reporting, and release management. Even if the rule logic checks the policy type, the LOB column is required metadata and should not be removed.
* Option B:While the first requirement (the calculation) lacks a DV name (which it should have), it is a Business Rule(assignment), not a validation. Therefore, it doesnotgenerate an error or warning message for the user, so the second part of Option B is incorrect.
* Option E:The "Rules" column is exactly where the calculation logic (Date of Loss - Date of Birth) belongs. The developer needs this information to implement the automation.
NEW QUESTION # 34
Succeed Insurance has a strategic initiative to change auto insurance into a pay-as-you-drive model... When claims are processed, claimants must provide the log from the application for the date of incident. The log's details are essential to validation and analysis of the monitoring system's activity at the time of the incident.
Without the application log, claims should not be processed to indemnification.
Executives say the implementation team must maintain the base product functionality where appropriate and only change those things essential to the success of the initiative...
Which two requirements are in scope based on the guiding principles? (Choose two.)
Answer: A,B
Explanation:
When defining scope based on specific strategic initiatives and guiding principles (such as "only change those things essential"), the Business Analyst must map requirements directly to the stated business rules and critical success factors.
* Requirement D (Log Intake):The scenario explicitly states:"The log's details are essential to validation and analysis... claimants must provide the log."Option D directly captures this by requiring the log to be received, reviewed, and attached. This is the core data intake requirement.
* Requirement C (Validation Rule):The scenario states:"Without the application log, claims should not be processed to indemnification."Option C directly maps to this business rule. It utilizes base product capabilities (Validation Rules) to enforce the "No Log, No Pay" constraint, ensuring the initiative's security and validity.
Why other options are incorrect:
* Option B (OEM Integration):The scenario mentions leveraging integration "where possible," but creates a requirement for "application logs," not direct integration with "top five vehicle manufacturers." Adding a rigid schedule ("one integration every 30 days") is a high-cost, high- complexity constraint that contradicts the principle of maintaining base functionality and minimizing cost/maintenance unless explicitly required.
* Option A (Mileage):While mileage is part of the concept, theessentialrequirement described for the claim process is thevalidation of the logfor the incident. Tracking mileage is secondary to the critical path of validating the accident data via the log.
NEW QUESTION # 35
......
Our company has been working on the preparation of ClaimCenter-Business-Analysts study materials, and now has successfully helped tens of thousands of candidates around the world to pass the exam. As a member of the group who are about to take the ClaimCenter-Business-Analysts Exam, are you worried about the difficulties in preparing for the exam? Maybe this problem can be solved today, if you are willing to spend a few minutes to try our ClaimCenter-Business-Analysts study materials.
ClaimCenter-Business-Analysts Brain Exam: https://www.newpassleader.com/Guidewire/ClaimCenter-Business-Analysts-exam-preparation-materials.html
P.S. Free & New ClaimCenter-Business-Analysts dumps are available on Google Drive shared by NewPassLeader: https://drive.google.com/open?id=1xElDDWvep7VDKCFYPBIIYeVuLCxznEgA