2026 Die neuesten ZertFragen IIA-CIA-Part3 PDF-Versionen Prüfungsfragen und IIA-CIA-Part3 Fragen und Antworten sind kostenlos verfügbar: https://drive.google.com/open?id=1zSLoEBf2Xr1f-f-BhnkKGSD68nSyHyB8
ZertFragen ist eine Website voller Zuversicht. Die IT-Profis von ZertFragen widmen sich der Studie der vielfältigen IT-Zertifizierungsprüfungen, um die Effektivität der Erfolg der IIA IIA-CIA-Part3 Zertifizierungsprüfungen zu verbessern. Solange Sie einmal ZertFragen Unterlagen probieren, wollen Sie unbedingt sie wieder benutzen, weil wir ZertFragen nicht nur Ihnen die besten IIA IIA-CIA-Part3 Zertifizierungsunterlagen, sondern auch den besten Service anbieten. Wenn Sie irgendwelche Meinungen haben, senden Sie bitte ihre Vorschläge an uns per E-Mail. Wir hoffen, wir helfen Kadidaten Erfolg machen und auch bieten den besten Service.
Die IIA-CIA-Part3 Prüfung ist eine herausfordernde und anspruchsvolle Zertifizierungsprüfung, die darauf ausgelegt ist, das Wissen und die Fähigkeiten von Personen zu testen, die an einer Karriere im internen Audit interessiert sind. Ein erfolgreiches Bestehen dieser Prüfung ist ein entscheidender Schritt in der Erlangung der CIA-Bezeichnung und wird von Arbeitgebern auf der ganzen Welt hoch geschätzt. Mit der richtigen Vorbereitung und Studium können Kandidaten diese Prüfung selbstbewusst angehen und ihre beruflichen Ziele erreichen.
>> IIA-CIA-Part3 Prüfungsinformationen <<
Es ist eine weise Wahl, sich an der IIA IIA-CIA-Part3 Zertifizierungsprüfung zu beteiligen. Mit dem IIA IIA-CIA-Part3 Zertifikat werden Ihr Gehalt, Ihre Stelle und auch Ihre Lebensverhältnisse verbessert werden. Es ist doch nicht so einfach, die IIA IIA-CIA-Part3 Zertifizierungsprüfung zu bestehen. Sie nehmen viel Zeit und Energie in Anspruch, um Ihre Fachkenntnisse zu konsolidieren. ZertFragen ist eine spezielle Schulungswebsite, die Schulungsprogramme zur IIA IIA-CIA-Part3 (Internal Audit Function) Zertifizierungsprüfung bearbeiten. Sie können zuerst die Demo zur IIA IIA-CIA-Part3 Zertifizierungsprüfung im Internet als Probe kostenlos herunterladen, so dass Sie die Glaubwürdigkeit unserer Produkte testen können. Normalerweise werden Sie nach dem Probieren unserer Produkte Vertrauen in unsere Produkte haben.
Die IIA-CIA-Part3 Zertifizierungsprüfung wird von Arbeitgebern sehr geschätzt, da sie die Fähigkeit eines Kandidaten zeigt, Geschäftskonzepte auf den internen Prüfungsprozess anzuwenden. Der Besitz dieser Zertifizierung kann internen Prüfern helfen, ihre Karriere voranzutreiben und ihr Einkommenspotenzial zu erhöhen. Es demonstriert auch ein Engagement für die berufliche Entwicklung und die Bereitschaft, auf dem neuesten Stand der Branchentrends und Best Practices zu bleiben.
Die IIA-CIA-Part3 Prüfung ist eine umfassende Prüfung, die entworfen wurde, um das Wissen des Kandidaten in den Geschäftsgrundsätzen und -konzepten zu messen, die für interne Prüfungsprofis unerlässlich sind. Es ist eine anspruchsvolle Prüfung, die vom Kandidaten ein tiefes Verständnis verschiedener Geschäftsbereiche erfordert. Daher sollten Personen, die eine Karriere in der internen Prüfung anstreben, in Erwägung ziehen, die IIA-CIA-Part3 Prüfung abzulegen, um ihre professionelle Anerkennung und Karriereaussichten zu verbessern.
49. Frage
At December 31, Year 1, an entity had the following equity accounts: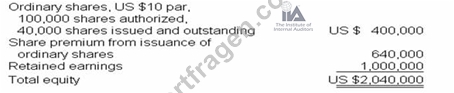
Each of the 40,000 ordinary shares outstanding was issued at a price of US $26. On January 2, Year 2, 2,000 shares were reacquired for US $30 per share. The cost method is used in accounting for these treasury shares. Which of the following correctly describes the effect of the acquisition of the treasury shares?
Antwort: A
Begründung:
Using the cost method, the journal entry to record the acquisition of the treasury shares includes a debit to treasury shares for US $60,000. The balance of the treasury shares account is classified as a contra equity item. Thus, the acquisition of the treasury shares reduces total equity by US $600002.000 shares x $30).
50. Frage
Which of the following statements is true regarding change management?
Antwort: D
Begründung:
Change management is a structured approach to transitioning individuals, teams, and organizations from a current state to a desired future state while minimizing risk and disruption.
* Definition of Change Management:
* Change management ensures that all modifications to IT systems, processes, and applications are controlled and documented.
* As per the IIA GTAG on Change Management, an effective change management process should be repeatable, defined, and predictable to reduce errors and system failures.
* Why Change Management Must Be Structured?
* Uncontrolled changes increase risks such as security vulnerabilities, data loss, and system downtime.
* Best practices (e.g., ITIL, COBIT) require organizations to follow a consistent change management process to protect the production environment.
* A structured approach includes:
* Documenting change requests
* Testing in non-production environments
* Gaining approvals before deployment
* Why Not Other Options?
* A. The degree of risk associated with a proposed change determines whether the change request requires authorization:
* All changes should require authorization, not just high-risk ones.
* B. Program changes generally are developed and tested in the production environment:
* Changes should never be tested in production due to risk exposure. Best practice is to test in a development or staging environment first.
* C. Changes are only required by software programs:
* Change management applies broadly to IT infrastructure, business processes, security protocols, and governance frameworks, not just software.
* IIA GTAG - Change Management Controls
* COBIT 2019 - Change Management Best Practices
* ITIL Change Management Framework
* IIA Standard 2120 - Risk Management
Step-by-Step Justification:IIA References:Thus, the correct and verified answer is D. To protect the production environment, changes must be managed in a repeatable, defined, and predictable manner.
51. Frage
Which of the following statements is true regarding an investee that received a dividend distribution from an entity and is presumed to have little influence over the entity?
Antwort: B
Begründung:
Accounting Treatment for Investments with Little Influence:
When an investee has little or no influence over an entity, it uses the cost method (or fair value method, if applicable) to account for the investment.
Under the cost method, cash dividends received are recorded as dividend revenue rather than adjusting the investment account.
IIA Standard 2120 - Risk Management:
Internal auditors must ensure that financial reporting aligns with applicable accounting standards.
Applicable Accounting Standards:
IFRS 9 (Financial Instruments) and U.S. GAAP (ASC 320 - Investments in Equity Securities) state that dividends received should be recognized as income in the period received.
A). The cash dividends received increase the investee investment account accordingly. (Incorrect) This applies to the equity method, used when an entity has significant influence (usually 20-50% ownership).
Under the cost method, dividend income is recognized as revenue, not as an increase in the investment account.
B). The investee must adjust the investment account by the ownership interest. (Incorrect) Adjusting the investment account for ownership percentage is a feature of the equity method, not the cost method.
C). The investment account is adjusted downward by the percentage of ownership. (Incorrect) A downward adjustment only occurs under the equity method when dividends exceed earnings, indicating a return of capital.
Under the cost method, dividends are recorded as revenue.
Explanation of Answer Choice D (Correct Answer):Explanation of Incorrect Answers:Conclusion:When an investee has little influence, dividends are recorded as revenue (Option D), following IFRS 9 and U.S. GAAP standards.
IIA References:
IIA Standard 2120 - Risk Management
IFRS 9 - Financial Instruments
U).S. GAAP ASC 320 - Investments in Equity Securities
52. Frage
While reviewing the contracts for a large city, the internal auditor learns that the organization contracted to perform trash collection is paid based on the number of bins emptied each week As a result, the city has minimal control over payments Which of the following actions should the auditor recommend to give the city greater control over payments?
Antwort: D
53. Frage
A company purchased US $50,000 worth of office supplies on January 1st and had US $15,000 of office supplies still on hand at year-end. If the initial purchase of supplies entry on January 1st was to debit office supplies expense and to credit cash for US $50,000 the adjusting entry on December 31 will be:
Antwort: B
Begründung:
Because the initial entry recorded the entire purchase to a nominal account. the year-end adjusting entry must debit a prepaid asset to reflect the remaining supplies on hand of US $15.000. The adjusting entry must also credit reduce) expenses for the US $15.000 of supplies that were not used during the period.
54. Frage
......
IIA-CIA-Part3 Prüfungsfrage: https://www.zertfragen.com/IIA-CIA-Part3_prufung.html
P.S. Kostenlose und neue IIA-CIA-Part3 Prüfungsfragen sind auf Google Drive freigegeben von ZertFragen verfügbar: https://drive.google.com/open?id=1zSLoEBf2Xr1f-f-BhnkKGSD68nSyHyB8