P.S. Free 2026 CIPS L4M2 dumps are available on Google Drive shared by TestPDF: https://drive.google.com/open?id=1MDJZSa3gz9R8yZYFQ2cn5l03wDXAJNlN
Our L4M2 exam guide can stand the test of market as well as customers of various needs with passing rate up to 98 to 100 percent, which is a strong proof that attest to their efficacy. OurL4M2 practice materials can provide the evidence of your working proficiency, and the high-efficiency of them are provided by our company can effectively advance your pace of making progress and speed up your pace of reviving it. So our L4M2 Practice Engine is your ideal choice.
| Section | Objectives |
|---|---|
| Understand how to develop a business case for requirements to be sourced from external suppliers | - Analyse how market factors affect procurement |
| Understand the use of specifications in procurement and supply | |
| Understand market management in procurement and supply | - Contrast direct costs and indirect costs
|
By using TestPDF L4M2 exam questions, you will be able to understand the real exam L4M2 scenario. It will help you get verified L4M2 answers and you will be able to judge your L4M2 preparation level for the L4M2 exam. More importantly, it will help you understand the real L4M2 exam feel. You will be able to check the real exam scenario by using this specific L4M2 Exam PDF questions. Our CIPS experts are continuously working on including new L4M2 questions material and we provide a guarantee that you will be able to pass the L4M2 exam on the first attempt.
NEW QUESTION # 285
XYZ Ltd is a large supermarket chain which operates mainly in the UK and Europe. Their custom-ers are increasingly concerned about sustainability. Therefore, procurement manager is required to source the products from suppliers who have good environmental performance. Which of the fol-lowing can be an assurance that the supplier has procedures and policies to enhance its environmental performance?
Answer: B
Explanation:
ISO 9001:2015 specifies requirements for a quality management system.
ISO 14001:2015 specifies the requirements for an environmental management system that an or-ganization can use to enhance its environmental performance. ISO 14001:2015 is intended for use by an organization seeking to manage its environmental responsibilities in a systematic manner that contributes to the environmental pillar of sustainability.
ISO 22716:2007 gives guidelines for the production, control, storage and shipment of cosmetic products.
These guidelines cover the quality aspects of the product, but as a whole do not cover safety aspects for the personnel engaged in the plant, nor do they cover aspects of protection of the environment.
ISO 13485:2016 specifies requirements for a quality management system where an organization needs to demonstrate its ability to provide medical devices and related services that consistently meet customer and applicable regulatory requirements.
NEW QUESTION # 286
An IT category buyer wishes to include social and environmental criteria within a supplier specification. The focus is on the avoidance of hardware manufacturing inputs that have been derived from ' conflict minerals ' , e.g. from politically unstable areas. Is this the right approach?
Answer: C
Explanation:
Sustainability and ethical sourcing are now integral to specifications, especially in sectors like IT procurement, where the use of conflict minerals is a known issue.
The CIPS L4M2 Study Guide, Chapter 1: Developing Specifications, states:
"Including environmental and ethical criteria in specifications helps organisations demonstrate corporate social responsibility and enhances their reputation with stakeholders and customers." Assessment of options:
* A. Preventing innovation - Incorrect. Ethical requirements don't prevent innovation; they guide it responsibly.
* B. Breach of competition laws - No. Ethical sourcing does not violate competition law as long as all suppliers are evaluated fairly using published criteria.
* C. Enhances brand reputation - Correct. Ethical practices (e.g., avoiding conflict minerals) demonstrate corporate responsibility and improve brand image.
* D. Achieving lowest cost - Ethical sourcing often prioritises responsible practices over lowest cost.
Correct answer: C
CIPS Study Guide Reference:
* Module: L4M2 - Defining Business Needs
* Chapter 1: Specification Development
* Topic: Ethical and environmental considerations in specifications
NEW QUESTION # 287
Which of the following positively affects a buyer's company cash flow? Select TWO that apply:
Answer: A,C
Explanation:
Detailed Explanation:
* A (Customer payment upon purchase): Immediate payments improve cash flow.
* D (Loan): Loans provide cash inflow, though they may increase liabilities.Options like supplier payment on receipt (C) negatively impact cash flow, and sales promotions (B) may increase expenses.
Reference: CIPS Level 4, Financial Management in Procurement.
NEW QUESTION # 288
Which of the following can cause overhead variance? Select TWO that apply:
Answer: A,B
Explanation:
Overhead variances arise when the actual overhead costs incurred differ from the expected amounts. Managers want to understand the reasons for these differences, and so should consider computing one or more of the overhead variances described below. Each of these variances applies to a different aspect of overhead expenditures. It is not necessary to calculate these variances when a manager cannot influence their outcome.
Fixed Overhead Spending Variance
The fixed overhead spending variance is the difference between the actual fixed overhead expense incurred and the budgeted fixed overhead expense. An unfavorable variance means that actual fixed overhead expenses were greater than anticipated. The formula for this variance is:
Actual fixed overhead - Budgeted fixed overhead = Fixed overhead spending variance The amount of expense related to fixed overhead should (as the name implies) be relatively fixed, and so the fixed overhead spending variance should not theoretically vary much from the budget.
Fixed Overhead Volume Variance
The fixed overhead volume variance is the difference between the amount of fixed overhead actually applied to produced goods based on production volume, and the amount that was budgeted to be applied to produced goods. For example, a company budgets for the allocation of $25,000 of fixed overhead costs to produced goods at the rate of $50 per unit produced, with the expectation that 500 units will be produced. However, the actual number of units produced is 600, so a total of $30,000 of fixed overhead costs are allocated. This creates a fixed overhead volume variance of $5,000.
Variable Overhead Efficiency Variance
The variable overhead efficiency variance is the difference between the actual and budgeted hours worked, which are then applied to the standard variable overhead rate per hour. The formula is:
Standard overhead rate x (Actual hours - Standard hours)
= Variable overhead efficiency variance
A favorable variance means that the actual hours worked were less than the budgeted hours, resulting in the application of the standard overhead rate across fewer hours, resulting in less expense being incurred. However, a favorable variance does not necessarily mean that a company has incurred less actual overhead, it simply means that there was an improvement in the allocation base what was used to apply overhead.
Variable Overhead Spending Variance
The variable overhead spending variance is the difference between the actual and budgeted rates of spending on variable overhead. The variance is used to focus attention on those overhead costs that vary from expectations. The formula is:
Actual hours worked x (Actual overhead rate - standard overhead rate)
= Variable overhead spending variance
A favorable variance means that the actual variable overhead expenses incurred per labor hour were less than expected.
In the study guide, CIPS splits overhead variance into volume and expenditure variance. They can be understood as variable and fixed overhead variance respectively.
Reference:
- CIPS study guide page 59
- What are overhead variances? - AccountingTools
LO 1, AC 1.4
NEW QUESTION # 289
When devising a business case for purchasing a new copier, Maria analyses its whole-life costs as following: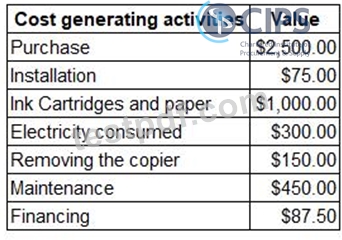
Though cost generating activities are identified, she has not categorised the costs. What is the total value of copier's end of life costs?
Answer: B
Explanation:
Life cycle costing is a key asset management tool that takes into account the whole of life implications of planning, acquiring, operating, maintaining and disposing of an asset.
The process is an evaluation method that considers all ownership and management costs. These include;
- Concept and definition;
- Design and development;
- Manufacturing and installation;
- Maintenance;
- Support services; and
- Retirement, remediation and disposal costs.
End of life costs often comprise of decommissioning, removing and disposal costs. In the copier scenario, the end of life costs equal to removal cost, which is $150.
Reference:
- Life Cycle Cost Guidelines (dlgsc.wa.gov.au)
- CIPS study guide page 36-40
LO 1, AC 1.2
NEW QUESTION # 290
......
The majority of people encounter the issue of finding extraordinary CIPS L4M2 exam dumps that can help them prepare for the actual CIPS L4M2 Exam. They strive to locate authentic and up-to-date CIPS L4M2 practice questions for the Defining Business Needs exam, which is a tough ask.
Valid L4M2 Test Sims: https://www.testpdf.com/L4M2-exam-braindumps.html
BTW, DOWNLOAD part of TestPDF L4M2 dumps from Cloud Storage: https://drive.google.com/open?id=1MDJZSa3gz9R8yZYFQ2cn5l03wDXAJNlN