CSI AFP-Exam-1認定資格試験の難しさなので、我々サイトAFP-Exam-1であなたに適当する認定資格試験問題集を見つけるし、本当の試験での試験問題の難しさを克服することができます。当社はCSI AFP-Exam-1認定試験の最新要求にいつもでも関心を寄せて、最新かつ質高い模擬試験問題集を準備します。また、購入する前に、無料のPDF版デモをダウンロードして信頼性を確認することができます。
| Section | Weight | Objectives |
|---|---|---|
| Technical Competencies | 84% | - Estate Planning - Retirement Planning - Risk Management and Insurance - Tax Planning - Investment Planning - Asset and Liability Management |
| Enabling Competencies | 16% | - Professional Conduct and Regulatory Compliance - Client Relationship and Practice Management |
我々は受験生の皆様により高いスピードを持っているかつ効率的なサービスを提供することにずっと力を尽くしていますから、あなたが貴重な時間を節約することに助けを差し上げます。Jpexam CSIのAFP-Exam-1試験問題集はあなたに問題と解答に含まれている大量なテストガイドを提供しています。インターネットで時勢に遅れないAFP-Exam-1勉強資料を提供するというサイトがあるかもしれませんが、Jpexamはあなたに高品質かつ最新のCSIのAFP-Exam-1トレーニング資料を提供するユニークなサイトです。Jpexamの勉強資料とCSIのAFP-Exam-1に関する指導を従えば、初めてCSIのAFP-Exam-1認定試験を受けるあなたでも一回で試験に合格することができます。
質問 # 99
Richard reviewed his divorce settlement from his partner Alex with his advisor Maria. He is deciding between providing a lump sum spousal support payment of $60,000 or making monthly payments. If Richard's income is $200,000 and Alex's income is $40,000, what should Maria advise Richard about the tax implications for both Richard and Alex in regard to the lump sum payment?
正解:D
解説:
Maria should explain that a lump-sum spousal support payment is generally not deductible to Richard and not taxable to Alex. The tax treatment differs from qualifying periodic spousal support paid under a written agreement or court order, which may be deductible to the payer and taxable to the recipient. A lump-sum settlement is usually treated as a capital or property settlement rather than periodic support for income-tax purposes. Therefore, Richard remains taxable on his full $200,000 of income, and Alex is taxable only on Alex's own earned income of $40,000, ignoring other facts. Options A, B, and C incorrectly allow Richard a deduction for all or part of the lump sum or tax Alex on the lump sum. The planner should advise them to obtain legal and tax advice before structuring support because payment form materially affects after-tax cost.
Study Guide focus: spousal support, lump-sum payments, deductibility, taxable income, and divorce cash- flow planning.
質問 # 100
Consider the following information for a client's portfolio: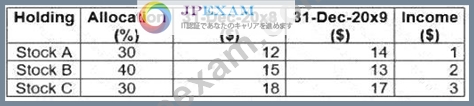
What is the annual rate of return for this portfolio?
正解:A
解説:
The portfolio return must combine price change and income for each holding, then weight each holding by its allocation. Stock A rises from $12 to $14 and pays $1 of income, producing a return of ($14 + $1 - $12) / $12
= 25%. Stock B falls from $15 to $13 but pays $2, producing a 0% total return. Stock C falls from $18 to $17 and pays $3, producing ($17 + $3 - $18) / $18 = 11.11%. Applying the allocation weights gives 30% × 25%, plus 40% × 0%, plus 30% × 11.11%, which is approximately 10.8%. The answer is not based only on market value movement and not on a simple average of the three returns. AFP investment calculations require total return and allocation weighting. Study Guide focus: portfolio return, income return, capital return, weighted averages, and performance measurement. This is why the answer is a weighted total-return figure, not a yield figure or a price-only performance measure.
質問 # 101
Camila's firm recently issued their client, Shawn, an investment management fee summary on his non- registered investment portfolio for $5,000 in carrying charges. Shawn's federal tax rate is 29% and his provincial tax rate is 15%. What will be Shawn's tax savings on this investment management fee?
正解:D
解説:
Shawn's investment management fee produces tax savings of $2,200. The $5,000 fee is a carrying charge related to a non-registered investment portfolio, and such fees may be deductible when they meet the tax rules. His combined marginal tax rate is 44%, calculated as 29% federal plus 15% provincial. Multiplying
$5,000 by 44% gives $2,200. Option A uses only the provincial tax rate. Option D uses only the federal tax rate. Option C ignores the deductibility of eligible investment counsel or management fees in a taxable account. The same fee would not have the same treatment if it related to a registered account such as an RRSP or TFSA. The planner should ensure that the fee summary properly identifies deductible carrying charges and that Shawn's tax preparer applies the deduction correctly. Study Guide focus: carrying charges, non-registered investment fees, marginal tax rates, deductibility, and tax savings. The tax saving should be shown as a reduction in tax payable, not as a reimbursement of the full fee.
質問 # 102
A client wants to increase net worth by identifying spending reductions and increasing monthly surplus.
Which document is most useful for this purpose?
正解:D
解説:
Expense control is a cash flow problem. A net worth statement shows assets, liabilities, and net worth at a point in time, but it does not explain where monthly income is going. A current cash flow statement identifies inflows and outflows, while a budget converts that information into a forward-looking spending and savings plan. Option A is incomplete because the balance sheet can show that debt exists but not which behaviours are creating or reducing surplus. Option C relates to estate transfer, not spending control. Option D governs investment objectives and constraints; it does not normally capture household expense categories. To increase net worth, the planner must connect the income statement and balance sheet: reduce unnecessary outflows, direct surplus to debt repayment or savings, and measure progress through updated net worth statements. The practical planning sequence is diagnose cash flow, set a budget, automate surplus allocation, and review outcomes. References/topics: cash flow statement, budgeting, net worth improvement, expense management.
質問 # 103
Kendrick, age 55, owns a successful small business, ZXC Inc., valued at $800,000. Kendrick has extensive savings outside of the business and would like to pass the company onto his son at some point in the future.
Kendrick expects the business to increase in value $25,000 per year. If Kendrick decides to use an estate freeze to reduce the amount of taxes he will be required to pay, his financial planner should recommend that he implement the estate freeze at which point in relation to gifting the business to his son?
正解:B
解説:
The estate freeze should be implemented immediately if Kendrick expects the business to continue appreciating. The purpose of the freeze is to lock in the current value of the owner's interest, usually by exchanging growth shares for fixed-value preferred shares, while future growth accrues to the successor generation or a trust. Waiting until the gift date, one month before the gift, or death allows additional appreciation to remain taxable to Kendrick. Since the company is already valued at $800,000 and expected to grow by $25,000 per year, every year of delay increases the value exposed to future tax in Kendrick's estate.
A freeze also needs legal and tax design, including valuation, share terms, control, income needs, and succession intentions. Among the options, immediate implementation best achieves the objective of reducing future tax growth in his hands. Study Guide focus: estate freezes, business succession, preferred shares, future growth transfer, and tax minimization.
質問 # 104
......
Jpexamが提供したCSIのAFP-Exam-1トレーニング資料を利用したら、CSIのAFP-Exam-1認定試験に受かることはたやすくなります。Jpexamがデザインしたトレーニングツールはあなたが一回で試験に合格することにヘルプを差し上げられます。 JpexamのCSIのAFP-Exam-1トレーニング資料即ち問題と解答をダウンロードする限り、気楽に試験に受かることができるようになります。まだ困っていたら、我々の試用版を使ってみてください。ためらわずに速くあなたのショッピングカートに入れてください。でないと、絶対後悔しますよ。
AFP-Exam-1受験資料更新版: https://www.jpexam.com/AFP-Exam-1_exam.html