PF1 training materials have now provided thousands of online test papers for the majority of test takers to perform simulation exercises, helped tens of thousands of candidates pass the PF1 exam, and got their own dream industry certificates PF1 exam questions have an extensive coverage of test subjects and have a large volume of test questions, and an online update program. PF1 Study Material has a high quality service team. First of all, the authors of study materials are experts in the field. They have been engaged in research on the development of the industry for many years, and have a keen sense of smell for changes in the examination direction.
| Section | Weight | Objectives |
|---|---|---|
| Record of Employment (ROE) | 20% | - Submission and deadlines
|
| Communication and Compliance | 10% | - Stakeholder communication
|
| Termination and Special Payments | 30% | - Leaves and absences
|
| Individual Pay Calculations | 40% | - Regular earnings
|
>> PF1 Reliable Study Guide <<
Customizable Payroll Fundamentals 1Exam (PF1) exam conditions in such a way that you can create your desired PF1 exam with pre-determined questions and exam duration. You will be able to see instant results after going through the PF1 Practice Exam To confirm the product licence. For customer satisfaction, TorrentVCE has also designed a Payroll Fundamentals 1Exam (PF1) demo version so the candidate can assure the reliability of the National Payroll Institute PDF Dumps.
NEW QUESTION # 63
A retiring allowance includes:
Answer: D
Explanation:
The CRA defines a retiring allowance (also called severance pay) as an amount paid to an employee when or after they retire or lose their job, in recognition of long service or for the loss of office or employment. This matches option A.
The other options are specifically not retiring allowances under CRA guidance. The CRA states a retiring allowance does not include salary, wages, bonuses, or overtime, which rules out bonus or incentive pay and accumulated overtime. The CRA also states it does not include payments for accumulated vacation leave not taken before retirement, which rules out vacation pay.
This classification matters in payroll because retiring allowances have distinct rules: for example, they are not subject to CPP or EI deductions, and part of a retiring allowance may be eligible for direct transfer to an RRSP
/RPP under special rules (based on pre-1996 service).
NEW QUESTION # 64
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)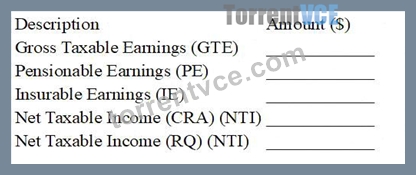
STATUTORY DEDUCTIONS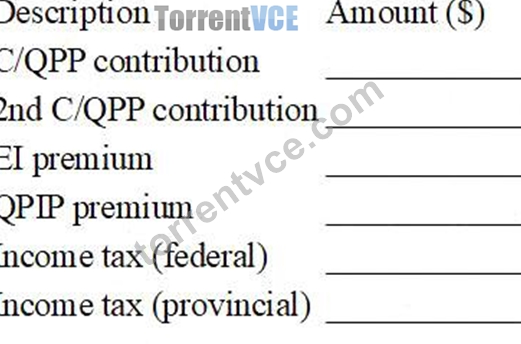
OTHER DEDUCTIONS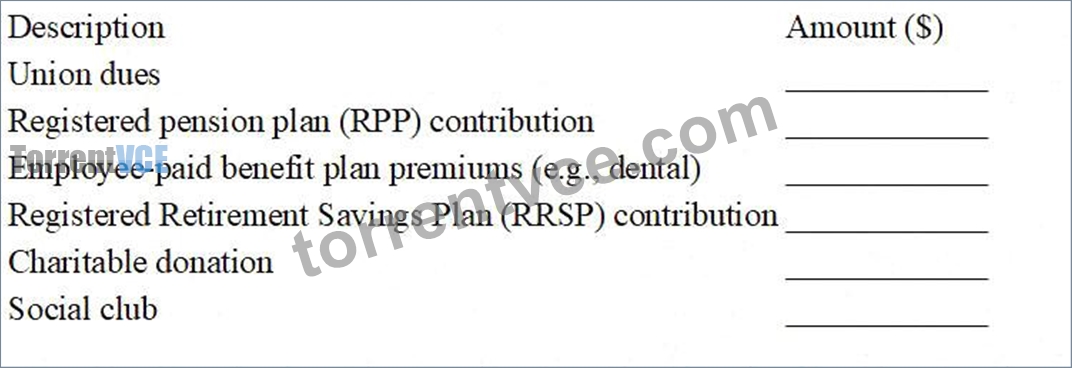
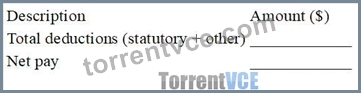
Given Data (Reference)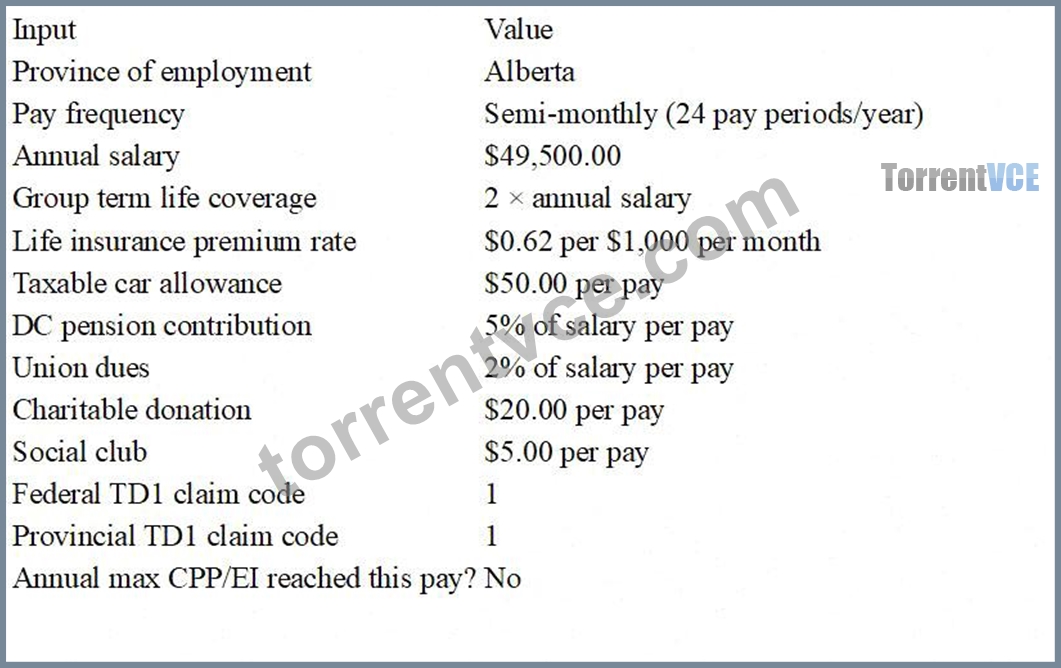
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 65
Expense reimbursements are:
Answer: D
Explanation:
An expense reimbursement is paid to repay an employee for actual business expenses the employee incurred while performing their job (for example, meals while travelling on business, supplies purchased for work, etc.). CRA's taxable benefits guidance distinguishes reimbursements from allowances: an allowance is usually a predetermined amount paid without the employee having to support the expense with receipts, while a reimbursement is tied to actual costs.
That distinction matters because reimbursements are generally not compensation for work performed (so they are not "earnings"), and they are not "benefits" in the sense of a good or service provided by the employer (though CRA notes that benefits can include reimbursements of personal expenses-so payroll must still ensure the reimbursement is for business use and properly supported).
Option A correctly describes reimbursements. Option B is typically an allowance (for example, a vehicle allowance for using personal property). Option C describes earnings (wages/salary). Option D describes benefits (value of something provided or paid for on the employee's behalf).
NEW QUESTION # 66
What information is required to calculate thestandby charge, thereduced standby charge, and theoperating cost benefitfor a company-owned automobile?
Answer: B
Explanation:
CRA's automobile benefit calculations require multiple data points because there are usuallytwo components thestandby charge(vehicle availability) and theoperating expense benefit(personal driving where the employer pays operating costs). CRA's guidance on employer-provided automobiles explains that standby charge calculations use the automobile'scost (capital cost) including applicable taxesand the time the vehicle wasavailableto the employee, while the reduced standby charge and operating benefit depend on kilometres drivenand the split betweenbusiness and personal use.
To determine whether areduced standby chargeapplies, you need availability plusbusiness-use requirements(which are evidenced through total/business kilometres). To calculate the operating expense benefit, you needpersonal kilometres(often derived from total kilometres minus business kilometres) or detailed personal km directly.
Therefore, the complete and correct set of required inputs is:capital cost (with sales tax), availability, total kilometres, business kilometres, and personal kilometres-which is optionD.
NEW QUESTION # 67
When would a Record of Employment be issued for an employee paid mainly by commission?
Answer: A
Explanation:
Commission employees have a specific ROE rule. Service Canada's ROE Guide explains that for employees whose earnings consist mainly of commissions, an interruption of earnings occurs only when the employment contract is terminated-unless the employee stops working due to specified EI-related reasons such as illness
/injury/quarantine, maternity/pregnancy, parental leave, or compassionate care/family caregiver leaves.
This means the usual 7-day rule (7 consecutive days with no work and no insurable earnings) generally does not trigger an interruption of earnings for mainly-commission employees as long as the contract continues. In other words, if the employee stops working for reasons like vacation or a leave of absence but remains under contract, Service Canada indicates there is no interruption of earnings and therefore no ROE is issued just because of time without commissions/work.
So the correct choice is when the employment relationship/contract is terminated (option C).
NEW QUESTION # 68
......
In today's society, many people are busy every day and they think about changing their status of profession. They want to improve their competitiveness in the labor market, but they are worried that it is not easy to obtain the certification of PF1. Our study tool can meet your needs. Once you use our PF1 exam materials, you don't have to worry about consuming too much time, because high efficiency is our great advantage. You only need to spend 20 to 30 hours on practicing and consolidating of our PF1 learning material, you will have a good result. After years of development practice, our PF1 test torrent is absolutely the best.
Test PF1 Tutorials: https://www.torrentvce.com/PF1-valid-vce-collection.html