DOWNLOAD the newest FreeDumps Accounting-for-Decision-Makers PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=13oEQ6tthExWzI01v9p46lfRAjNwyGpZs
FreeDumps are supposed to help you pass the Accounting-for-Decision-Makers exam smoothly. Don't worry about channels to the best Accounting-for-Decision-Makers study materials so many exam candidates admire our generosity of offering help for them. Up to now, no one has ever challenged our leading position of this area. The existence of our Accounting-for-Decision-Makers learning guide is regarded as in favor of your efficiency of passing the exam. Over time, our company is becoming increasingly obvious degree of helping the exam candidates with passing rate up to 98 to 100 percent. All our behaviors are aiming squarely at improving your chance of success on Accounting-for-Decision-Makers Exam.
| Section | Objectives |
|---|---|
| Financial Statement Analysis | - Ratio analysis (liquidity, profitability, solvency, efficiency ratios) - Interpreting financial data for decision-making purposes - Horizontal and vertical analysis |
| Budgeting and Planning | - Variance analysis - Master budget components - Operating budgets (sales, production, direct materials, direct labor, overhead) - Financial budgets (cash budget, budgeted income statement, budgeted balance sheet) |
| Financial Accounting Fundamentals | - Understanding the accounting cycle - Accrual vs. cash basis accounting - Preparing financial statements (Income Statement, Balance Sheet, Statement of Cash Flows) - Recording transactions and adjusting entries |
| Decision Making and Performance Evaluation | - Responsibility accounting and performance metrics - Relevant costs for decision making - Capital budgeting techniques (NPV, IRR, Payback Period) - Balanced Scorecard concepts - Make-or-buy and special order decisions |
| Managerial Accounting Concepts | - Cost classification and behavior (fixed, variable, mixed costs) - Cost-Volume-Profit (CVP) analysis - Contribution margin and break-even analysis - Job order and process costing |
>> Valid Accounting-for-Decision-Makers Test Duration <<
In case there are any changes happened to the Accounting-for-Decision-Makers exam, the experts keep close eyes on trends of it and compile new updates constantly so that our Accounting-for-Decision-Makers exam questions always contain the latest information. It means we will provide the new updates of our Accounting-for-Decision-Makers Study Materials freely for you later since you can enjoy free updates for one year after purchase. And you can free download the demos to check it by yourself.
NEW QUESTION # 52
Which information does a balance sheet provide about a company?
Answer: B
Explanation:
A balance sheet shows the company's financial position at a specific point in time , so Option C is correct.
It reports what the business owns (assets), what it owes (liabilities), and usually owners' or stockholders' equity as of a particular date. This is why the balance sheet is often described as a snapshot rather than a report covering a span of time. Authoritative accounting learning materials describe the balance sheet as presenting assets, liabilities, and equity "as of" a date or at a specific moment.
Option A is incorrect because revenues and expenses for a period of time belong to the income statement , not the balance sheet. Option D is incorrect because cash collections and cash expenditures for a period of time are presented in the statement of cash flows . Option B is also incorrect because cash inflows and outflows are not reported only at a single point in time; they are summarized over a period. Therefore, the best answer is the one identifying the balance sheet as a statement of assets and liabilities at a specific point in time .
NEW QUESTION # 53
Match each accounting term with its definition.
Answer options may be used more than once or not at all.
Select your answer from the pull-down list.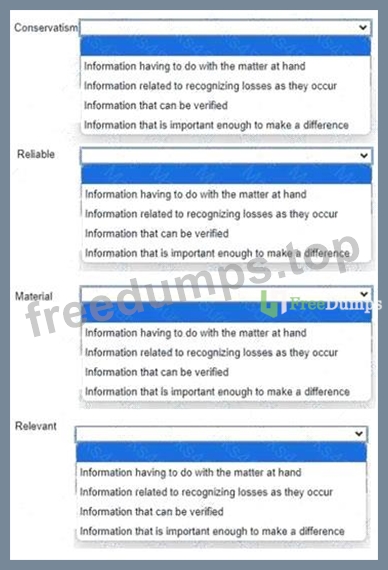
Answer:
Explanation: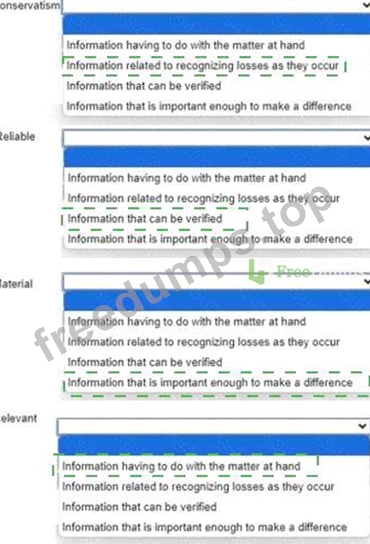
Explanation:
Conservatism - Information related to recognizing losses as they occur
Reliable - Information that can be verified
Material - Information that is important enough to make a difference
Relevant - Information having to do with the matter at hand
These accounting terms describe important qualitative ideas used in financial reporting. Conservatism means accountants should use caution when uncertainty exists, especially by recognizing potential losses sooner rather than delaying them. Reliable information is information that can be supported, confirmed, or verified, which makes it trustworthy for users of financial statements. Material information is significant enough to affect the decisions of investors, creditors, or other users. If leaving it out or misstating it could influence a decision, it is material. Relevant information is information that relates directly to the issue being considered and is useful for decision-making.
These concepts help ensure that accounting information is useful, dependable, and meaningful. Relevance focuses on usefulness, reliability focuses on trustworthiness, materiality focuses on significance, and conservatism focuses on caution under uncertainty. Together, they support better financial statement preparation and interpretation. In this matching question, each term lines up with its most standard accounting definition, so the correct matches are exactly as shown above.
NEW QUESTION # 54
Under the Sarbanes-Oxley Act, which requirement must an accounting firm that audits public companies meet?
Answer: C
Explanation:
The correct answer is B . Section 201 of the Sarbanes-Oxley Act and related SEC rules prohibit registered public accounting firms from providing certain nonaudit services to their audit clients because those services could impair auditor independence. The SEC's rulemaking specifically identifies prohibited services, including internal audit outsourcing , among other restricted nonaudit services.
Option A is incorrect because SOX requires lead audit partner rotation , not mandatory rotation of the entire audit firm after five years. Option C is incorrect because SOX does not impose a blanket ban on advertising by audit firms. Option D is also incorrect because while the audit committee, not management alone, plays a central role in hiring and overseeing the external auditor, the statement as written is not the key audit-firm requirement highlighted by SOX in this context. The most specific and widely tested SOX requirement here is the prohibition on certain nonaudit services to audit clients. This rule protects objectivity by preventing the auditor from effectively reviewing its own consulting or internal audit work. Therefore, Option B is correct.
NEW QUESTION # 55
What are two examples of product costs?
Choose 2 answers.
Answer: A,D
Explanation:
The correct answers are B. Direct labor and D. Raw materials . Product costs are the costs incurred to manufacture or acquire a product that will be sold. In a manufacturing setting, product costs normally include direct materials (raw materials) , direct labor , and manufacturing overhead . Corporate Finance Institute summarizes product costs as including direct material, direct labor, and manufacturing overhead.
Option A. Selling and administrative expenses is incorrect because those are period costs , not product costs. Option C. Period expenses is also incorrect for the same reason. Period costs are expensed in the period incurred and are not attached to inventory production. Lumen Learning similarly distinguishes product costs from period costs by explaining that product costs include direct materials, direct labor, and overhead, while selling and administrative expenses are period costs.
Because the question asks for two examples of costs directly associated with making a product, the best answers are Direct labor and Raw materials . These are core manufacturing inputs and become part of inventory until the goods are sold.
NEW QUESTION # 56
Which overhead cost is associated with batch-level activities?
Answer: C
Explanation:
The correct answer is B. Machine setups . In activity-based costing , batch-level activities are performed each time a batch of goods is processed, regardless of how many units are in that batch. A classic example is the machine setup required before production of a batch can begin. ABC materials commonly identify setup costs as batch-level because the activity occurs per batch rather than per individual unit.
Option A, property taxes , and Option C, factory insurance , are usually considered facility-level or organization-sustaining overhead because they support the factory as a whole rather than a specific batch.
Option D, product engineering wages , is more closely related to product-level activities , since engineering work often supports a particular product line rather than each batch run. Batch-level costs increase with the number of production batches, not necessarily with the number of units produced. Since machine setups are incurred each time a batch is started, they are the standard example of a batch-level overhead cost. Therefore, Option B is the correct answer.
NEW QUESTION # 57
......
We are confident about our WGU Accounting-for-Decision-Makers braindumps tested by our certified experts who have great reputation in IT certification. These Accounting-for-Decision-Makers exam pdf offers you a chance to get high passing score in formal test and help you closer to your success. Valid Accounting-for-Decision-Makers Test Questions can be access and instantly downloaded after purchased and there are free Accounting-for-Decision-Makers pdf demo for you to check.
Latest Accounting-for-Decision-Makers Guide Files: https://www.freedumps.top/Accounting-for-Decision-Makers-real-exam.html
DOWNLOAD the newest FreeDumps Accounting-for-Decision-Makers PDF dumps from Cloud Storage for free: https://drive.google.com/open?id=13oEQ6tthExWzI01v9p46lfRAjNwyGpZs