BTW, DOWNLOAD part of Exam4Labs PF1 dumps from Cloud Storage: https://drive.google.com/open?id=12EYQf8W9BtBNTRTMIXBRiAh-7TmzMXHt
Our company is a professional certificate exam materials provider, and we have occupied in this field for years. Our company is in the leading position in exam materials providing. PF1 exam materials of us have high pass rate, and you can pass it by using them, and money back guarantee for your failure. PF1 Exam Materials have the questions and answers and therefore you can practice the question and check the answers in a quite convenient way. We also offer you free update for one year, and you can get the latest version timely if you buy the PF1 exam dumps from us.
| Section | Objectives |
|---|---|
| Earnings, Deductions, and Taxation | - Deductions and remittances
|
| Payroll Records and Compliance Reporting | - Recordkeeping requirements
|
| Payroll Fundamentals and Compliance Framework | - Payroll system overview in Canada
|
Our website is the first choice among IT workers, especially the ones who are going to take PF1 certification exam in their first try. It is well known that getting certified by PF1 real exam is a guaranteed way to succeed with IT careers. We are here to provide you the high quality PF1 Braindumps Pdf for the preparation of the actual test and ensure you get maximum results with less effort.
NEW QUESTION # 24
A death benefit is a:
Answer: D
Explanation:
The CRA defines a death benefit as the gross amount of any payment made on or after the death of an employee to recognize the employee's service in an office or employment. It can be paid to a surviving spouse
/common-law partner, heir, or the estate.
This is different from amounts the employee already earned before death (for example, regular wages up to the date of death, or vacation pay that was accrued/earned). CRA guidance treats wages and employment income earned up to and including the date of death as amounts to be reported on a T4 slip, not as a death benefit.
It's also different from a life insurance payout from an insurer (which is not an employer-paid "death benefit" for payroll reporting purposes). The payroll impact is that a qualifying death benefit is generally reported as a special payment (often on a T4A), following CRA rules for deductions and reporting of death benefits.
NEW QUESTION # 25
Alyssa is a member of her employer's Defined Contribution Pension Plan. The plan defines the contribution as 3% of the employee's pensionable earnings, with the employer matching the employee's contribution.
Alyssa's pensionable earnings are $3,400.00 per month. Calculate the total payment to be remitted to Alyssa's Defined Contribution Pension Plan each month.
Answer:
Explanation:
$204.00 per month
Explanation:
In a Defined Contribution (DC) pension plan, contributions are calculated as a set percentage of the employee' s pensionable earnings, and the total remittance is usually the sum of the employee deduction plus the employer's matching contribution, based on the plan text. Here, the plan states the employee contributes 3% of pensionable earnings, and the employer matches the employee contribution.
Step 1: Calculate the employee's pension contribution:
3% × $3,400.00 = 0.03 × 3,400.00 = $102.00.
Step 2: Calculate the employer match:
Because the employer matches the employee contribution, the employer contributes $102.00 as well.
Step 3: Total remittance to the plan:
$102.00 (employee) + $102.00 (employer) = $204.00 each month.
From a payroll processing perspective, the employee amount is withheld from gross pay as a payroll deduction according to plan rules, while the employer match is recorded as an employer expense. Payroll remits both amounts to the plan administrator following the plan's remittance schedule, and should reconcile pensionable earnings and contributions to ensure accuracy and compliance with plan terms.
NEW QUESTION # 26
PF1 Exam - Net Pay Calculation (Template Worksheet)
Scenario
Diane Lemay works for Monarch Construction in Alberta and earns an annual salary of $49,500.00, paid on a semi-monthly basis.
The company provides its employees with group term life insurance coverage of two times annual salary and pays a monthly premium of $0.62 per $1,000.00 of coverage.
Diane uses her car to meet with clients on company business and receives a taxable car allowance of $50.00 per pay.
The company has a defined contribution pension plan to which Diane contributes 5% of her salary each pay.
Diane also contributes $20.00 to United Way and has $5.00 deducted for her social club membership each pay. She belongs to a union and pays 2% of her salary in union dues per pay period.
Diane's federal and provincial TD1 claim codes are 1. She will not reach the first Canada Pension Plan or Employment Insurance annual maximums this pay period.
Required: Calculate the employee's net pay, following the order of the steps in the net pay template.
EXHIBIT A - Net Pay Template (Fill in all blanks)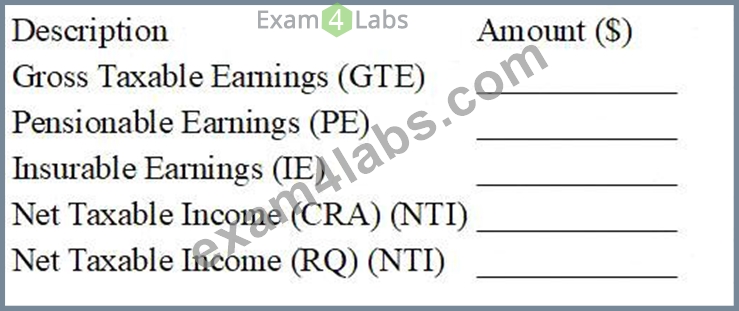
STATUTORY DEDUCTIONS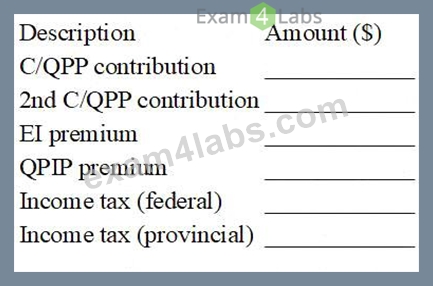
OTHER DEDUCTIONS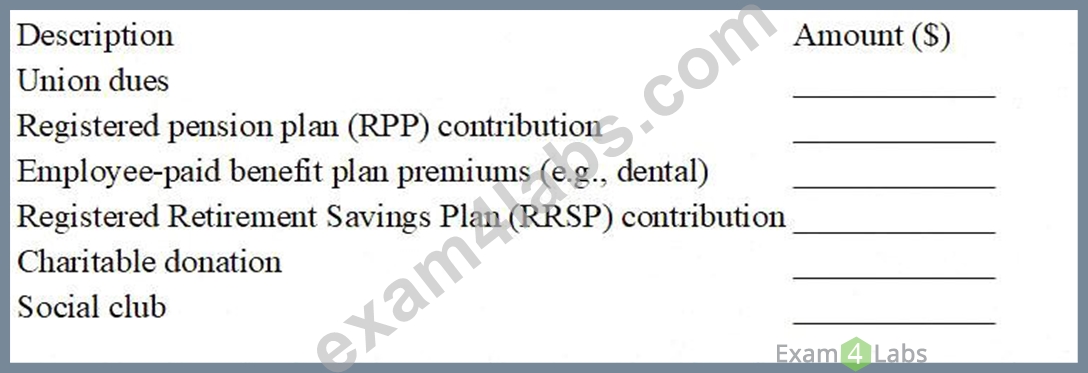
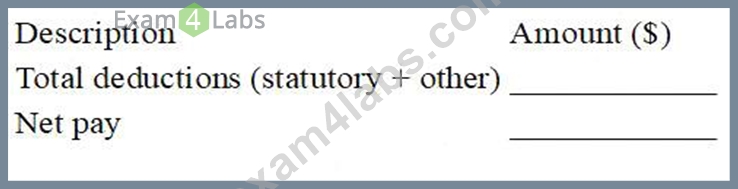
Given Data (Reference)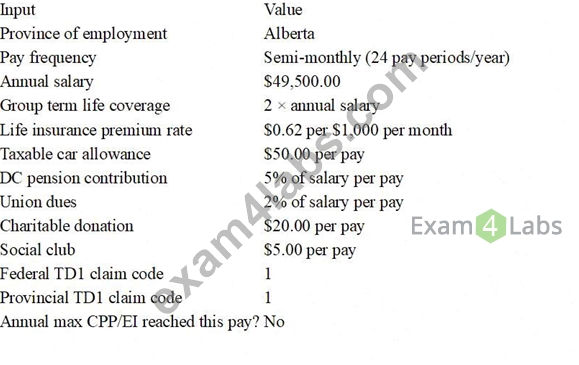
Step 1 - Calculate the employee's gross taxable earnings (GTE) for this pay.
[ _________________________________ ]
Step 2 - Calculate the pensionable earnings (PE).
[ _________________________________ ]
Step 3 - Calculate the insurable earnings (IE).
[ _________________________________ ]
Step 4 - Calculate the net taxable income (CRA) (NTI).
[ _________________________________ ]
Step 5 - Calculate the net taxable income (RQ) (NTI).
[ _________________________________ ]
Step 6 - Calculate Diane's Canada Pension Plan contribution.
[ _________________________________ ]
Step 7 - Calculate Diane's Employment Insurance premium.
[ _________________________________ ]
Step 8 - Calculate Diane's Quebec Parental Insurance Plan premium.
[ _________________________________ ]
Step 9 - Determine Diane's federal income tax.
[ _________________________________ ]
Step 10 - Determine Diane's provincial income tax.
[ _________________________________ ]
Step 11 - Calculate Diane's total deductions (statutory + other).
[ _________________________________ ]
Step 12 - Calculate Diane's net pay.
[ _________________________________ ]
Answer:
Explanation:
See the Explanation part for answer for each step.
Explanation:
Step 1 - Gross Taxable Earnings (GTE)
Salary per pay: 49,500 ÷ 24 = $2,062.50
Taxable car allowance: $50.00
Group term life taxable benefit:
Coverage = 2 × 49,500 = 99,000
Monthly premium = (99,000 ÷ 1,000) × 0.62 = 99 × 0.62 = 61.38
Semi-monthly benefit = 61.38 ÷ 2 = $30.69
GTE = $2,143.19
Step 2 - Pensionable Earnings (PE)
PE = $2,112.50 (2,062.50 + 50.00)
Step 3 - Insurable Earnings (IE)
IE = $2,112.50
Step 4 - Net Taxable Income (CRA) (NTI)
RPP = 5% × 2,062.50 = $103.13
Union dues = 2% × 2,062.50 = $41.25
NTI (CRA) = 2,143.19 # 103.13 # 41.25 = $1,998.81
Step 5 - Net Taxable Income (RQ)
$0.00
Step 6 - CPP (base CPP)
Period exemption = 3,500 ÷ 24 = $145.83
Contributory = 2,112.50 # 145.83 = $1,966.67
CPP = 1,966.67 × 5.95% = $117.02
CPP = $117.02
Step 6B - 2nd CPP (CPP2)
CPP2 = $0.00
Step 7 - EI premium
EI = 2,112.50 × 1.63% = $34.43
EI = $34.43
Step 8 - QPIP
$0.00
Step 9 - Federal income tax (CC1, semi-monthly)
$156.10
Step 10 - Alberta income tax (CC1, semi-monthly)
$73.20
Step 11 - Total deductions
Statutory: 117.02 + 34.43 + 156.10 + 73.20 = $380.75
Other: RPP 103.13 + Union 41.25 + United Way 20.00 + Social club 5.00 = $169.38 Total deductions = $550.13 Step 12 - Net pay Cash pay (salary + car allowance) = 2,062.50 + 50.00 = $2,112.50 Net pay = 2,112.50 # 550.13 = $1,562.37
NEW QUESTION # 27
Bonus and incentive pays are subject to which statutory deductions?
Answer: C
Explanation:
Bonuses and incentives are treated as taxable remuneration, so they are generally subject to the same core statutory deductions as regular earnings: CPP/QPP, EI, and income tax (and in Quebec, QPIP also applies when the remuneration is subject to EI). The CRA specifically notes that you must deduct EI premiums from bonuses/retroactive pay (up to the annual maximum), and the CRA's guidance for bonuses/irregular amounts uses tools (PDOC/formulas) that calculate CPP contributions, EI premiums, and income tax on these payments.
In Quebec payroll, remuneration that is subject to EI premiums is generally also subject to QPIP premiums, so bonuses/incentives that are EI-insurable are typically QPIP-insurable as well.
In the Northwest Territories and Nunavut, there is also a statutory territorial payroll tax that employers must withhold/remit where applicable, and the NWT guidance explicitly lists bonuses as part of employment income subject to payroll tax.
NEW QUESTION # 28
Anne Massy works for Liberty Promotions in Nunavut and is provided with a company-leased automobile.
The automobile was in Anne's possession for 365 days. Of the 34,134 kilometres driven, 15,805 kilometres were for business purposes. The monthly lease cost of the vehicle was $198.60, excluding GST calculated at
5%. Anne requested in writing that Liberty Promotions use the optional operating cost method if all conditions apply. She did not reimburse the company for any of the expenses associated with the automobile.
Calculate Anne's annual automobile taxable benefit.
Answer:
Explanation:
$7,900.10
Explanation:
Anne has both an automobile standby charge (because the car was made available) and an operating expense benefit (because the employer paid operating costs and she did not reimburse).
1) Standby charge (leased auto): Lease cost for standby charge purposes includes GST and excludes insurance.
Monthly lease incl. GST = $198.60 × 1.05 = $208.53.
Standby charge per month = 2/3 × $208.53 = $139.02.
Days available ÷ 30 = 365 ÷ 30 = 12.17, rounded to 12.
Annual standby charge = $139.02 × 12 = $1,668.24.
2) Operating expense benefit: Personal km = 34,134 # 15,805 = 18,329.
Optional method requires the automobile be used primarily (>50%) for business; Anne's business use is under
50%, so the optional method does not apply and the fixed rate must be used.
Fixed rate (2026) = $0.34/km # 18,329 × 0.34 = $6,231.86.
Total taxable benefit = $1,668.24 + $6,231.86 = $7,900.10.
NEW QUESTION # 29
......
Our PF1 practice materials enjoy a very high reputation worldwide. This is not only because our practical materials are affordable, but more importantly, our PF1 practice materials are carefully crafted after years of hard work and the quality is trustworthy. If you are still anxious about getting a certificate, why not try our PF1 practice materials? If you have any questions about our practical materials, you can ask our staff who will give you help.
PF1 Exam Dumps Free: https://www.exam4labs.com/PF1-practice-torrent.html
P.S. Free 2026 National Payroll Institute PF1 dumps are available on Google Drive shared by Exam4Labs: https://drive.google.com/open?id=12EYQf8W9BtBNTRTMIXBRiAh-7TmzMXHt