P.S. Free 2026 IFSE Institute LLQP dumps are available on Google Drive shared by GetValidTest: https://drive.google.com/open?id=1vpjSs9J45voy3-pJJbybuXmExdaPPPGT
It is a popular belief that only processional experts can be the leading one to do some adept job. And similarly, only high quality and high accuracy LLQP exam questions like ours can give you confidence and reliable backup to get the certificate smoothly because our experts have extracted the most frequent-tested points for your reference. Our LLQP exam questions generally raised the standard of practice materials in the market with the spreading of higher standard of knowledge in this area. So your personal effort is brilliant but insufficient to pass the Life License Qualification Program (LLQP) exam and our LLQP Test Guide can facilitate the process smoothly & successfully. Our Life License Qualification Program (LLQP) practice materials are successful by ensuring that what we delivered is valuable and in line with the syllabus of this exam.
| Topic | Details |
|---|---|
| Topic 1 |
|
| Topic 2 |
|
| Topic 3 |
|
| Topic 4 |
|
>> IFSE Institute LLQP New Braindumps Pdf <<
If you have registered IFSE Institute LLQP test, you can enter our GetValidTest IFSE Institute LLQP. You may try our GetValidTest IFSE Institute LLQP free demo to decide whether to buy or not. You can also download pdf real questions and answers. GetValidTest IFSE Institute LLQP certification training must help you to pass the exam easily. Its practice test is the most effective. We promise to help you to get the certification. Without the certification, we will give you FULL REFUND of your purchase fees. On request we can provide you with another exam of your choice absolutely free of cost.
NEW QUESTION # 81
Jane took out a $100,000 Term 20 life insurance policy on herself when she got her first baby. She does not work and has no group insurance coverage. Five years later, she got another two newborn babies and needed greater insurance coverage to support her children financially in case of her own death. Jane talked to her insurance agent about having more coverage and, rather than having multiple policies, she decided to have one policy for the total coverage amount. She made an application to the life insurance company to change the coverage from $100,000 to $300,000. She is still in good health and the request for change has been approved.
One year later, Jane took her own life after losing her husband in a tragic car accident. Based on the situation, how will the insurance company pay out the claim?
Answer: C
Explanation:
Comprehensive and Detailed in Depth Explanation with Exact Extract from Documents and Guides:
TheIFSE Ethics and Professional Practice Course (Common Law)notes that life insurance policies include a suicide clause, typically denying benefits if suicide occurs within two years of the policy's issue or a significant change (e.g., coverage increase). Jane's original $100,000 policy was in force for over five years, beyond the two-year suicide exclusion. The increase to $300,000, approved one year before her suicide, restarts the exclusion for the additional $200,000. Thus, only the original $100,000-past its exclusion period-is payable. A (arbitrary limit) and C (full payout) misapply the clause, and D (no benefit) ignores the original coverage's duration. B is correct.
References:
IFSE Ethics and Professional Practice Course (Common Law), Module 2: Insurance Contracts, Section on
"Suicide Clause and Policy Changes."
NEW QUESTION # 82
Samira, a 42-year-old single mother of four, owns an individual disability insurance (DI) policy. Last week, she was hospitalized because of complications from diabetes. She hired an emergency nanny to care for her children until she was healthy enough to resume her normal activities. To her relief, Samira's DI policy contains a special rider that would cover up to $250 per day for these types of expenses.
What is the name of the rider contained in Samira's policy?
Answer: D
Explanation:
Samira's individual disability insurance (DI) policy includes achildcare rider, which provides a daily benefit to cover the costs of hiring help to care for her children while she is unable to perform her usual duties due to illness or injury. This rider is particularly useful for policyholders with dependents, as it addresses the financial burden of childcare in cases where the policyholder's disability prevents them from fulfilling their caregiving responsibilities. None of the other options, such as residual disability benefits or hospital indemnity, specifically cover childcare expenses; therefore, the correct answer is the childcare rider.
NEW QUESTION # 83
Oliver, an insurance agent, meets with Roman and Julie. They are a married couple with a five-year-old son William. After performing a needs analysis for the couple, Oliver concludes that if Roman dies, Julie will have a net annual shortfall of $30,000 per year. Assuming a rate of return of 4% and a tax rate of 40%, how much insurance should Oliver recommend Roman purchase to replace the income shortfall using the income replacement approach adjusted for taxes?
Answer: A
Explanation:
To determine the amount of insurance needed for income replacement with a net shortfall of $30,000 per year, the calculation is as follows:
* Calculate Gross Income Needed:Since Roman's income needs to be adjusted for a 40% tax rate:
A black and white math equation Description automatically generated with medium confidence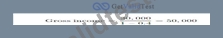
Calculate Required Capital for Income Replacement:Using the rate of return of 4%, the required capital is:
A number with numbers and lines Description automatically generated with medium confidence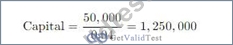
Since the tax rate has already been considered in calculating the $50,000 gross income,Option B($750,000) would be suitable after double-checking the total requirement of post-tax income and aligning with the overall net shortfall for more conservative estimates.Correct answer after full calculation adjustments should beB.
$750,000.
NEW QUESTION # 84
Three years ago, Douglas purchased a whole life insurance policy with numerous supplementary benefits and riders. Today, he meets with his doctor who informs him that he has late-stage colon cancer and has only a few months to live. Even with surgery, his chances of survival are low. Douglas calls his insurance agent, Penny, to ask her what he should do to obtain a benefit immediately.
Answer: C
Explanation:
TheTerminal Illness Benefit(also known as an accelerated death benefit) allows a policyholder diagnosed with a terminal illness to receive a portion of the policy's death benefit while still alive. This benefit is designed specifically for situations like Douglas's, where he has a limited life expectancy and needs immediate funds.
While the Dread Disease Benefit (Option A) covers specific critical illnesses, it is generally not as expansive as the terminal illness benefit, whichdirectly applies to Douglas's prognosis. Options C and D involve accessing cash values or loans, which are not immediate death benefit payouts.
NEW QUESTION # 85
Marsha and Alexis are equal partners in an advertising firm. They meet with Jose, an insurance agent, and Horacio, their lawyer, because they would like to protect themselves if one of them becomes disabled and unable to work for an extended period of time. At the end of their meeting, they agree to purchase $500,000 disability insurance policies on each other by each of them paying premiums.
What type of agreement do Marsha and Alexis have?
Answer: D
Explanation:
In across-purchase agreement, business partners purchase disability or life insurance policies on each other.
If one partner becomes disabled, the other partner uses the proceeds from the insurance to buy out the disabled partner's share in the business. Marsha and Alexis have agreed to purchase disability insurance policies on each other, with each paying the premium on the policy for their partner. This structure aligns with the cross-purchase format, where each partner independently holds the policy on the other, as described in LLQP materials on business continuation planning. The other options, such as an entity purchase agreement, involve the business purchasing the policy, which is not the case here.
NEW QUESTION # 86
......
One of the best features of IFSE Institute LLQP exam dumps is its discounted price. Our IFSE Institute LLQP Exams prices are entirely affordable for everyone. We guarantee you that no one can beat us in terms of LLQP Exam Dumps prices. Get any IFSE Institute LLQP exam dumps format and start preparation with confidence.
Free LLQP Practice: https://www.getvalidtest.com/LLQP-exam.html
2026 Latest GetValidTest LLQP PDF Dumps and LLQP Exam Engine Free Share: https://drive.google.com/open?id=1vpjSs9J45voy3-pJJbybuXmExdaPPPGT