Our AFP-Exam-1 study practice guide takes full account of the needs of the real exam and conveniences for the clients. Our AFP-Exam-1 certification questions are close to the real exam and the questions and answers of the test bank cover the entire syllabus of the real exam and all the important information about the exam. Our AFP-Exam-1 Learning Materials can stimulate the real exam's environment to make the learners be personally on the scene and help the learners adjust the speed when they attend the real AFP-Exam-1 exam.
| Section | Objectives |
|---|---|
| Insurance and Risk Management | - Life and health insurance fundamentals - Risk mitigation strategies in financial planning |
| Taxation Concepts | - Personal income tax principles - Tax-efficient investment strategies |
| Financial Planning Foundations | - Financial planning process and client relationship management - Ethics and professional standards in financial advising |
| Retirement Planning | - Retirement savings vehicles and planning principles |
| Investment Planning | - Asset allocation and portfolio basics - Investment products and risk-return profiles |
>> Valid AFP-Exam-1 Test Pattern <<
With the collection of AFP-Exam-1 real questions and answers, our website aim to help you get through the real exam easily in your first attempt. There are AFP-Exam-1 free demo and dumps files that you can find in our exam page, which will play well in your certification preparation. We give 100% money back guarantee if our candidates will not satisfy with our AFP-Exam-1 vce braindumps.
NEW QUESTION # 114
Bill was recently declined for a loan application at his financial institution, and he is concerned that a liability has been added to his credit bureau that does not belong to him. He asks his financial planner to review his credit bureau with him to help him identify why he may have been declined. Which area of the credit bureau might his financial planner advise Bill to review?
Answer: D
Explanation:
Bill should review the account history section of the credit bureau. If a liability has been added that does not belong to him, it would normally appear as an account entry showing creditor name, account type, balance, payment status, opening date, and ownership or responsibility. Inquiries show who accessed the credit file, not whether an incorrect liability exists. Public record information may show bankruptcies, judgments, liens, or collections, but the question specifically asks about a liability added to the bureau. The number of previous declines is not the relevant bureau section for identifying a disputed account. The planner should advise Bill to obtain the full credit report, identify unfamiliar accounts, contact the credit bureau and creditor, and dispute inaccurate information in writing. Accurate credit reporting is critical before another loan application. Study Guide focus: credit bureau review, account history, credit disputes, borrowing capacity, and liability management. A documented dispute process is important because unresolved bureau errors can affect pricing, approval, and future borrowing capacity.
NEW QUESTION # 115
Suzy, age 45, is meeting with a financial planner as she has recently inherited $1.25 million from her late aunt. Suzy has poor spending habits and would like to review options that would safeguard and help her receive stable cash flows. She does not have a lot of experience investing and would like to avoid making day- to-day investment decisions. Which type of investment account is most appropriate for Suzy?
Answer: D
Explanation:
Suzy's facts point to income certainty and behavioural protection. She has inherited significant capital, admits poor spending habits, wants stable cash flow, lacks investment experience, and does not want day-to-day investment decisions. A straight life annuity converts a lump sum into predictable income for life, reducing the risk that she spends the inheritance too quickly or makes unsuitable investment decisions. A separately managed, multi-mandate managed, or discretionary fee-based account may delegate investment decisions, but those structures still expose her to market fluctuation and do not automatically impose a stable lifetime income discipline. The trade-off is that a straight life annuity may provide limited estate value and little liquidity after purchase, so the planner should consider whether only part of the inheritance should be annuitized. Among the options, however, the annuity best matches the stated need. Study Guide focus:
annuities, behavioural risk, retirement income products, capital preservation, and cash-flow certainty. The planner should reserve liquid capital separately if Suzy needs emergency funds or future discretionary purchases.
NEW QUESTION # 116
Mina has $20,000 in a savings account earning 3% before tax. She also has a $9,000 credit card balance at
22%, a $7,000 unsecured line of credit at 10%, and a $14,000 car loan at 4%. Her marginal tax rate is 35%.
Which liability should she target first?
Answer: C
Explanation:
The credit card is the highest-cost non-deductible liability and should be the first repayment target, subject to retaining an adequate emergency reserve. Mina's savings account produces only 3% before tax, or 1.95% after tax at a 35% marginal rate. That return is overwhelmed by a 22% credit card rate. Paying the card produces a risk-free improvement equal to avoided interest; no conservative investment can justify carrying that balance. Option A is lower priority because the car loan rate is modest. Option C is important but still secondary to the credit card. Option D ignores the after-tax spread between savings income and debt cost. The planning principle is not simply "pay debt"; it is to compare after-tax investment returns with after-tax borrowing costs, prioritizing expensive consumer debt while preserving liquidity. The planner should then structure a repayment plan and address the spending pattern that created the balance. References/topics: debt prioritization, cash flow, after-tax return, asset and liability management.
NEW QUESTION # 117
Keitaro, age 42, and Ruth, age 52, are married and have two children - Maximo, age 20, and Hannah, age 16, both from Keitaro's previous marriage. In the event Keitaro dies, he would like to minimize taxes, provide for Ruth for the remainder of her life, and then after her death leave the residual to his children. What estate planning strategy should his financial planner recommend to help Keitaro achieve his goal?
Answer: D
Explanation:
A testamentary spousal trust is the best strategy for Keitaro's blended-family objective. It can provide Ruth with income for life, defer tax on assets transferred at death to a qualifying spouse or spousal trust, and preserve the remaining capital for Maximo and Hannah after Ruth's death. The trust is created through Keitaro's will, so it is testamentary, not inter vivos. The children should be capital beneficiaries, not income beneficiaries during Ruth's lifetime, because the goal is to provide for Ruth first and leave the residual to the children later. Naming the children as income and capital beneficiaries while Ruth is alive would undermine the spousal-trust rollover requirements and the planning objective. The planner should refer Keitaro to an estate lawyer to draft the trust terms precisely. Study Guide focus: testamentary spousal trusts, blended-family planning, spousal rollover, income beneficiary, and capital remainder. The will should also address trustee powers, encroachment rights, tax filings, and the treatment of registered assets.
NEW QUESTION # 118
Janet's non-registered account holds the funds listed in the following table: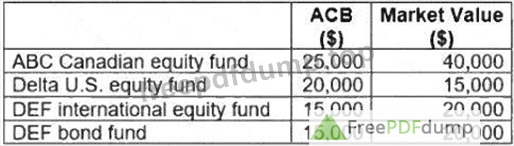
Assuming a marginal tax rate of 45%, what amount of tax payable will Janet incur if she redeems the account to fund the purchase of a new business?
Answer: D
Explanation:
Janet's taxable result comes from the net realized capital gain, not from the total market value redeemed. The ABC Canadian equity fund has a $15,000 gain, the Delta U.S. equity fund has a $5,000 loss, the DEF international equity fund has a $5,000 gain, and the DEF bond fund has a $5,000 gain. Net capital gains are therefore $20,000 after offsetting the Delta loss. Only one-half of the net capital gain is taxable under the standard capital gains inclusion treatment used in AFP-level calculations, producing a $10,000 taxable capital gain. At a 45% marginal tax rate, the tax payable is $4,500. Option A taxes the full net gain; option C and option D reflect incorrect inclusion or arithmetic assumptions. The purpose of the question is to test disposition analysis in a non-registered account and the sequence of gain/loss netting before applying the marginal rate. Study Guide focus: adjusted cost base, fair market value, capital gains inclusion, and non- registered tax planning.
NEW QUESTION # 119
......
FreePdfDump is offering very reliable AFP-Exam-1 real questions answers. Our key advantages are that 1. We get first-hand information; 2. We provide one –year free updates; 3. We provide one-year customer service; 4. Pass guaranteed; 5. Money back guaranteed and so on. Purchasing our AFP-Exam-1 Real Questions answers will share worry-free shopping. If you fail exam with our exam questions, you just need to send your AFP-Exam-1 failure score scanned to our email address, we will full refund to you soon without any other doubt.
Reliable AFP-Exam-1 Braindumps Questions: https://www.freepdfdump.top/AFP-Exam-1-valid-torrent.html