Our AFP-Exam-1 training materials impressed all our customers by the help as well as our after-sales services. We offer the most considerate after-sales services for you 24/7 with the help of patient staff and employees. They are all patient and enthusiastic to offer help on AFP-Exam-1 Study Guide. If you have some questions about our AFP-Exam-1 exam braindumps, ask for our after-sales agent, they will solve the problems for you as soon as possible.
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Tax Planning | 14% | - Income Tax Fundamentals - Registered Plans - Tax Deductions and Credits - Tax-Efficient Strategies |
| Topic 2: Retirement Planning | 17% | - Registered Retirement Savings Plans - Pension Plans - Retirement Income Strategies - Retirement Needs Analysis |
| Topic 3: Estate Planning | 13% | - Estate Transfer Strategies - Wills - Trust and Beneficiary Planning - Powers of Attorney |
| Topic 4: Investment Planning | 17% | - Asset Allocation - Portfolio Construction - Investment Products - Investment Theory |
| Topic 5: Client Relationship and Practice Management | 6% | - Communication and Advisory Process - Client Discovery - Practice Management |
| Topic 6: Asset and Liability Management | 11% | - Debt Management - Personal Balance Sheet Analysis - Budgeting - Cash Flow Management |
| Topic 7: Risk Management and Insurance | 12% | - Risk Transfer Strategies - Life Insurance - Disability and Health Insurance - Risk Assessment |
| Topic 8: Professional Conduct and Regulatory Compliance | 10% | - Regulatory Requirements - Compliance Responsibilities - Ethics and Professional Standards |
>> Valid CSI AFP-Exam-1 Exam Questions <<
The TopExamCollection AFP-Exam-1 exam software is loaded with tons of useful features that help in preparing for the exam efficiently. The AFP-Exam-1 questions desktop AFP-Exam-1 exam software has an easy-to-use interface. TopExamCollection provides CSI certification exam questions for desktop computers. Before purchasing, you may try a free demo to see how it gives multiple CSI AFP-Exam-1 Questions for CSI certification preparation. You may schedule the CSI AFP-Exam-1 questions in the AFP-Exam-1 exam software at your leisure and keep track of your progress each time you try the CSI AFP-Exam-1 questions, which preserves your score. However, it is only compatible with Windows.
NEW QUESTION # 10
Todd, a financial planner, is meeting with Vanessa, a new client, to review her investment goals and objectives. During the meeting, Vanessa states that she believes the markets are very efficient and should reflect all available information in the price of securities. She is looking for an investment option that will reflect a similar level of risk and return characteristics as the Canadian market. What investment option should Todd recommend with Vanessa that would reflect her opinions?
Answer: B
Explanation:
Vanessa's belief points directly to passive market exposure. If she accepts that markets are efficient and wants risk and return characteristics similar to the Canadian market, an exchange-traded fund tracking a broad Canadian equity index is the most consistent recommendation. An ETF can provide diversified Canadian market exposure, transparent holdings, intraday liquidity, and typically lower management cost than many actively managed strategies. A Canadian value mutual fund is an active or style-biased mandate and may depart materially from total market characteristics. A neutral balanced fund includes fixed income and therefore will not mirror the Canadian equity market. A hedge fund may use leverage, short positions, derivatives, or absolute-return strategies, which do not match her stated view. Todd must still confirm KYC information and suitability, but among the options, the Canadian ETF best operationalizes an efficient-market philosophy. Study Guide focus: passive investing, ETFs, diversification, efficient markets, and investment objective alignment. The recommendation should still be framed inside Vanessa's KYC profile rather than presented as a universal market rule.
NEW QUESTION # 11
Jackson, a wealth advisor, is helping Terry, a self-employed IT professional, determine his net income. The goal is to develop a budget and savings strategy for the year ahead Terry has provided the information below: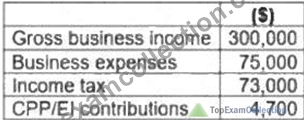
What is Terry's net business income?
Answer: D
Explanation:
Terry's net business income is $225,000. The calculation starts with gross business income of $300,000 and subtracts deductible business expenses of $75,000. Income tax is not deducted in computing net business income for this purpose; it is calculated after taxable income is determined. CPP/EI contributions are also not treated as ordinary business expenses in this basic net business income calculation. Option A and option B incorrectly subtract personal tax and statutory contribution amounts. Option D subtracts the CPP/EI amount from business profit but still incorrectly treats it as part of the business-income calculation. The planner needs the correct net business income figure because it drives budgeting, savings capacity, tax installments, retirement contribution planning, insurance affordability, and debt-service analysis. AFP cash-flow work separates business operating results from personal tax payments and after-tax cash flow. Study Guide focus:
self-employment income, deductible business expenses, net income, tax planning, and budgeting.
NEW QUESTION # 12
What financial information would Deandra a financial planner, analyze in order to increase her client's net worth by decreasing expenses?
Answer: C
Explanation:
A budget is the appropriate tool when the objective is to increase net worth by reducing expenses. The net worth statement shows assets minus liabilities at a point in time; it identifies the result but not the spending pattern that caused it. A current cash-flow statement records actual inflows and outflows, but the budget is the forward-looking control document used to set limits, redirect discretionary spending, and create planned savings. An expense report may list costs, but it does not necessarily connect those costs to income, goals, debt repayment, or savings targets. Deandra should analyze the client's budget to identify spending categories that can be reduced or eliminated and to quantify the effect on monthly surplus. In AFP planning, net worth improves when cash-flow surplus is consistently applied to debt reduction, saving, or investment. Study Guide focus: budgeting, net worth improvement, expense management, cash-flow planning, and implementation monitoring. The budget also creates the monitoring benchmark for whether the client actually changes spending behaviour after the meeting.
NEW QUESTION # 13
Ali wishes to retire in five years. His financial planner calculates that he needs to save an additional $40,000 to meet his retirement income objectives. What would Ali's financial planner advise him to do in order to meet his retirement income objectives?
Answer: B
Explanation:
With only five years until retirement, Ali's planner should recommend reducing current expenses and redirecting the freed cash flow to retirement savings. The short time horizon makes aggressive corrective strategies dangerous. Borrowing through a mortgage to invest introduces leverage risk and could worsen retirement security if markets underperform. Increasing equity exposure solely to chase a higher return may be inconsistent with the time horizon and risk capacity. Whole life insurance is not an efficient solution for a near-term retirement savings shortfall; it combines insurance and investment features but does not directly solve a five-year funding gap. Expense reduction is controllable, immediate, and aligned with the identified
$40,000 savings need. The planner should quantify how much monthly savings is required and monitor progress annually. Study Guide focus: retirement shortfall strategies, savings rate, time horizon, risk capacity, leverage risk, and expense management. The recommendation is conservative because the closer the retirement date, the less time Ali has to recover from investment error.
NEW QUESTION # 14
Edward's client is updating his will and is concerned what will happen to his and his wife's estates should they die within a short time of each other. Which clause in the will should Edward recommend the couple discuss with their lawyer?
Answer: B
Explanation:
A survivorship clause addresses the risk that spouses or beneficiaries die within a short period of each other.
The clause normally requires a beneficiary to survive the testator by a specified number of days before inheriting. Without such a clause, assets may pass through one estate and then almost immediately through another, increasing administration complexity, probate exposure, and possible distribution results that do not match the couple's intentions. A conversion clause is not the standard will clause for this issue. A life interest gives someone use or income from property for life, which is a different estate-planning tool. A successor designation may apply to certain registered or TFSA arrangements, but the will provision for near- simultaneous deaths is survivorship. Edward should advise the client to discuss survivorship wording with a lawyer because provincial legislation and drafting precision matter. Study Guide focus: wills, survivorship clauses, estate administration, simultaneous death planning, and beneficiary succession.
NEW QUESTION # 15
......
Our AFP-Exam-1 exam questions have a lot of advantages. First, our AFP-Exam-1 practice materials are reasonably priced with accessible prices that everyone can afford. Second, they are well-known in this line so their quality and accuracy is unquestionable that everyone trusts with confidence. Third, our AFP-Exam-1 Study Guide is highly efficient that you have great possibility pass the exam within a week based on regular practice attached with the newest information.
AFP-Exam-1 Reliable Exam Vce: https://www.topexamcollection.com/AFP-Exam-1-vce-collection.html